


EN
Canada Drug Approval Might Change The Case For Investing In Cytokinetics Stock (CYTK)
- Cytokinetics reported that Health Canada authorized MYQORZO (aficamten) for adult NYHA class II to III obstructive hypertrophic cardiomyopathy, supported by positive SEQUOIA-HCM Phase 3 data and a boxed warning requiring echocardiographic monitoring.
- Fresh ACACIA-HCM findings for non obstructive HCM showed multi domain exercise and symptom gains, underscoring how MYQORZO could broaden Cytokinetics' cardiomyopathy franchise beyond a single oHCM label.
- We will look at how Cytokinetics' investment narrative evolves as MYQORZO gains Health Canada approval based on SEQUOIA-HCM data.
Cytokinetics Investment Narrative Recap
The big idea you need to buy into with Cytokinetics is that MYQORZO becomes a real cardiomyopathy franchise anchor, with additional myosin modulators filling in around it. Health Canada’s authorization supports that narrative by reinforcing consistent oHCM labeling across major markets and leaning on SEQUOIA-HCM data, but it does not change that the business is still loss making with negative equity today.
In the near term, the key operational swing factor remains execution on the global roll out and payer access for MYQORZO, especially in markets already approved. The biggest risk is that uptake runs slower than the cost base and debt burden, which could keep cash burn and potential dilution elevated even as new approvals like Canada stack up.
The most relevant recent update for this story is Cytokinetics’ plan to file a supplemental new drug application for aficamten in non obstructive HCM after ACACIA-HCM hit its endpoints. If regulators accept that package and move it forward, MYQORZO shifts from a single oHCM product to a broader HCM platform that leans on the same commercial footprint.
The same announcement also highlighted that no new safety signals were identified in ACACIA-HCM, while the company continues to invest in additional myosin activators and inhibitors. For investors, that clusters the main near term catalysts around regulatory decisions in nHCM and continued launch metrics in oHCM. The core execution risk is that operating expenses stay heavy if those cardiology assets do not scale as planned.
Cytokinetics' current analyst narrative points to revenues of US$1.0b and earnings of US$178.9 million by 2029, built on yearly revenue growth of 114.3% and a swing in earnings of roughly US$1.0b from an earnings loss of US$829.6 million today.
Uncover why Cytokinetics' fair value indicates a 73% potential upside to its current price, which could narrow quickly.
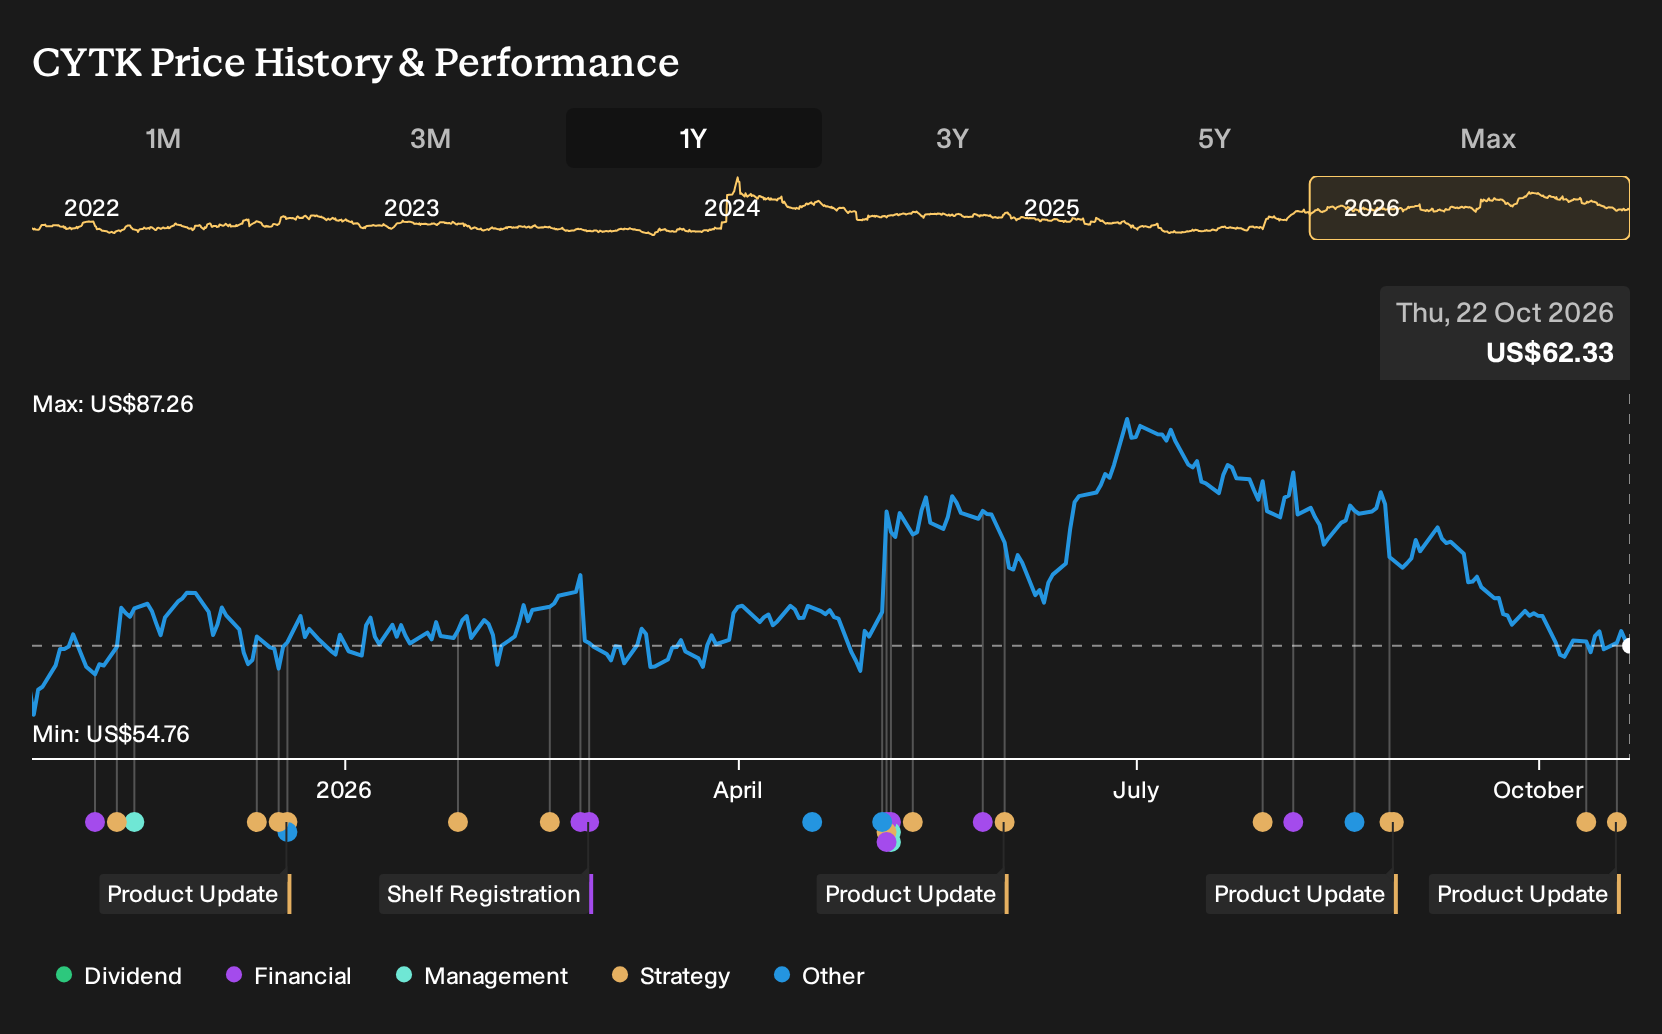
Exploring Other Perspectives
One alternate angle focuses on cardiac safety concerns in aficamten titration rather than the headline of new approvals. The most cautious Cytokinetics analysts were working off revenue assumptions of about US$956.3 million and earnings of US$164.5 million by 2029, yet still framed the story as high risk. Those views came before this Health Canada decision, so opinions may shift as investors compare them with the new development.
Explore 2 other Cytokinetics fair value estimates, including one that suggests it could be worth just $107.80!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cytokinetics research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cytokinetics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cytokinetics' overall financial health at a glance.
Looking for more Cytokinetics sized ideas?
If the MYQORZO narrative has you rethinking how you build exposure to cardiology, biotech or wider healthcare, it can help to line Cytokinetics up against a broader watchlist of potential opportunities.
- For readers who care most about quality at a reasonable entry point, scan a carefully filtered group of 29 high quality undervalued stocks that pair fundamentals with compressed market expectations.
- If balance sheet strength is your non negotiable, focus on businesses in the list of solid balance sheet and fundamentals (26 results) and compare their financial footing with what you see at Cytokinetics.
- For those willing to look earlier in the life cycle for potential upside, review a curated 9 elite penny stocks with strong financials that screens for smaller companies with more robust financial traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com