


EN
Caught Out By Magellan Financial Group's Slide? What Bears Saw
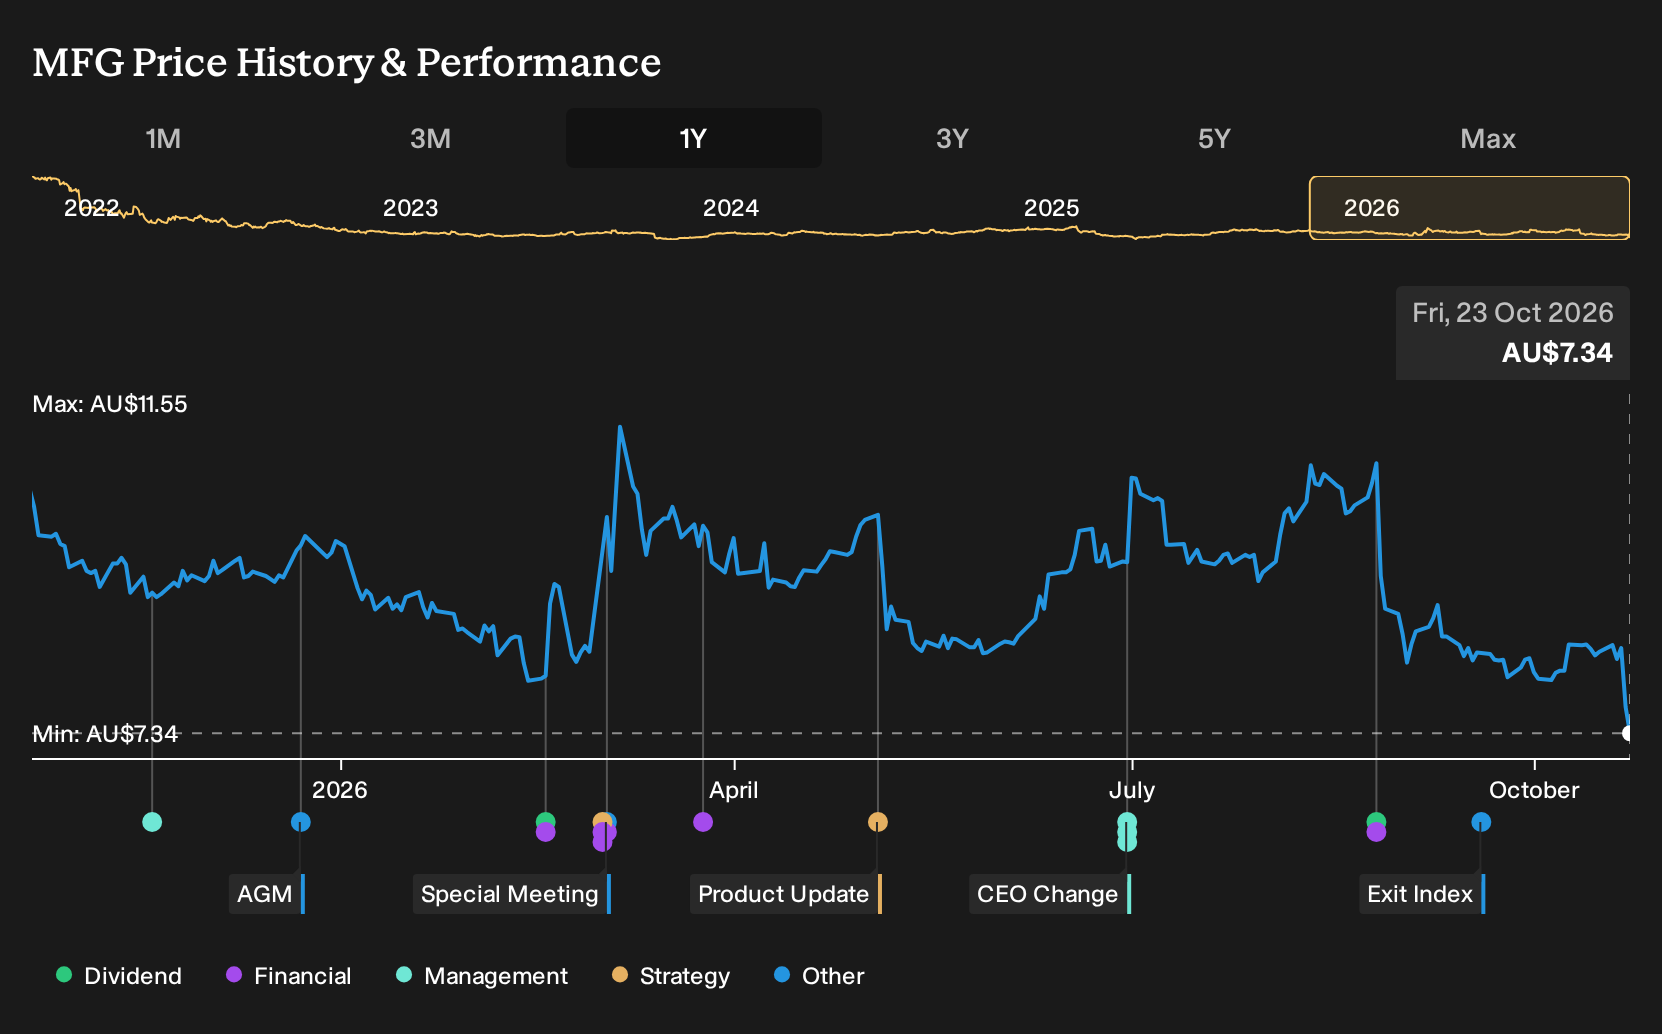
If you had looked at Magellan Financial Group in late 2025 and decided to sit out the bullish talk about Asia Pacific wealth and digital transformation, the past year would have felt very different to owning it. For Magellan Financial Group shareholders, the loss over the past year was 21.6%, including dividends. With that result now fixed, which pre merger warnings about fee pressure, concentrated products and ongoing outflows do you think deserved closer scrutiny at the time?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Magellan Financial Group has already moved. See which of 5 high quality undervalued stocks still trade below our estimates.
The Two Magellan Financial Group Stories Investors Had To Price
The shares cost A$10.45 at the start of the period. Anyone weighing Magellan Financial Group then had to decide which story felt more plausible based on fees, flows and digital change.
The optimistic case pinned Fair Value at A$12. It assumed revenue would decline 1.8% a year, while the profit margin climbed to 60.2% and the business earned a 12.5x future P/E.
The cautious view put Fair Value at A$7.65. That scenario expected revenue to fall 13.3% annually, with margin reaching 53.2% and a 13.1x future P/E despite fee pressure and digital disruption risk.
What The Results Changed For The Magellan Financial Group Debate
Magellan Financial Group’s merger with Barrenjoey created a broader fee pool across investment management, financial markets and corporate finance, which gave the optimistic story fresh support. The hard numbers told a different tale. Total revenue fell from A$141.3m in H2 2025 to A$75.5m in H2 2026, with net income dropping and net margin moving from 50.3% to 25.1%. Overall, the evidence leaned toward the cautious case.
The core assumption on trial was resilience of fees and margins. For any other asset manager, you would now watch the direction of funds under management, the average fee rate and the reported net margin each half year. Then you would compare those lines to whatever revenue and profitability story investors are paying for.
What Magellan Financial Group’s Price Now Asks You To Believe
Magellan Financial Group trades at A$7.34 today, after a loss of 21.6% over the past year from A$10.45. The selected Narrative’s Fair Value sits above the current price and is based on a rebuilding story rather than a quick fix.
Leadership change, partnerships and offshore expansion sit at the center of that thesis. For this higher figure to be reached, a buyer today would need to assume new management turns those initiatives into steadier earnings despite ongoing fee and outflow pressure.
"The appointment of Sophia Rahmani as CEO and the stabilization of leadership positions MFG for enhanced business stability and client trust, potentially improving earnings through better management and strategic execution. Strategic partnerships, particularly with Vinva Investment Management, are poised to significantly drive MFG’s next phase of growth, likely increasing revenue and expanding the firm’s AUM through new fund offerings."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Magellan Financial Group
Thinking about Magellan Financial Group points you toward fund flows and fees. One step away, a quieter kind of financial plumbing matters.
Investors move cash between funds, brokers and banks. Behind those everyday choices sits a payments platform that helps money travel digitally.
It focuses on processing transactions efficiently and turning frequent usage into surplus cash. Instead of holding large loan books, it relies on partner banks for funding.
That model can leave more room to repurchase shares and invest in software tools. As digital payments spread through commerce and transfers, its role could quietly grow.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 43% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com