


EN
Horace Mann Educators (HMN) Stock Looks Priced At A Premium As Shares Rose 66%
Horace Mann Educators has quietly produced a 65.8% return over the past three years, yet its share price around US$47 still raises a basic question for investors who care about how efficiently a business turns capital into profits. With the latest headlines pointing to strong reported earnings but softer profitability metrics than many insurance peers, the focus naturally shifts to whether the returns Horace Mann Educators earns on its capital are enough to justify where the stock trades today.
- The 65.8% share price gain over three years puts real weight on the idea that Horace Mann Educators is using shareholder capital productively enough to support that kind of compounding.
- Recent record earnings and higher earnings expectations can support the case that Horace Mann Educators may be improving how effectively it converts its capital base into profits, even as its 6.8% return on equity trails a sector average near 12.5%.
- If you'd rather focus on earnings, this one's for you. See why Horace Mann Educators's 10.8x P/E tells a different valuation story.
The issue now is whether the returns Horace Mann Educators currently earns on its capital are strong and durable enough to make the present share price look sensible.
To compare Horace Mann Educators with other businesses through the lens of the returns they generate on their capital, a focused starting point is a screener of 29 high quality undervalued stocks.
Does Horace Mann Educators Look Pricey on Excess Returns?
The Excess Returns model looks at how effectively Horace Mann Educators turns each dollar of shareholder equity into profits above its own cost of capital. On this view, the business is assumed to earn Stable EPS of $2.56 per share on a Stable Book Value base of $31.60 per share, implying an Average Return on Equity of 8.09% built around recent history rather than aggressive expansion.
Against that, the Cost of Equity is set at $2.29 per share, which leaves an estimated Excess Return of $0.27 per share on a Book Value of $37.11 per share. That spread is modest, so the model outputs an intrinsic value that is meaningfully below the current share price of $47.37, suggesting the market is paying up for qualities that are not fully captured by past returns on equity. Because record Q2 2026 core earnings and a higher full year guidance arrive alongside sector lagging ROE, the premium to the Excess Returns estimate reflects a tension between recent earnings strength and the longer run profitability profile the model assumes. Find out what Horace Mann Educators could be worth using our Excess Returns estimate.
The Horace Mann Educators Narrative: What Would Justify Today's Price?
Narratives for Horace Mann Educators pick up where the valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Instead of leaving you with a single ratio or model output, they map out the future that number relies on so you can watch how the real business lines up against it over time.
One of the top community narratives on Horace Mann Educators: 16% undervalued
"The main thing that has to go right is continued execution on expanding educator and employer focused benefits platforms and distribution reach…"
Discover why this Narrative puts Horace Mann Educators at 16% undervalued.
The Horace Mann Educators share price is only one piece of the puzzle
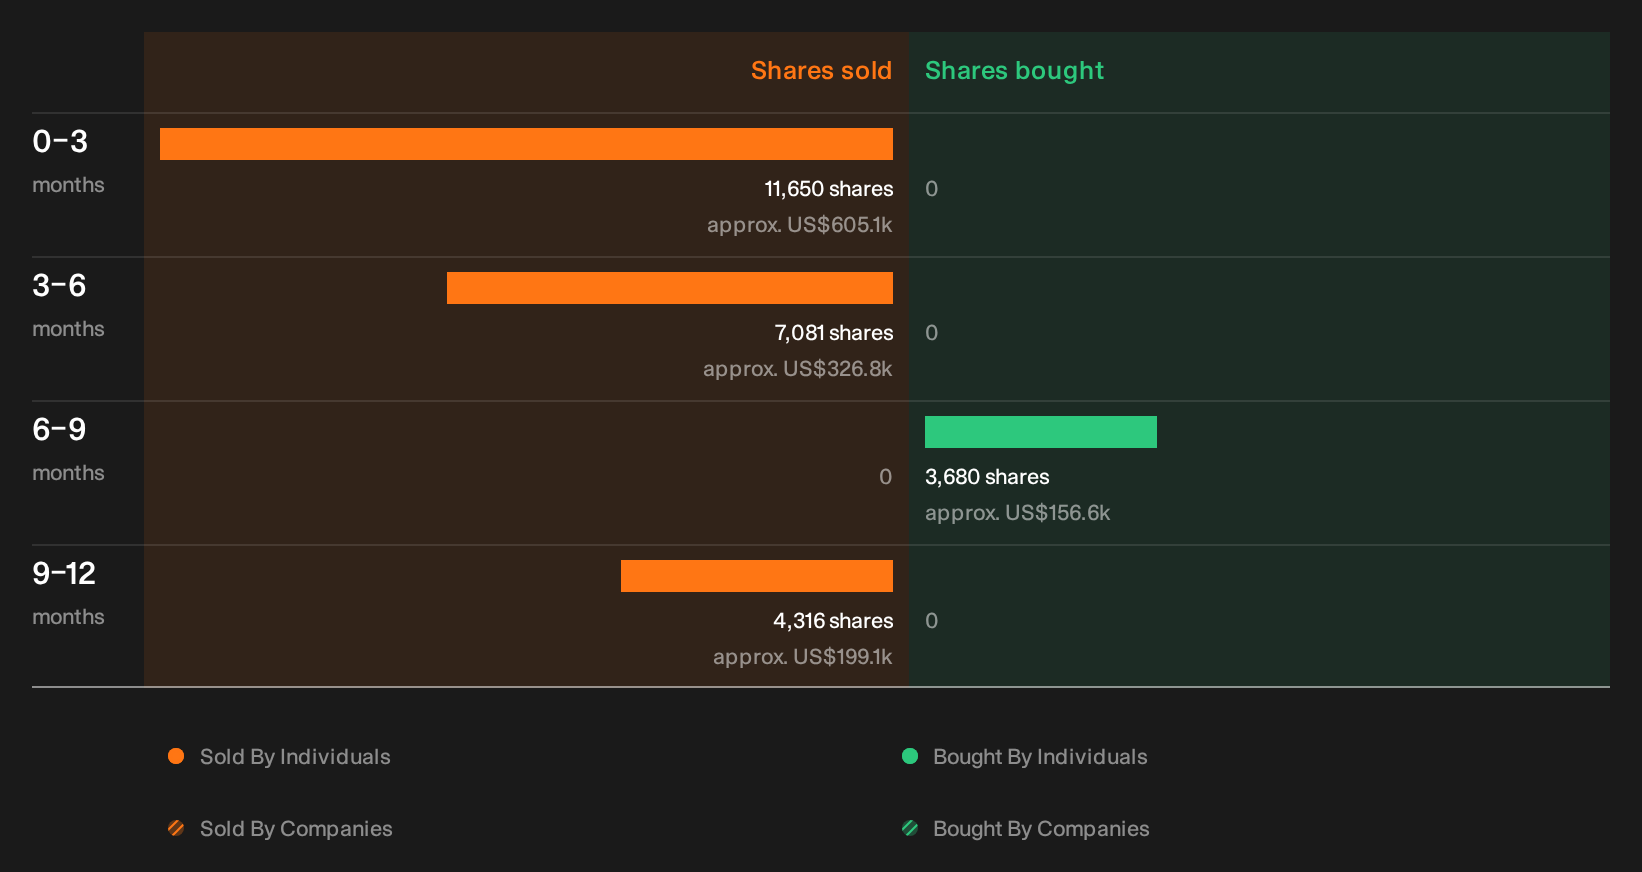
Before you decide how to treat Horace Mann Educators in your portfolio, it is worth knowing that recent insider transactions have shifted in a way our checks have picked up. See the recent insider selling flagged for Horace Mann Educators.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com