


EN
Wind Powered Data Center Deal Could Change The Case For Applied Digital Stock
- Soluna Holdings reported a definitive deal with Applied Digital to form a 51/49 joint venture for a 50 MW AI and HPC data center at the Dorothy 3 site in Texas, with Soluna contributing land and power assets and Applied Digital funding development.
- The project is planned to pair grid access with energy from the 150 MW Briscoe Wind farm, highlighting Applied Digital's push toward lower cost, renewable power for high-density AI workloads while it continues to balance capital needs, long leases, and construction risk.
- We will examine how Applied Digital's investment narrative is influenced by this wind powered AI data center joint venture.
Applied Digital Investment Narrative Recap
To own Applied Digital, you need to believe its heavy build out of AI and HPC campuses can convert large contracted revenue into future cash generation before the balance sheet gets stretched too far. The Soluna joint venture fits that thesis by adding another 50 MW tied to visible power, but on its own it does not change the near term story.
The major near term catalyst still lies in bringing contracted megawatts into service on time and on budget, particularly the hyperscaler leases that underpin roughly US$36b of contracted revenue. The biggest immediate risk remains execution under a high capex, high debt model, with less than one year of cash runway and volatile crypto related demand still in the mix.
The most relevant context around this Soluna deal is Applied Digital’s pivot toward long dated, power backed AI capacity such as the Polaris Forge 1 campus with CoreWeave, which carries an estimated US$7b of 15 year lease commitments. That type of agreement illustrates what investors are ultimately betting Dorothy 3 can resemble over time, even if the terms differ.
Linking Dorothy 3 to a 150 MW wind resource aligns with management’s broader push into lower cost, renewable power that can support dense AI workloads. For you as a shareholder, the key question is whether projects like this come online smoothly enough to support that contracted backlog while offsetting risks from debt, short seller pressure, and any crypto exposure that remains uneven.
Applied Digital's current loss of US$451.8 million is forecast by analysts to move to earnings of US$41.0 million by 2029. This implies an earnings swing of about US$493 million, on top of an expected 57.6% yearly revenue growth rate that would see revenue reach US$3.4 billion by that same year.
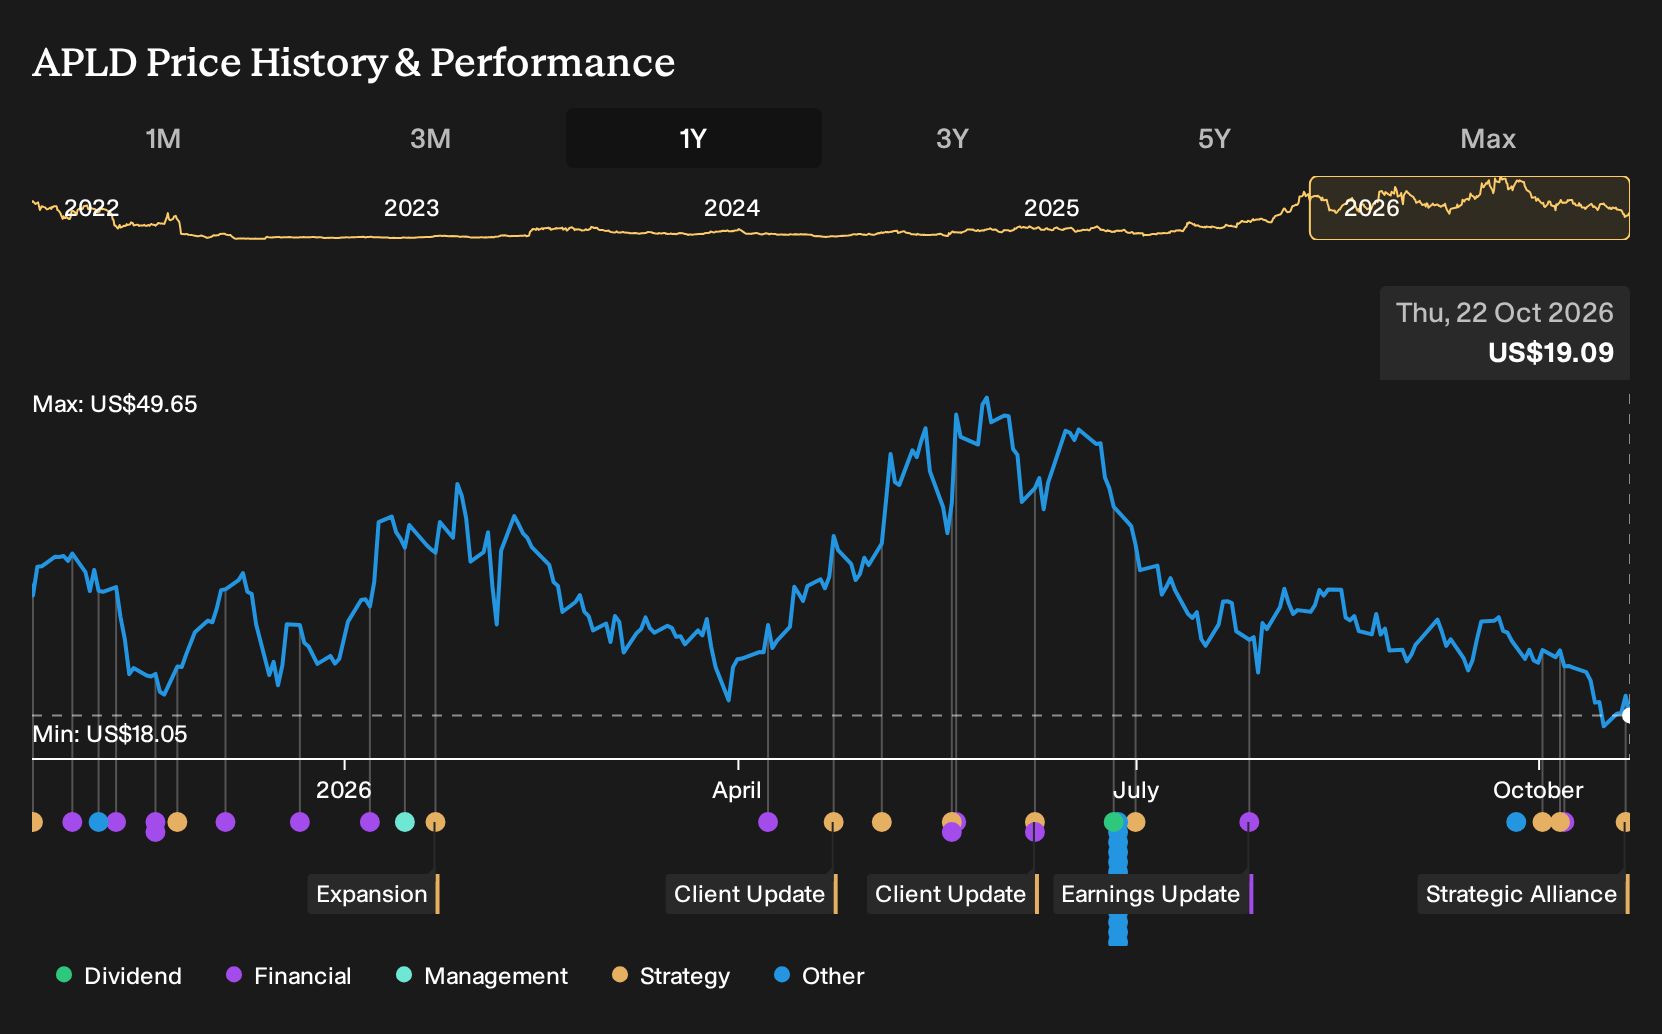
Uncover how Applied Digital's fair value indicates a 227% potential upside to its current price, which could narrow quickly as execution risks clear.
Exploring Other Perspectives
Debt risk looks very different through the most bearish Applied Digital lens. One might focus on the chance that repeated capital raises and interest costs cap any benefit from projects like Dorothy 3. Before this news, the lowest analysts were only penciling in about 34.8% yearly revenue growth to roughly US$2.1b by 2029. That is far more cautious than the consensus and could shift again once this wind powered venture is fully reflected in their models.
Explore 5 other Applied Digital fair value estimates, including one that suggests it could be worth just $25.32!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking For More Ideas Beyond Applied Digital?
If the Applied Digital story has you thinking about position sizing, risk and where to find your next opportunity, it helps to scan a wider field of candidates with clear financial profiles you can compare side by side.
Use the Simply Wall St Screener to look across different angles of quality, value and resilience, then line those results up against what you see in Applied Digital.
- Prefer potential bargains that also show solid fundamentals and cash generation strength? Take a look at our 29 high quality undervalued stocks for possible candidates that might deserve a place on your watchlist.
- If capital preservation matters as much as return potential, start with companies in the 30 resilient stocks with low risk scores and see which businesses line up with your tolerance for downside.
- For investors hunting for lesser known opportunities with stronger balance sheets and financial quality, the 20 high quality undiscovered gems can surface ideas that are not already crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com