


EN
How Investors May Respond To Kinaxis (TSX:KXS) AI Growth And Undervaluation
- Kinaxis recently drew attention after a discounted cash flow review suggested the intrinsic value of its AI infused supply chain platform business could be substantially higher than the current share price.
- The focus on Kinaxis Maestro, supported by heavy R&D spending and a growing patent base, highlights how management is leaning hard into AI led supply chain orchestration.
- We will look at how Kinaxis's investment narrative is shaped by this perceived DCF undervaluation and its Maestro focused AI strategy.
Scan beyond Kinaxis and its Maestro story by reviewing a curated set of 38 profitable AI stocks that aren't just burning cash that pair real earnings power with AI driven business models.
Kinaxis Investment Narrative Recap
To own Kinaxis, you need to believe its AI infused Maestro platform keeps gaining traction across complex supply chains while the company sustains meaningful R&D at roughly 18% of revenue without eroding profitability too far. The short term swing factor is whether new Maestro use cases and partner led delivery translate into consistent SaaS and ARR expansion.
The biggest near term risk is that investors reassess rich software and AI valuations, since Kinaxis already trades on a higher P/E than the broader North American software industry. The recent DCF work suggesting intrinsic value above the current share price does not materially change that risk or the operational task in front of management.
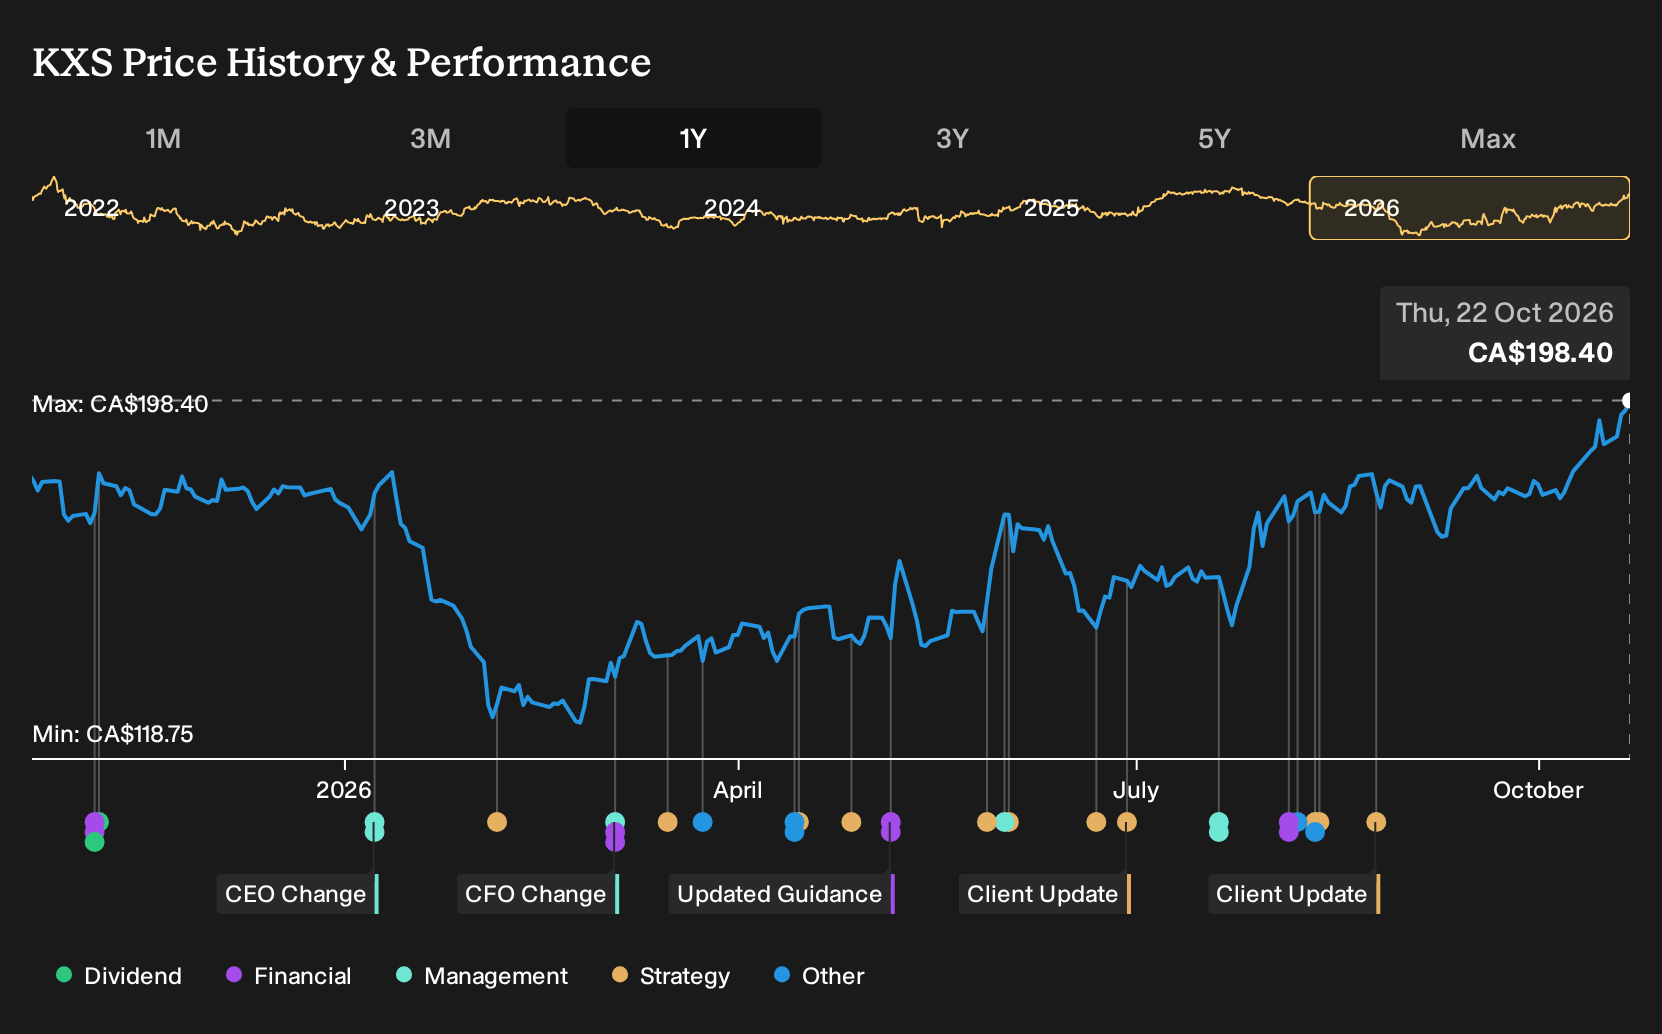
The most relevant recent development is Kinaxis approaching a 52 week high around CA$196.31 while a DCF model still flags a large gap to estimated cash flow value at roughly CA$320.96. The stock has also outperformed the Canadian software sector over the past year, which already reflects a significant level of confidence in Maestro and AI driven orchestration.
For you, the key question is whether Kinaxis can justify both the current P/E of about 44x and any implied DCF upside through actual execution. That means converting early Maestro Agent uptake, new vertical wins in areas like energy and aerospace, and Forward Deployed Engineering projects into durable recurring revenue without profit margins drifting well below the current 14.4% level.
Kinaxis earnings assumptions behind the Maestro story
Kinaxis is being valued on a very specific earnings path, not just a broad story about AI in supply chains. Analysts are working off an assumption that revenue expands by 12.6% per year over the next few years, while profit margins ease from 14.4% today to 12.8% as Maestro development and Forward Deployed Engineering stay front and center.
On that framework, current earnings of US$87.0 million are projected to reach US$109.8 million by 2029. That implies an earnings increase of about US$22.8 million over the period, with consensus estimates flagging US$4.62 in earnings per share and some forecasts reaching as high as US$129.7 million if Maestro adoption runs ahead of the base case.
Kinaxis' current P/E of roughly 42.6x and the implied future multiple of 41.4x hinge on this combination of mid teens margin, double digit top line expansion, and a slowly shrinking share count. Analysts expect outstanding shares to fall about 3.11% annually for the next three years. For you as an investor, the moving parts are clear: the business needs Maestro driven growth to hold close to that 12.6% pace without margin compression running deeper than the forecast 12.8% level.
Kinaxis' narrative projects US$861.0 million revenue and US$109.8 million earnings by 2029. This requires 12.6% yearly revenue growth and an earnings increase of about US$22.8 million from US$87.0 million today.
Uncover why Kinaxis' fair value indicates a 5% potential upside to its current price. That upside could narrow quickly if Maestro execution keeps impressing investors.
Exploring Other Perspectives
One alternate angle you might consider is the bullish catalyst around Maestro driven margin expansion. The most optimistic analysts were already modeling revenue of about US$812.8 million and earnings near US$139.9 million by 2029. Those forecasts pre date the recent DCF spotlight on Kinaxis, so expectations could shift as fresh information lands.
Explore 4 other Kinaxis fair value estimates, including one that suggests as much as 62% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Kinaxis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kinaxis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kinaxis' overall financial health at a glance.
Looking for more investment ideas beyond Kinaxis?
Once you have a view on Kinaxis and its Maestro story, it can help to line that thesis up against other opportunities using the Simply Wall St Screener.
- If you want potential value with quality attached, start by scanning a curated set of 3 high quality undervalued stocks that already pair stronger fundamentals with more modest expectations.
- If capital preservation matters most to you, consider focusing on 8 resilient stocks with low risk scores that our models assess as having more resilient business profiles and lower overall risk scores.
- If balance sheet strength is non negotiable in your process, filter for companies in the list of solid balance sheet and fundamentals (7 results) to see which candidates combine financial robustness with solid operating metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com