


EN
How Reaffirmed Guidance At Equity LifeStyle Properties Has Changed Its Investment Story
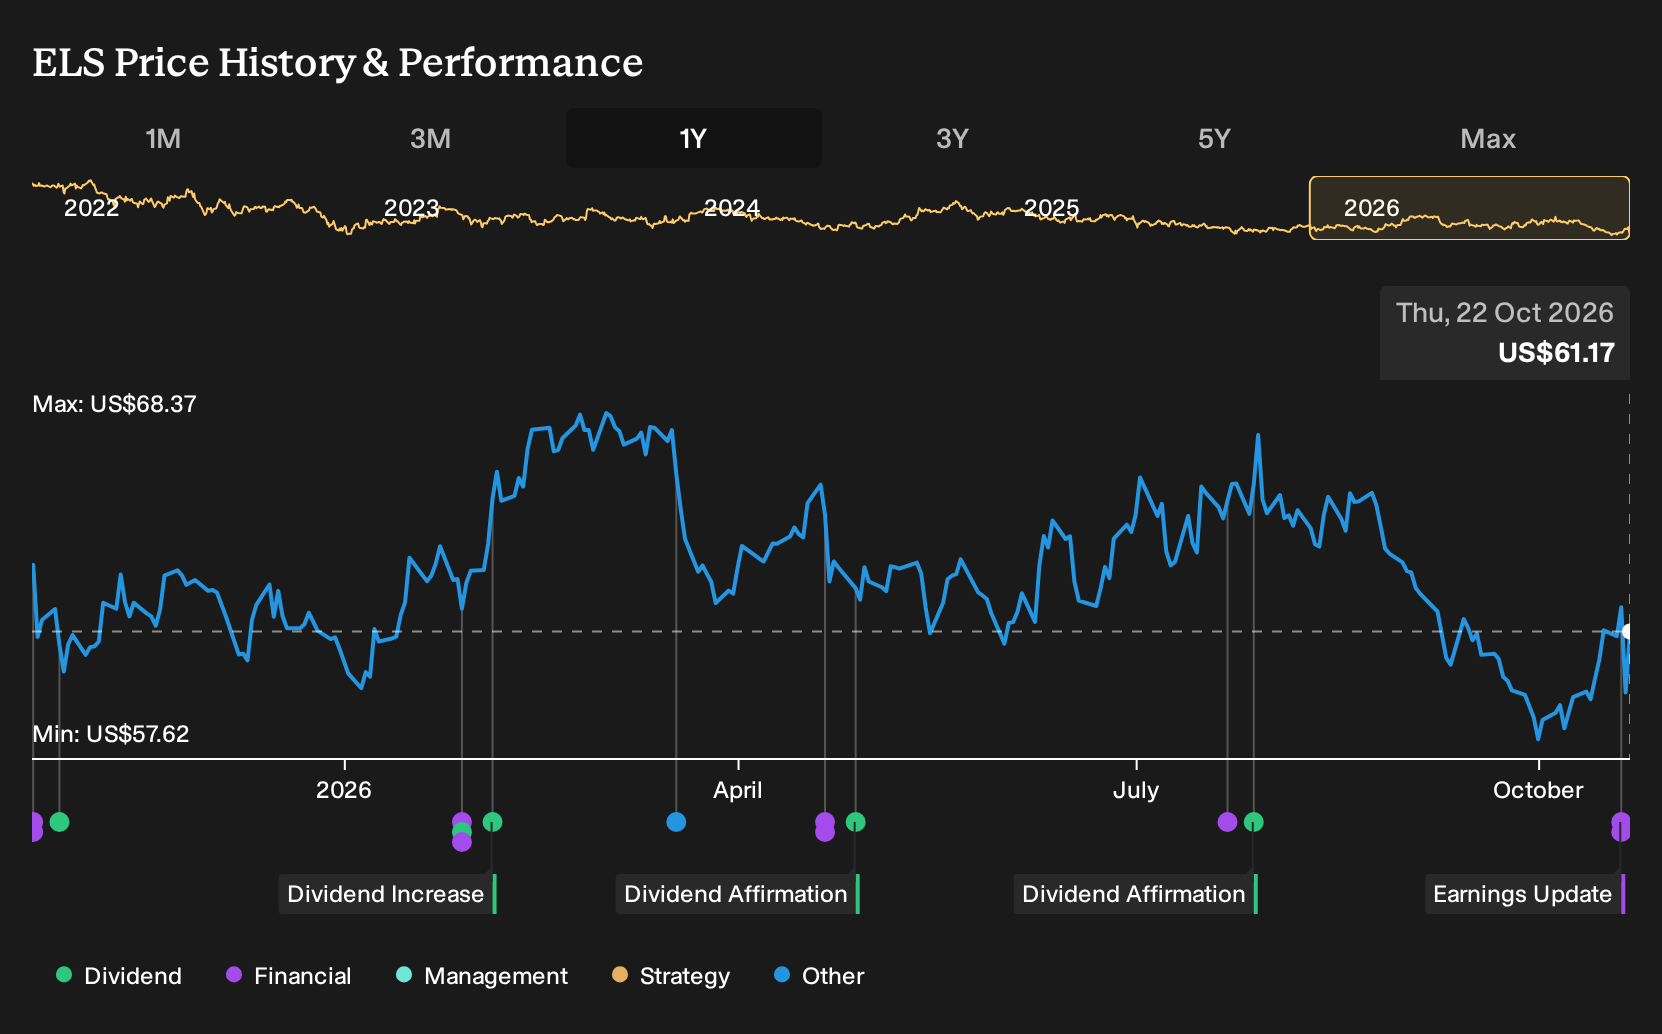
- Equity LifeStyle Properties reported past third quarter 2026 results with revenue of US$409.9 million and net income of US$86.43 million, alongside reaffirmed 2026 guidance and updated per share earnings expectations for the fourth quarter and full year.
- Management highlighted steady normalized FFO and occupancy, membership and rent growth across manufactured housing and RV communities, pointing to resilient resident demand supported by long average stays and limited near term secured debt maturities.
- We will look at how Equity LifeStyle Properties' investment narrative aligns with reaffirmed 2026 guidance and preliminary 2027 rent growth expectations.
Scan beyond Equity LifeStyle Properties and evaluate peers with resilient balance sheets and steady cash generation using our curated list of 30 resilient stocks with low risk scores.
Equity LifeStyle Properties Investment Narrative Recap
To stay invested in Equity LifeStyle Properties, you need to believe that its mix of long stay manufactured housing, annual RV and marina residents can keep offsetting softer transient RV demand. The Q3 print supports that storyline, with revenue and nine month net income both above the prior year despite a quarterly earnings dip.
The key short term swing factor is how quickly hurricane affected marinas and weaker transient RV activity stabilize relative to ongoing rent and occupancy growth. On the risk side, any further weather delays or a more persistent reset in short stay demand would lean against that, although the reaffirmed 2026 guidance suggests no major near term change.
The most relevant update here is management reaffirming 2026 normalized FFO guidance and giving more detail on rent expectations for 2027. Combined with Q3 normalized FFO growth of 4.6% and core NOI up 6.7%, that indicates the operating engine behind the guidance remains tied to rent increases and stable occupancy rather than transient swings.
Preliminary 2027 rent growth planning, including a 5.1% increase for manufactured housing and 4.7% for RVs, matters because it links directly to the same store income story that many shareholders focus on. Execution risk is clearest where guidance has already flagged pressure, particularly flat transient RV revenue in Q4 2026 and the timing of Florida marina repairs.
Equity LifeStyle Properties' current analyst framework points to revenues of US$1.8b and earnings of US$468.3 million by 2029. This is based on assumed yearly revenue growth of 4.1% and an earnings increase of about US$66.5 million from US$401.8 million today.
Uncover why Equity LifeStyle Properties' fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Simply Wall St Community members provide two fair value views for Equity LifeStyle Properties, spanning roughly US$68 to US$87 per share, which already shows how far apart retail investors can be. Those estimates pre date the Q3 2026 update and refreshed 2026 guidance, so you should weigh them against hurricane repair delays, softer transient RV trends, and long stay demand drivers before forming your own view.
Explore another Equity LifeStyle Properties fair value estimate, including one that suggests it could be worth just $68.21.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Equity LifeStyle Properties research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Equity LifeStyle Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Equity LifeStyle Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond Equity LifeStyle Properties?
Once you have formed a view on Equity LifeStyle Properties, it often helps to line it up against other opportunities that fit different goals, from income focus to balance sheet strength or potential mispricing. The Simply Wall St screener can help you quickly filter for businesses that match the risk, quality, and income profile you care about most.
- For investors who want income to do more of the heavy lifting, start with companies that aim to pay sizeable payouts with resilient coverage through our 6 dividend fortresses.
- If capital preservation and financial strength matter most to you, stress test your watchlist with a list of solid balance sheet and fundamentals (26 results) that can better handle tougher conditions.
- When you want to spot potential mispriced opportunities before they are widely discussed, widen your search using our 29 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com