


EN
Neurocrine Biosciences (NBIX) Stock May Be Below Fair Value Following Phase 2 Alzheimer’s Study
Neurocrine Biosciences has delivered steady long term gains for shareholders, and fresh clinical updates keep attention on what the pipeline might mean for profits. The open question for anyone looking at the stock today is how far its current share price can be explained by the earnings that underpin it.
- Over the past 5 years the stock has returned 40.6%, which puts real weight on whether that performance is matched by the strength of its profit stream.
- Recent work on Prader Willi syndrome hyperphagia and a new Phase 2 study in Alzheimer's disease suggest management is leaning into areas that can influence future earnings durability and the timing of cash flows.
- There is a second opinion on Neurocrine Biosciences worth weighing. See what analysts think Neurocrine Biosciences's shares could be worth.
The issue now is whether Neurocrine Biosciences' current share price is appropriately aligned with the earnings profile that investors are paying for.
To evaluate whether Neurocrine Biosciences' earnings justify its current price, it helps to compare it with other biopharma-focused stocks screened for our screener containing 20 high quality undiscovered gems
Does Neurocrine Biosciences Look Undervalued on Earnings?
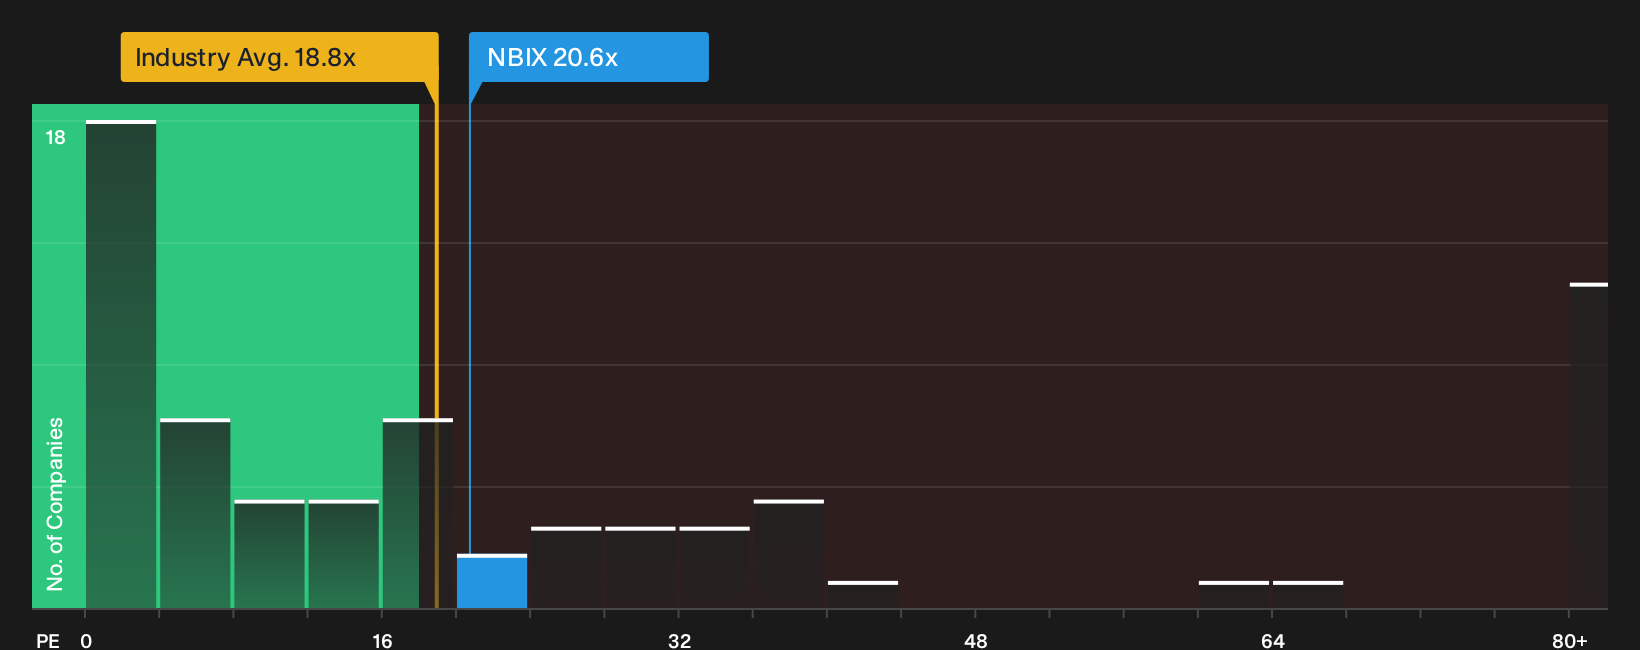
A P/E lens suits Neurocrine Biosciences because earnings already matter more than distant hopes to many investors in the stock. The current P/E sits around 20.6x, which is lower than both the biotech industry average near 18.8x and the broader peer group near 54.5x, so the shares trade below where many higher growth or higher risk biopharma stocks change hands on this metric.
The fair P/E that a tailored model suggests for Neurocrine Biosciences is higher than where the stock trades today. This points to the shares looking undervalued on this earnings yardstick once factors like margins, size and risk profile are blended in. Because the recent launch of VYKAT XR in Prader Willi syndrome gives the earnings line more support from an approved product, the current discount to that fair P/E may reflect investors waiting for more evidence rather than fully paying up for that contribution. Explore the numbers behind Neurocrine Biosciences's P/E valuation.
The Neurocrine Biosciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Neurocrine Biosciences' P/E puzzle leaves off. They spell out the earnings, margin and growth paths that would need to hold for the share price to look meaningfully higher or lower than it does today, and each one turns that implied fair value into a specific thesis about the business that can be tracked over time on the Community page.
One of the top community narratives on Neurocrine Biosciences: 31% undervalued
"Expansion of Neurocrine Biosciences’ commercial portfolio beyond INGREZZA through the launch of CRENESSITY and the acquisition of VYKAT XR, which together supplied about 25% of Q2 2026 revenue…"
Discover why this Narrative puts Neurocrine Biosciences at 31% undervalued.
Neurocrine Biosciences’ valuation still hinges on one quiet variable
Numbers only tell part of the story for Neurocrine Biosciences, because the people deciding where cash goes and how they are rewarded can either reinforce or dilute everything you have just seen. See who runs Neurocrine Biosciences and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com