


EN
Is FDA Warning Letter Altering The Investment Case For Baxter Stock (BAX)?
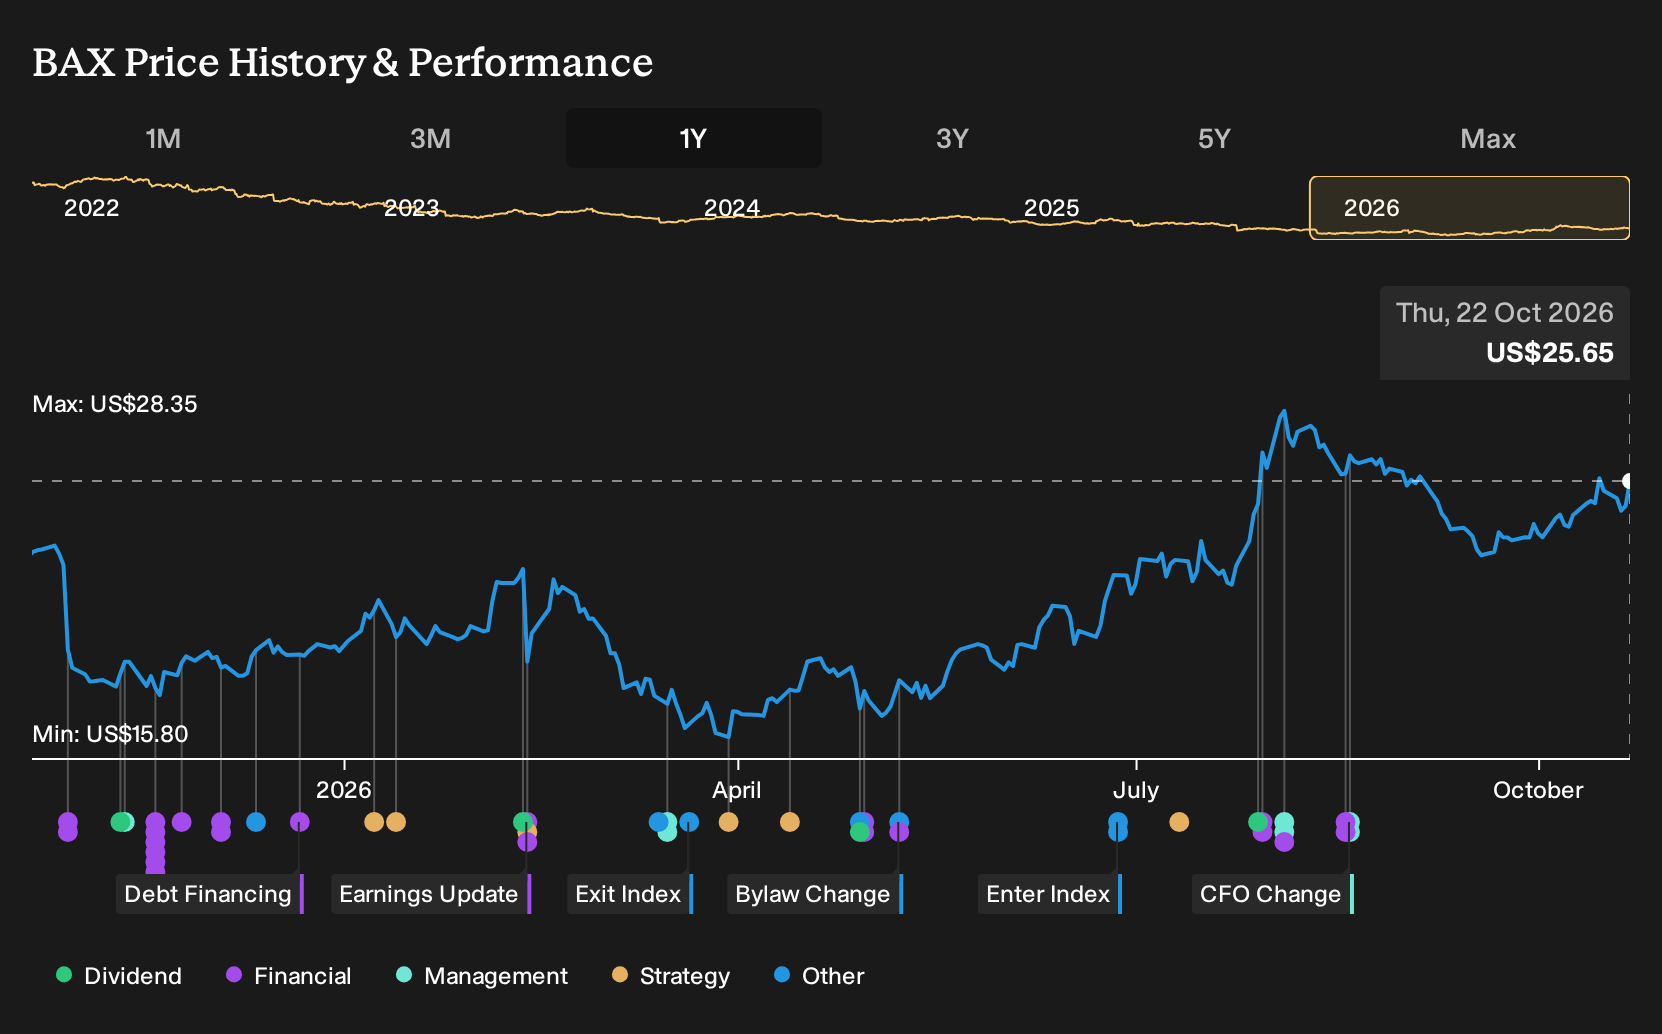
- Baxter International received an FDA warning letter in October 2026 regarding significant Current Good Manufacturing Practice violations at its Round Lake, Illinois injectable drugs facility, including inadequate segregation of cephalosporin production and weaknesses in aseptic processing controls.
- The findings highlight operational and quality control pressures for Baxter International, which may require increased remediation spending, tighter oversight of sterile manufacturing, and closer scrutiny of the reliability of its injectable portfolio for hospital customers.
- We will now examine how Baxter International's investment narrative is affected by the FDA's warning on contamination and sterile manufacturing controls.
Balance quality concerns around Baxter International by scanning a hand-picked 30 resilient stocks with low risk scores designed to keep operational and regulatory risk firmly in check.
Baxter International Investment Narrative Recap
To own Baxter International, you need to believe it can tighten manufacturing quality, keep hospital customers confident in its injectable drugs, and keep pushing its margin recovery plan. The FDA warning letter pulls operational focus toward remediation and away from efficiency work. In the near term, the key swing factor is how quickly the Round Lake issues are contained and production reliability stabilizes.
The biggest risk right now sits squarely in pharmaceuticals, where supply constraints and the Round Lake remediation could overlap. That can strain volumes and mix just as Baxter International is trying to improve earnings quality and chip away at debt. If the financial impact remains contained, the broader turnaround thesis stays largely intact.
With no fresh corporate announcements filed alongside the FDA action, the most relevant reference point is still management’s earlier emphasis on easing regulatory and supply constraints in infusion systems and injectable therapies by 2027. The warning letter directly tests that message. It introduces extra work and scrutiny into an area that was already flagged as operationally tight.
For catalysts, you are now watching two things in parallel. First, any company updates on remediation progress at Round Lake and potential effects on injectable availability. Second, whether Baxter International can keep moving on its decentralization and cost programs while absorbing higher quality related spending. Execution on both fronts will shape how quickly confidence returns.
Baxter International Forecasts Under the Microscope
Baxter International's narrative projects revenues of US$12.4b and earnings of US$788.3m by 2029, which rests on analysts assuming 2.8% yearly revenue growth and an earnings swing of about US$1.76b from a loss of US$968.0m today.
Uncover why Baxter International's fair value indicates a 9% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is earnings power. The most pessimistic analysts were already penciling in only US$691.3m of profit on about US$12.3b of revenue by 2029 for Baxter International, and they saw a lower 19.7x P/E as fair. This FDA warning could push those cautious stories even further, so treat it as a prompt to compare several viewpoints rather than a final verdict.
Explore 4 other Baxter International fair value estimates, including one that suggests there could be as much as 22% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Baxter International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Baxter International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baxter International's overall financial health at a glance.
Looking for more investment ideas beyond Baxter International?
If this Baxter International review sharpened your thinking, the next step is to widen your watchlist with companies that fit the kind of risk and balance sheet profile you want to own.
- For investors who care most about financial strength and resilience, start with a curated list of solid balance sheet and fundamentals (26 results) that keeps balance sheet risk front and center.
- If you want potential mispricing opportunities, compare Baxter International with a hand picked set of quality companies trading on what may be undemanding valuations through the 30 high quality undervalued stocks.
- For investors who prefer to be paid while they wait, focus on income ideas by scanning a group of higher yield opportunities in the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com