


EN
Sales Agent Partnership Might Change The Case For Investing In ZoomInfo Stock (GTM)
- Recent announcements show ZoomInfo working as a core data partner for Salesforce’s Hunter agent, while also rolling out native integrations with n8n, ClickUp, and expanded GTM.AI capabilities through Workbounce that blend external market data with internal customer knowledge.
- Together, these moves push ZoomInfo deeper into customers’ daily workflows, which can influence contract stickiness, data usage intensity, and the economics of how go to market teams run AI driven sales processes.
- We will now look at how ZoomInfo's deeper Salesforce Hunter integration could influence the strength of its investment narrative.
ZoomInfo Technologies Investment Narrative Recap
To own ZoomInfo Technologies, you need to believe its go to market data platform can stay embedded inside large customer workflows as AI agents spread across sales and marketing. The Salesforce Hunter partnership plus fresh integrations with n8n, ClickUp, and Workbounce push usage deeper into daily activity, which could support stickier contracts if execution holds.
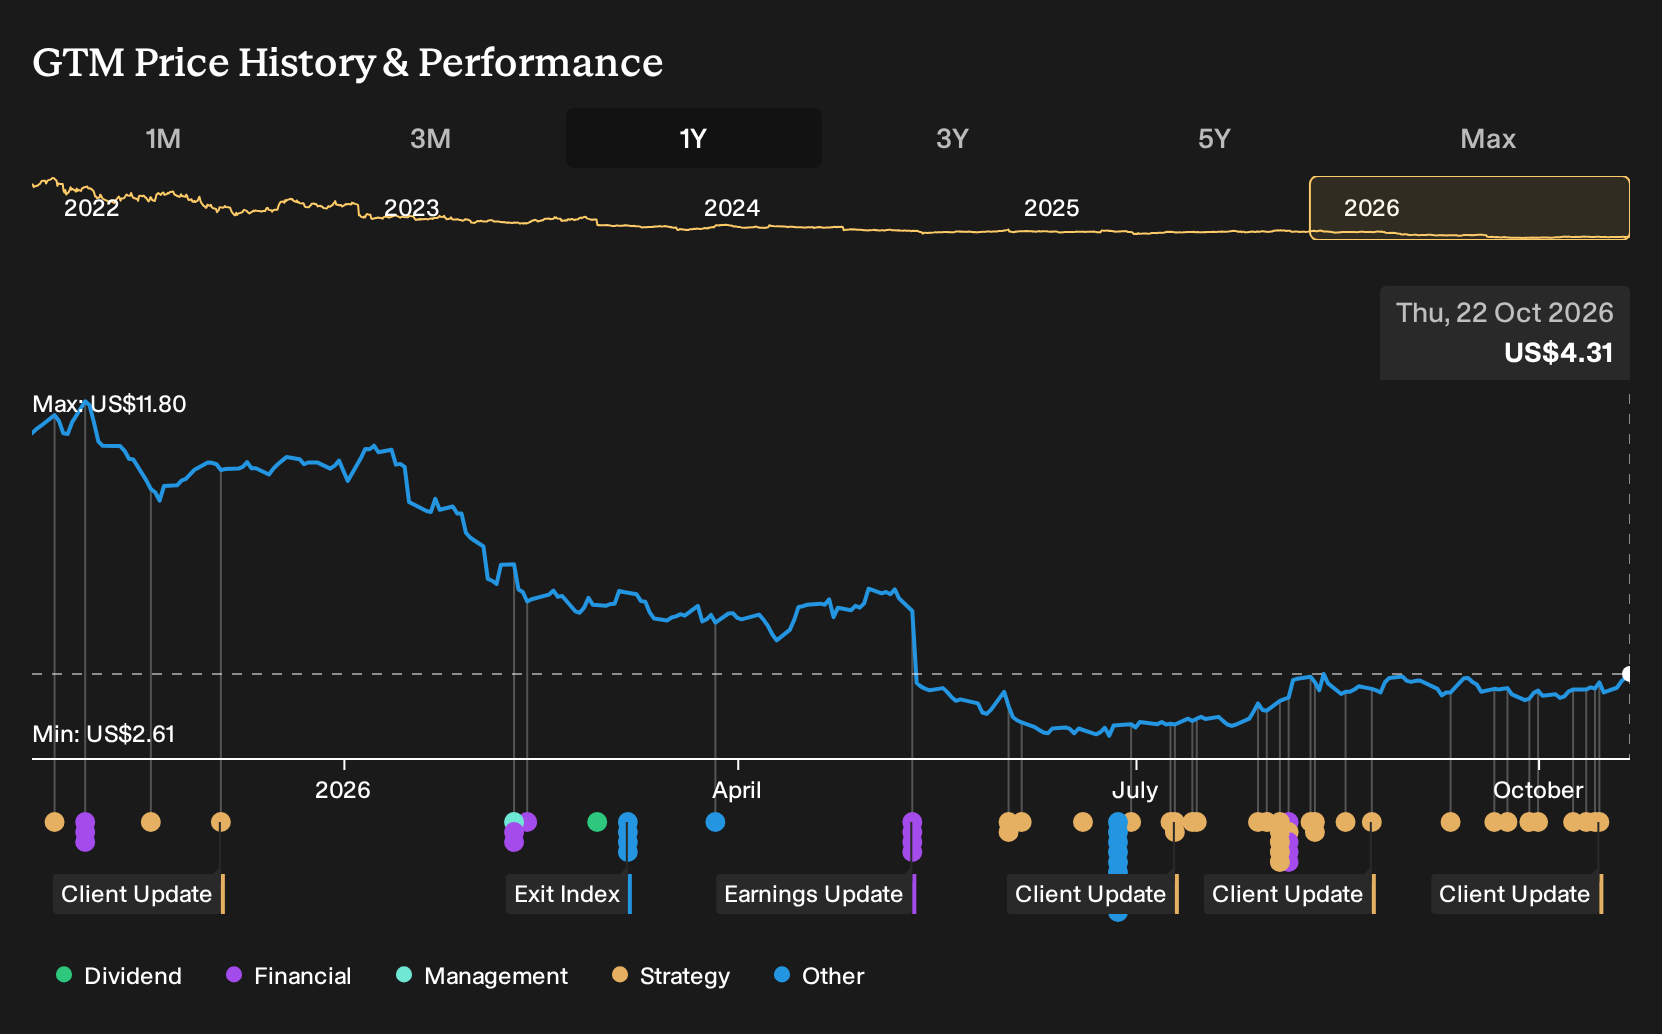
The key short term catalyst is whether deeper AI agent integrations translate into stable or improving revenue after the recent downtrend and ongoing unprofitability. The biggest risk remains customer concentration and downmarket softness, combined with commoditization pressure on AI data tools that could weigh on pricing and margins if differentiation blurs.
Among the recent announcements, Salesforce Hunter is the most relevant for the near term narrative. Hunter pipes ZoomInfo intelligence directly into a dominant CRM workflow, which tightens integration with large enterprises that already anchor the current upmarket focus. That kind of embedded access often matters more than adding another point tool on the side.
The operational question is whether Hunter usage converts into durable ZoomInfo data consumption rather than transient experimentation. Investors will likely track how often Hunter powered workflows pull on the GTM Context Graph, what that means for contract expansions, and whether any uplift offsets pressure from smaller customer churn and heavy AI investment spend.
ZoomInfo Technologies' narrative projects US$1.2b revenue and US$391.8 million earnings by 2029. This aligns with analyst expectations for revenue to decline by 1.3% per year and for earnings to rise by about US$932.8 million from a loss of US$541.0 million today.
Uncover why ZoomInfo Technologies' fair value indicates a 7% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame ZoomInfo Technologies very differently. They focus on GTM.AI and agent integrations as the real catalyst, with revenue modeled at about US$1.2b and earnings near US$366.1 million by 2029. Those figures were set before the Hunter news, so you may want to revisit both narratives and stress test your own view.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests as much as 187% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond ZoomInfo Technologies?
Once you have a view on ZoomInfo Technologies, it often helps to compare it with a few very different opportunities so you can calibrate risk, quality, and potential reward across your portfolio. The Simply Wall St Screener can surface ideas that fit those priorities in a structured way.
- If capital preservation matters most to you, focus on balance sheet strength and filter for companies from our list of solid balance sheet and fundamentals (26 results) that hold up well under financial stress.
- If your goal is finding quality at a reasonable price, scan through the 30 high quality undervalued stocks and see which businesses combine decent fundamentals with what our models flag as attractive pricing.
- If recurring cash returns appeal to you, anchor your watchlist around reliable payers through the 6 dividend fortresses that concentrate on high yield and payout resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com