


EN
Is Arcus Biosciences (RCUS) Too Expensive After New Trial Data?
Arcus Biosciences has seen sharp swings in its share price recently, and that volatility puts a simple question on the table for you as an investor. Is the current US$19.36 price tag supported by what the business is generating in sales today and what those sales could reasonably support over time?
- Over the past 5 years the stock has fallen 42.6%, which makes the relationship between Arcus Biosciences' current price and its revenue base especially important to understand.
- Fresh data from the ARC-20 program on kidney cancer and the decision to raise US$250m through a new share sale can influence how quickly Arcus Biosciences may be able to convert its pipeline into future revenue and how much dilution investors are taking on for that opportunity.
- The analysts covering Arcus Biosciences have run their own numbers. See what analysts think Arcus Biosciences's shares could be worth.
The issue now is whether the sales that Arcus Biosciences is generating, and is realistically positioned to generate, are enough to justify where the stock is trading today.
If you are weighing Arcus Biosciences against other opportunities built around revenue support for valuation, it can help to compare it with 30 high quality undervalued stocks.
Is Arcus Biosciences Getting Expensive on Sales?
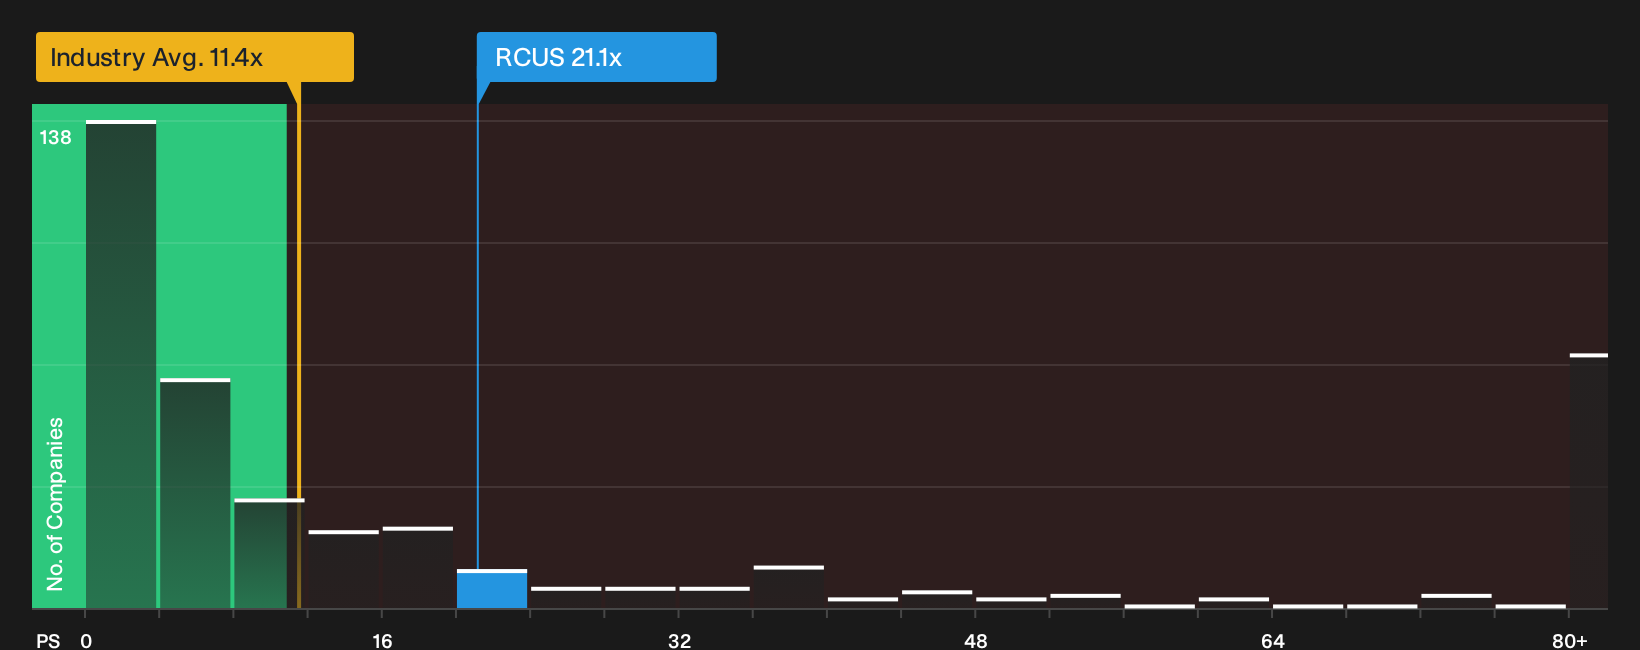
P/S works better than P/E for Arcus Biosciences, because the business is still loss making and investors are mostly anchoring on revenue and pipeline potential instead of current profits. On that measure, the stock trades on a P/S ratio of 21.1x, compared with about 11.4x for the wider biotechs sector and roughly 13.9x for its closer peer group. That is a clear premium to what investors are paying for similar revenue in comparable drug developers.
Fresh enthusiasm around the ARC-20 kidney cancer data has helped sentiment, yet the P/S multiple still screens as expensive relative to the tailored fair multiple implied by the valuation model, which heavily penalises the scale of current free cash flow losses and execution risk. The gap is so wide that the model output is better read as a warning flag about how much optimism is already embedded in the share price rather than a precise estimate of what Arcus Biosciences should trade on. Explore the numbers behind Arcus Biosciences's P/S valuation.
The Arcus Biosciences Narrative: What Would Justify Today's Price?
Narratives for Arcus Biosciences build on this valuation puzzle and outline which combinations of future growth, profitability and earnings power would need to occur for the stock to trade meaningfully higher or lower than it does today. All of this is presented on Simply Wall St's Community page. Each scenario connects its figures to a clear view on where revenue expansion, margin structure and key risks could go next, giving you concrete points to reassess as new information emerges.
One of the top community narratives on Arcus Biosciences: 54% undervalued
"Arcus Biosciences is prioritizing the launch of its late-stage development program for the HIF-2 alpha inhibitor, casdatifan, which has shown significant efficacy differentiation relative to existing market competitors..."
Discover why this Narrative puts Arcus Biosciences at 54% undervalued.
One more Arcus Biosciences check that sits beside the share price
Before you move on from Arcus Biosciences, it is worth asking who is steering the pipeline and how their rewards line up with your interests. See who runs Arcus Biosciences and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com