


EN
Is PPL (PPL) Fairly Priced After a 58% Three Year Gain?
PPL Corporation has delivered a solid 57.8% share price gain over the past three years, which puts fresh attention on what investors are paying for its earnings today. With the stock recently closing at US$35.35, the immediate question is whether that level lines up with what the utility's profit profile can reasonably support.
- A 57.8% return over three years means anyone looking at PPL now is stepping into a stock where past shareholders have already seen substantial value creation. As a result, the current P/E needs to work harder to make sense.
- For a regulated utility that relies on steady earnings and capital-intensive assets, the sustainability of profit margins and the predictability of cash generation can play a big role in how much investors are willing to pay for each dollar of income.
- The analysts covering PPL have run their own numbers. See what analysts think PPL's shares could be worth.
The issue now is whether PPL's current share price is justified by its earnings when judged against the Fair Ratio benchmark.
To see how PPL's earnings-based valuation compares with other utilities and income-focused opportunities, review it alongside the 6 dividend fortresses
Where Does PPL Sit on Earnings?
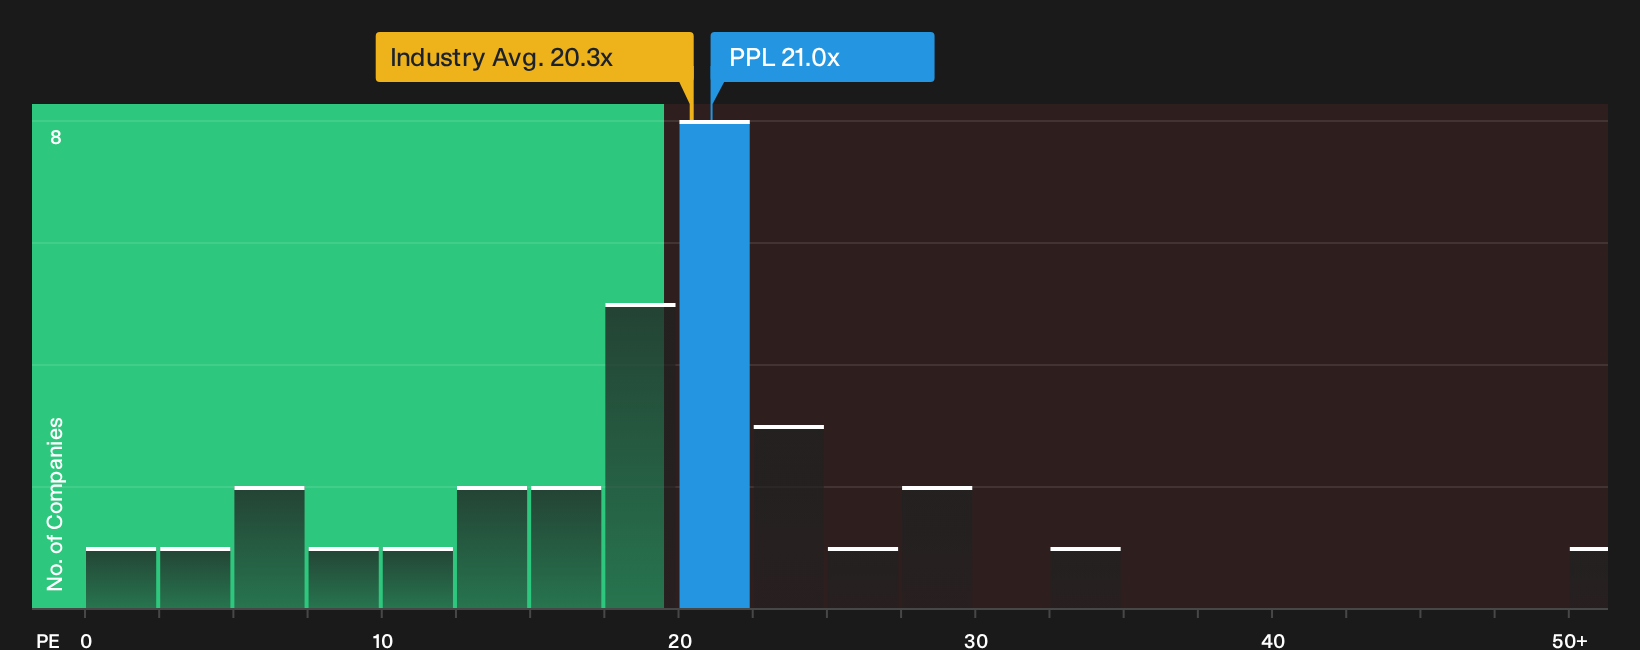
The P/E lens fits PPL because earnings account for much of the story for a regulated utility that depends on long term assets and set returns. On this measure, the stock trades at about 21.0x earnings, which is slightly above the Electric Utilities sector average near 20.3x and also a touch higher than the broader peer group near 19.3x.
Compared with the Fair Ratio benchmark, which reflects what investors might expect to pay for PPL given its sector, profitability profile, size and risk, the current multiple is very close to that reference point and suggests the valuation is roughly in line with earnings. For anyone considering the stock now, the key question is whether the quality and reliability of those profits justify paying approximately this P/E level compared with other income options. Explore the numbers behind PPL's P/E valuation.
The PPL Narrative: What Would Justify Today's Price?
Narratives for PPL bridge the gap between the current P/E puzzle and the assumptions under the surface by spelling out what would need to change in future growth, margins and earnings for the stock to look meaningfully cheaper or more expensive than it does today. Each narrative links its implied number to a clear view on how PPL's financial profile and risk picture could evolve, which you can revisit on the Community page as new information arrives.
One of the top community narratives on PPL: 12% undervalued
"The current valuation implies the market is discounting PPL's load and capex pipeline and is not fully pricing in the earnings contribution…"
Discover why this Narrative puts PPL at 12% undervalued.
Before acting on PPL's valuation, there is one more angle to check
Price and earnings only tell part of the story for PPL Corporation, since separate research checks have also flagged specific concerns that could influence how you weigh the balance of risk and reward. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com