
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Telia (OM:TELIA) Q3 Results Sharpen The Case For Stronger Cash Flow
Telia Company came into today’s Q3 2026 report with its stock at SEK48.26, carrying a reputation as a slow but steady Nordic telecom utility with a rich dividend and a stretched P/E. The headline print was simple and punchy. Quarterly net income reached SEK2,704m on SEK21,306m in revenue, with basic earnings per share at SEK0.69.
The market reaction now has to grapple with a different story. Profitability looked firmer than the defensive narrative around Telia suggests, which puts fresh pressure on a share price that has lagged the firm’s stated cash generation ambitions.
Drawn to Telia Company for the steady dividend profile but uneasy about paying up for a stretched P/E on a stock that has not kept pace with its own cash ambitions? Check out the 192 high quality undervalued stocks as a reference list of businesses that pair richer cash generation with valuations that look less demanding.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): SEK21,306m vs. SEK19,861m (up about 7.3%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): SEK2,704m vs. SEK2,322m (up about 16.5%)
- Basic EPS (Q3 2026 vs. Q3 2025): SEK0.69 vs. SEK0.59 (up about 16.4%)
- Trailing 12-month Net Income, excl. extra items (Q3 2026 vs. Q3 2025): SEK5,289m vs. SEK5,808m (down about 8.9%)
Prefer clean charts instead of another dense wall of Telia Company figures and footnotes? Get a full visual read on its valuation in an easy dashboard via the company report for Telia Company..
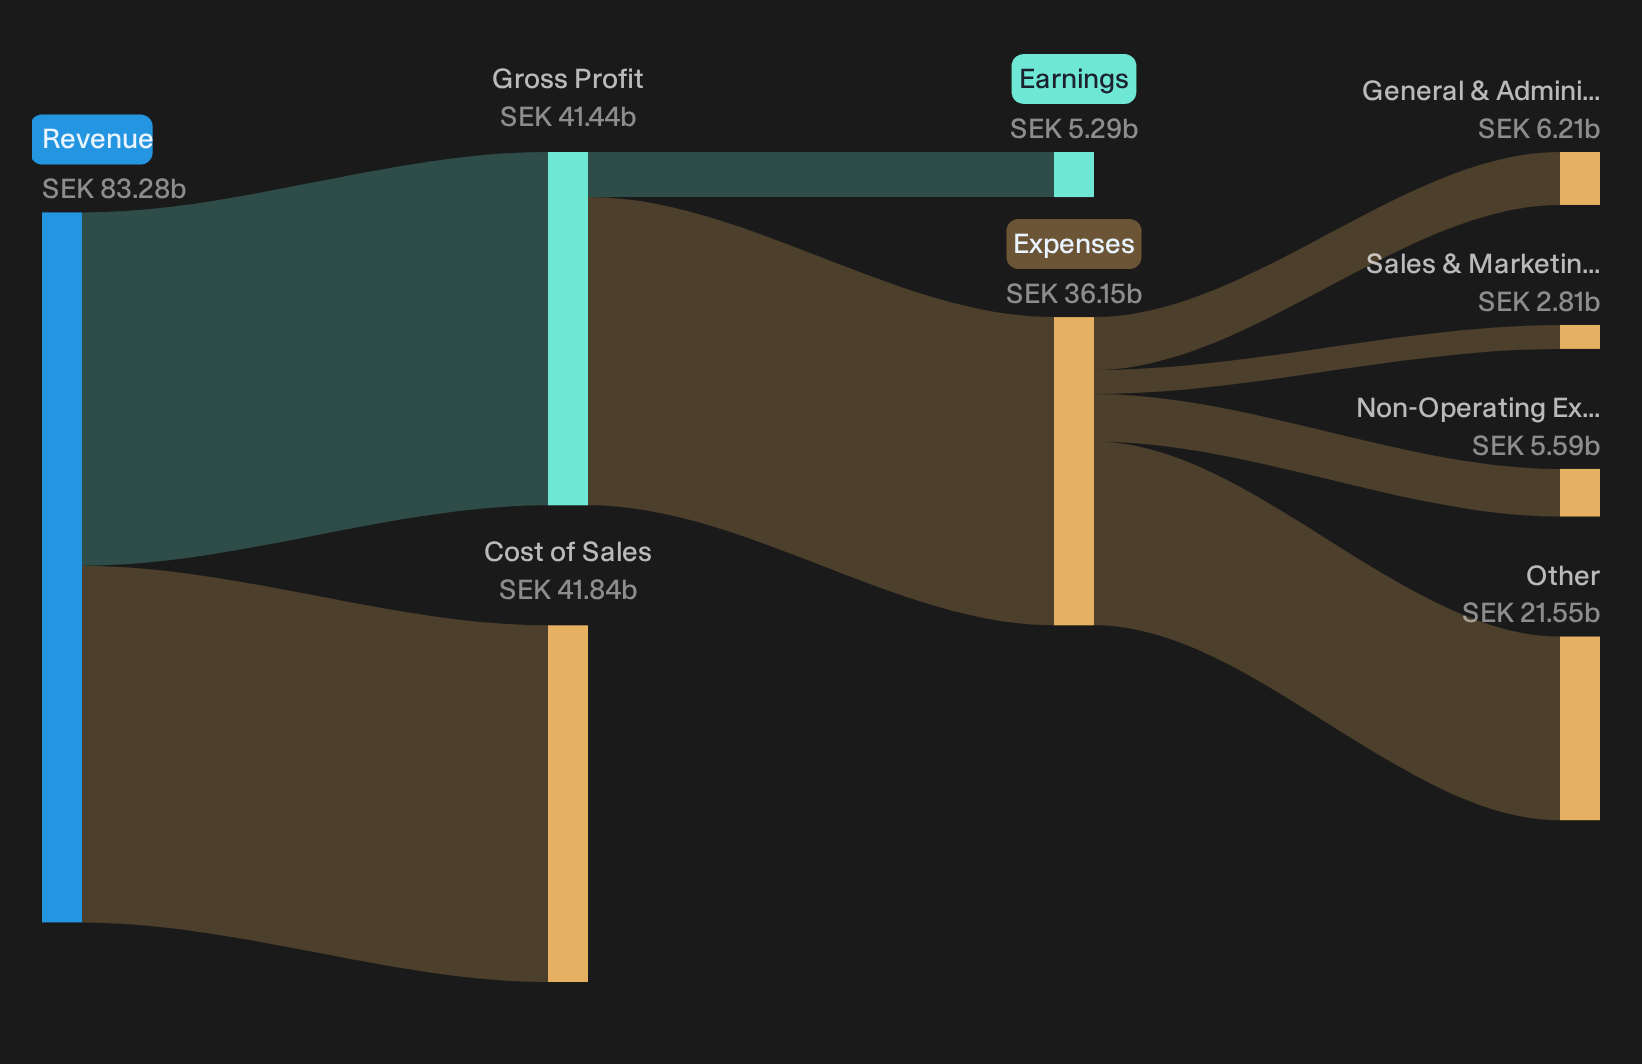
Telia margins: pruning story starting to show
Bullish investors have argued that Telia Company can turn portfolio clean up and tighter expenses into structurally higher earnings and cash.
"Management has already exited or is exiting several non core activities including TV and Media, web hosting, alarm services and parts of Finnish ICT. This ongoing refocus on core connectivity and infrastructure can still widen Telia Company group net margins and earnings quality, as lower contribution from low margin revenue frees up capital for higher return uses."
Q3 gives that claim some footing. Service revenue growth of 3.3% with EBITDA up 2.9% and year to date EBITDA up 3.5%, while CapEx holds at SEK12.6b, shows earnings quality improving rather than just being recycled into heavier investment. Free cash flow of SEK3.7b for Q3 and SEK7.8b for 9M sits close to the upgraded full year at least SEK9b ambition, which indicates the pruning and cost work are already flowing into cash.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Telia revenue mix fears meet early reality check
The more cautious view argues that Telia Company might be swapping quality for volume in Swedish broadband, with long term damage to pricing power and profitability.
"Although Telia Company is growing the base of Swedish converged households and lifting revenue per household, the sharp 9% fall in Swedish broadband ARPU in Q2 2026 tied to lower priced Bredband2 customers and a focus on volume over pricing risks embedding a structurally weaker revenue mix that limits future top line and margin progression."
Q3 service revenue growth of 4.7% in Sweden and roughly 4% on an underlying basis shows that volume has not yet dragged group margins. EBITDA growth did temporarily slow in Sweden, so this concern is not cleared. It is simply not confirmed by this quarter either.
Hunt For Quietly Mispriced Cash
Telia Company just reported a tidy quarter that still leaves investors debating the story. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 1 - 24% below our estimate - builds an integrated cloud and productivity stack enterprises adopt as AI workloads scale beyond on premises tools.
- Company 2 - 32% below our estimate - shifts production toward higher margin specialty molecules serving human nutrition and defense projects funded for capacity expansion.
- Company 3 - 40% below our estimate - expands protective film manufacturing so automakers and installers secure supply for higher margin window and paint protection products.
Three companies from the same screener. Open every one of the 192 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com