
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Atea (OB:ATEA) Stock Looks Cheap After Strong Q3 Earnings
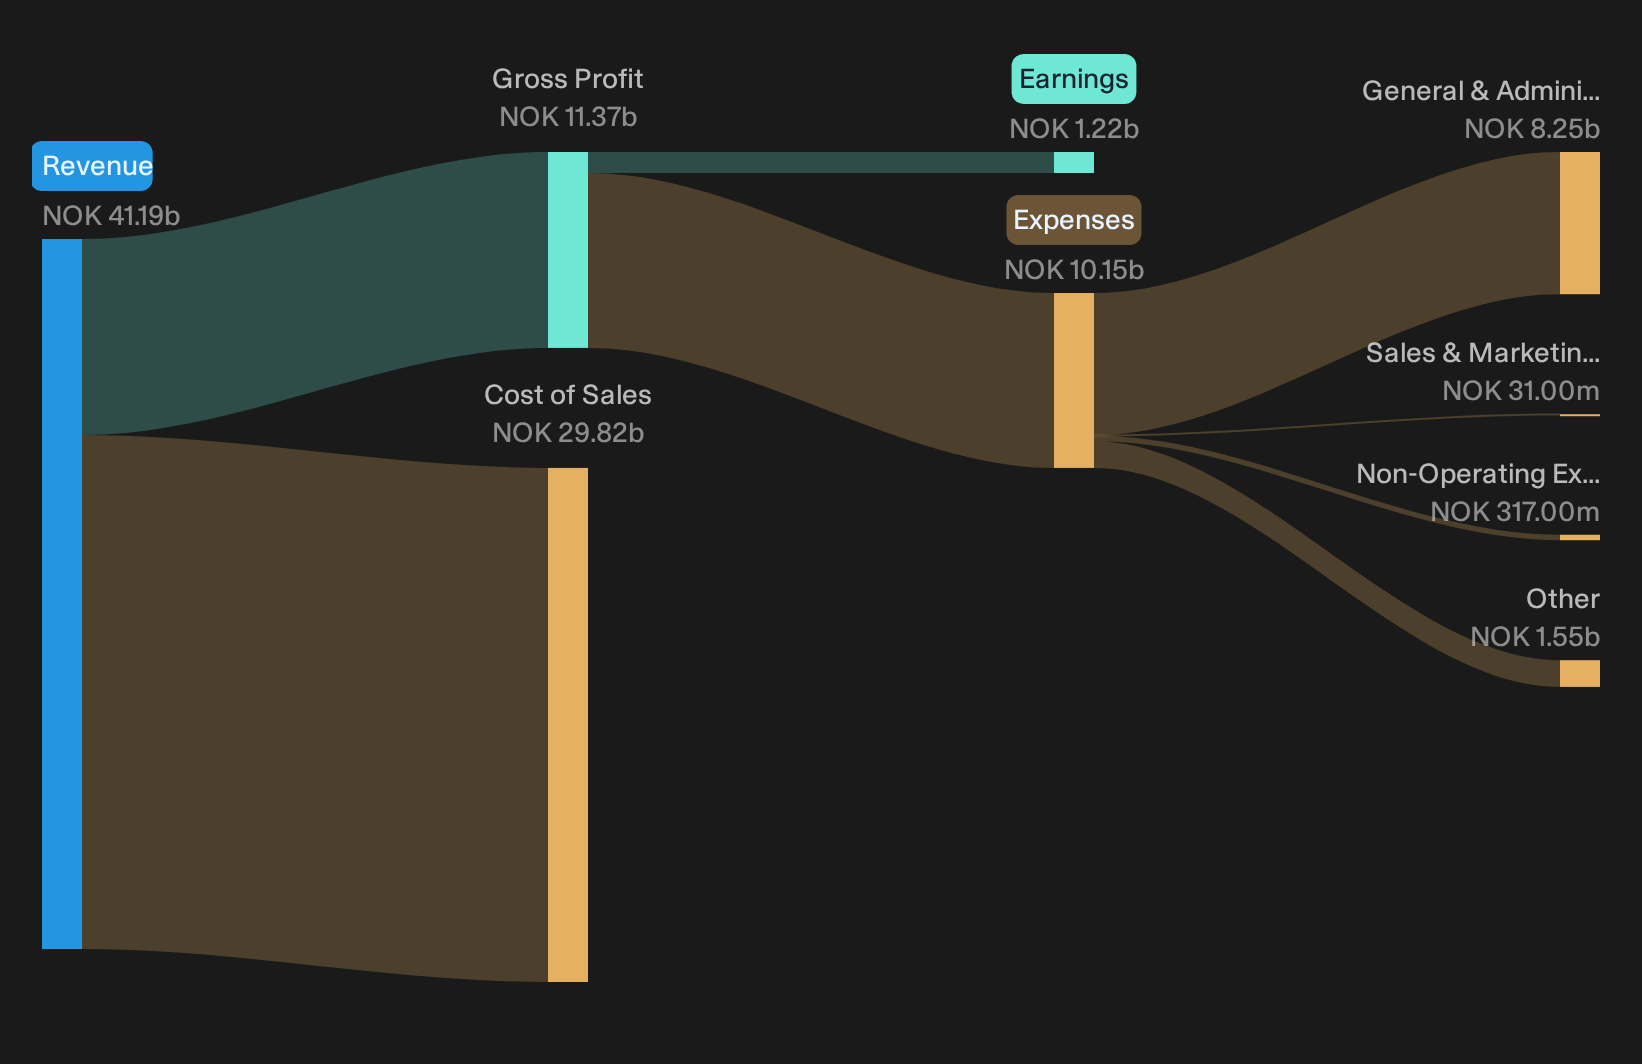
Atea walked into its Q3 2026 report with the stock at NOK165, roughly flat over the past quarter, and investor expectations quietly reset after a choppy year. The headline was clear. Net income reached NOK279m on IFRS revenue of NOK9.9b, while EBIT came in at NOK405m, all built on strong demand for data center hardware.
The twist is in the mood, not the math. One quarter of robust earnings power sits against a share price that screens materially below a discounted cash flow estimate of fair value, which leaves today’s reaction looking driven more by emotion than the full set of fundamentals.
Love Atea’s solid Q3 earnings print but wondering if the discount to estimated fair value is really justified? Compare it with our 193 high quality undervalued stocks to see how other quality businesses with strong fundamentals are pricing in similar conditions.
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): NOK 9,860m vs. NOK 8,433m (up roughly 16.9%)
- Net Income, Excl. Extra Items (Q3 2026 vs Q3 2025): NOK 279m vs. NOK 226m (up about 23.4%)
- Basic EPS (Q3 2026 vs Q3 2025): NOK 2.50 vs. NOK 2.03 (higher by around 23.2%)
- EBIT (Q3 2026 vs Q3 2025): NOK 405m vs. NOK 348m (up roughly 16.5%)
Ask Charlie what Atea really expects from AI demand into 2027.
Atea’s Q3 Shows Services Mix Slowly Catching Up
The bullish view hinges on Atea nudging more work into higher value recurring offerings while holding the cost base in check.
"The main thing that has to go right is that Atea continues to shift more customers toward higher value managed services and cybersecurity while keeping costs growing slower than gross sales."
Q3 results partly deliver on that script. Services revenue dipped 1.9% reported but grew about 6% in constant currency, so higher value work is at least keeping pace with hardware. Operating expenses were flat at around NOK 2.2b while gross sales grew strongly, which supports the cost discipline side of the narrative.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Atea Bear Case: Hardware Heaviness And Cash Still On Trial
Bears argue Atea’s reliance on hardware and working capital makes earnings fragile if demand or vendor terms shift.
"Despite Atea pointing to a strong balance sheet, the Q2 2026 operating cash outflow of NOK 727 million driven by inventory build shows that securing hardware availability ties up significant capital."
Q3 takes some sting out of that. Inventories fell by more than NOK 400m and operating cash returned to a NOK 143m inflow, which shows management is unwinding earlier stock build. The concern is not fully cleared though. Hardware still grew much faster than services, and gross margin eased as the mix tilted to lower margin categories.
Hunt For Mispriced Earnings Power
Atea reports a solid quarter while its share price remains subdued. The real opportunity is spotting stocks that could be undervalued before that gap narrows.
- Company 1 - 18% below our estimate - focuses on secured retail lending and raises business handled per employee as headcount declines.
- Company 2 - 40% below our estimate - builds protective films and services while directing new capital into scaled manufacturing and supply chain expansion.
- Company 3 - 24% below our estimate - runs a three-part engine tying productivity software, cloud infrastructure and metered AI usage into one integrated platform.
Three companies from the same screener. Open the full list of 193 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com