
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Randstad (ENXTAM:RAND) Q3 Results Sharpen Focus On Margin Rebuild
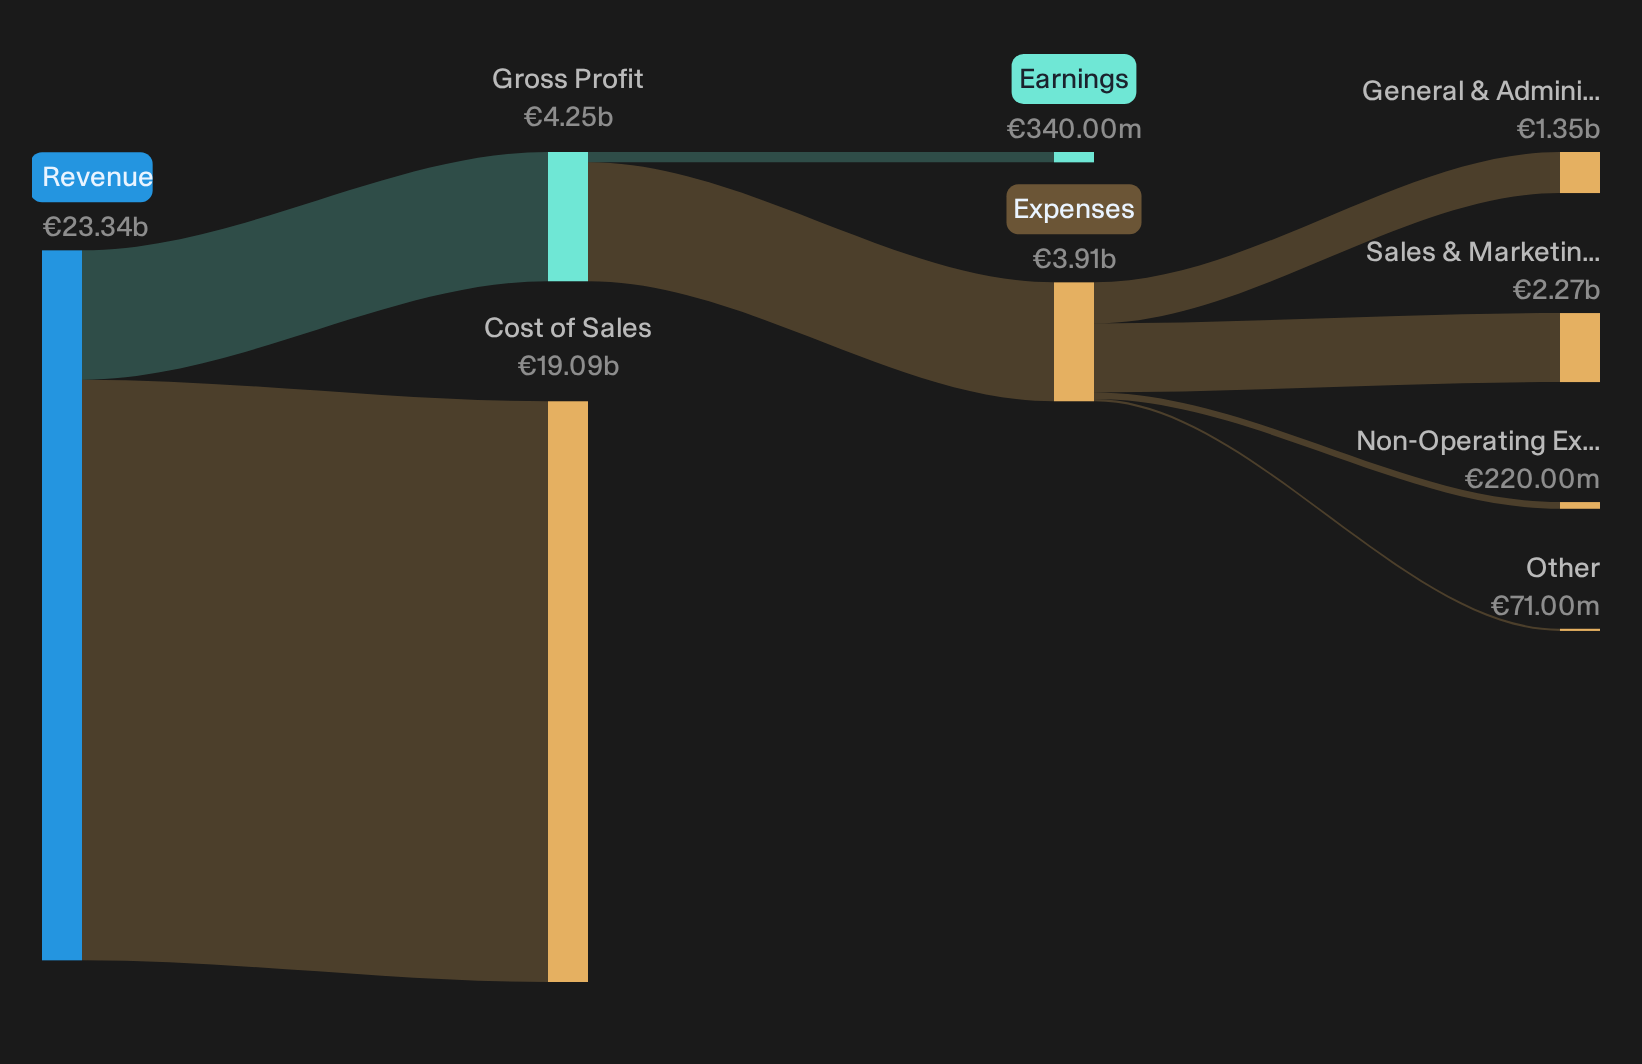
Randstad stock closed at €40.65 on Thursday after a steady run over the past three months, yet the real story sits in the fresh Q3 2026 earnings print. The staffing giant booked €6.1b in revenue and €108m in net income, with basic earnings per share at €0.62. This highlights a margin rebuild rather than a one quarter blip. Short term traders are reacting to the ticker. Long term holders are likely focusing on a very different question: whether this earnings momentum can reshape a business that has spent years wrestling with weaker profit trends.
Like the earnings reset at Randstad but unsure this margin rebuild story will stick across a full cycle? Screen for other recruiters and people focused companies with sturdier profitability profiles through the list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €6,115m vs. €5,810m (+5.3%)
- Net Income (Q3 2026 vs. Q3 2025): €108m vs. €81m (+33.3%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.62 vs. €0.46 (+33.1%)
- Net Profit Margin (Trailing 12 Months vs. Prior 12 Months): 1.5% vs. 0.2% (margin improved strongly)
Earnings tell you what Randstad booked this quarter, but investors who care about what the stock is worth usually focus on the cash moving through the business over time. When those cash flows are placed at the center of the story, Randstad starts to look very different, because on cash flows alone the stock could be a hefty 47% undervalued.
Randstad’s Bull Case Meets Early Execution Milestones
Bulls argue Randstad’s upside depends on turning digital scale and large contracts into better efficiency, not just chasing volume.
"The main requirement is that Randstad continues to convert its large-deal pipeline and digital marketplace adoption into profitable revenue while managing the margin trade off from a heavier large-client and Southern European mix."
Q3 shows real progress toward that goal. Revenue grew 3.9% while EBITA rose 10%, lifting the EBITA margin to 3.5%. Operating expenses declined year on year and underlying free cash flow reached €250m. North America illustrates the thesis best, with 19% operational growth and a 5.3% EBITA margin supported by marketplace and AI driven productivity gains.
The price and this Narrative do not agree. → Uncover what this Narrative says Randstad is actually worth.
Randstad Results Test Margin And Cashflow Fears
Bearish investors worry that Randstad’s own digital push could compress fees and blunt earnings power even when revenue looks healthy.
"The main thing that has to go right is that Randstad converts the early traction in AI enabled delivery, large account wins and marketplace volume into sustained productivity gains that more than offset ongoing gross margin pressure from mix and weak permanent recruitment."
Q3 offers mixed evidence. EBITA grew faster than revenue and the group booked €250m of underlying free cash flow, which challenges the pure margin compression story. Yet gross profit rose only 1% against 3.9% revenue growth and management still flags mix and regulatory headwinds, so the pressure point has not disappeared.
Hunt Quiet Dislocations In Plain Sight
Randstad reminds investors that a solid quarterly result can still prompt debate about long term earnings power. The real opportunity is finding stocks that could be undervalued before any gap between expectations and price potentially narrows.
- Company 1 - 19% below our estimate - uses dark stores and bundled subscriptions to move repeat food and grocery orders into a single app.
- Company 2 - 25% below our estimate - redirects fabrication lines toward higher value AI server memory under multi year supply agreements with long duration customers.
- Company 3 - 38% below our estimate - expands fee based services such as wealth, insurance and payments while central programs drive cost cuts and risk weighted asset releases.
That is three of the list. See all 193 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com