
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Can Kingfisher (LSE:KGF) Look Undervalued As Its New CEO Sharpens Digital Focus?
Kingfisher (LSE:KGF) has become a talking point after confirming that Sebastian Gundel will take over as chief executive in February 2027. This leadership shift is closely tied to the group’s digital and customer focus.
Investors have already reacted to the leadership news, with the 90 day share price return of 15.63% and a year to date share price gain of 9.45% pointing to building momentum around Kingfisher. The 3 year total shareholder return of 93.60% highlights the effect of compounding for long term holders.
Scan how other retailers with digital and customer focused stories are setting up for their next move by checking our hand picked 5 high quality undiscovered gems alongside Kingfisher.
After a 90 day gain of 15.63% and a 3 year total return near 94%, the obvious question for Kingfisher now is whether the real upside still lies ahead or if most of it already sits in the rear view mirror as valuation comes into focus.
Most Popular Narrative: 4% Overvalued
Against a last close of £3.46, the most followed valuation narrative for Kingfisher points to a fair value of about £3.32, so the current quote sits slightly above that central estimate while still within the range of analyst expectations.
The analysts have a consensus price target of £3.31 for Kingfisher based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of £3.31, the analyst price target of £3.31 is 0.2% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
See why 18 investors see Kingfisher as 4% overvalued.
Result: Fair Value of £3.32 (OVERVALUED)
Still, weak consumer sentiment in France and Poland, along with ongoing restructuring costs in certain regions, could quickly challenge the current Kingfisher valuation story.
Find out about the key risks to this Kingfisher narrative.
Another View: Kingfisher Through a Cash Flow Lens
The P/E based narrative suggests Kingfisher looks 4% overvalued around £3.46. Yet the SWS DCF model points the other way, with a future cash flow value estimate of about £4.10, implying the shares trade roughly 15.5% below that level. Which story do you think is closer to reality?
Look into how the SWS DCF model arrives at its fair value.
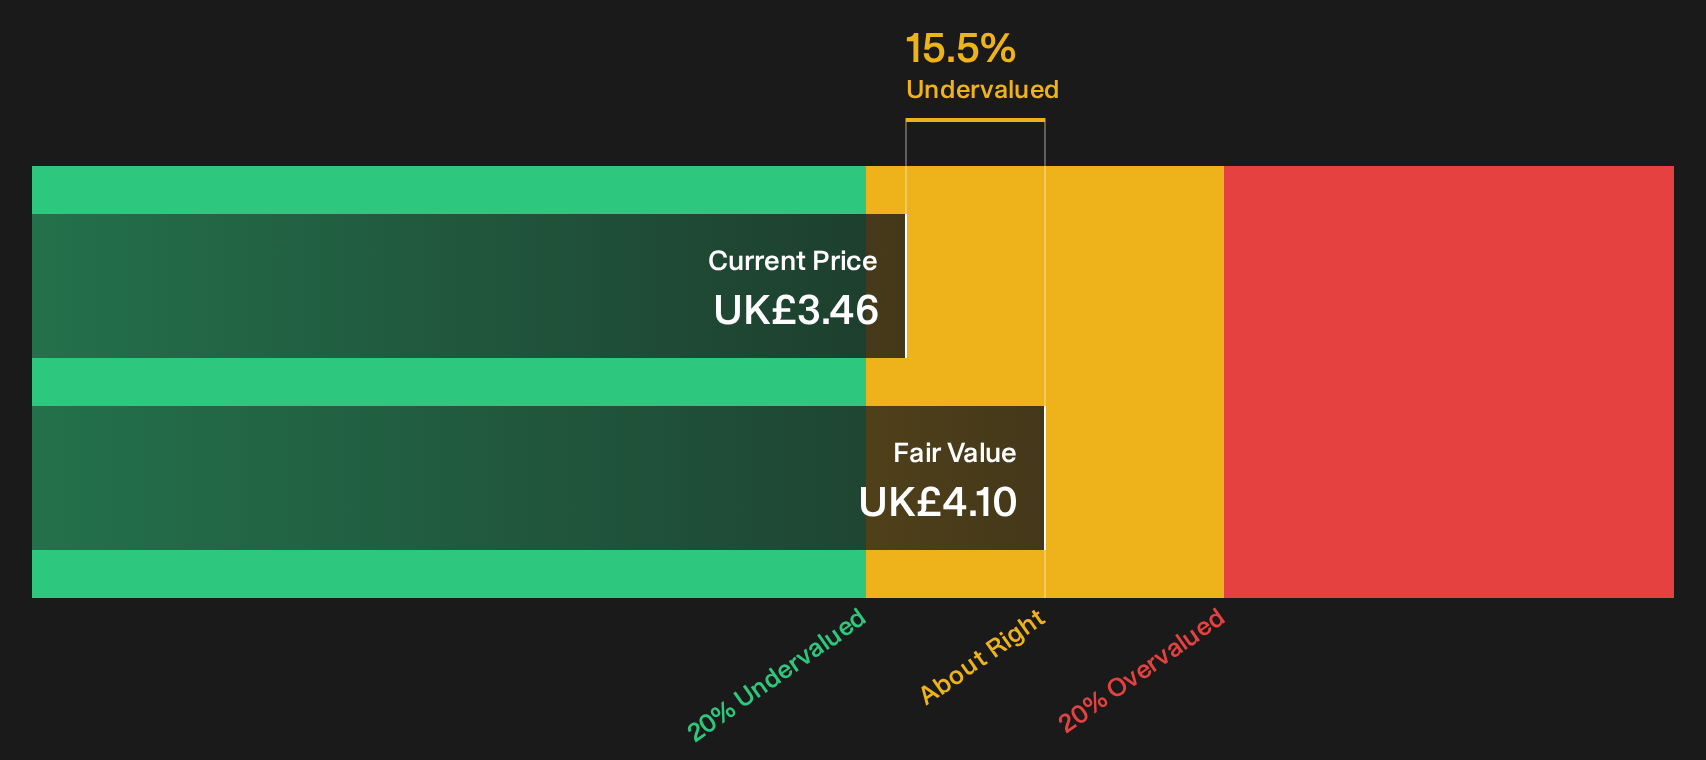
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kingfisher for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Market sentiment remains mixed following the extensive debate around Kingfisher. If you want to make a prompt decision on your position, consider reviewing the 3 key rewards and 2 important warning signs to assess the balance of potential risks and rewards.
Looking for more ideas beyond Kingfisher?
If Kingfisher has sharpened your focus on opportunities, do not stop here. The real edge often comes from comparing several high quality ideas side by side.
- Target resilient performers by scanning a 4 resilient stocks with low risk scores that may help reduce portfolio swings when markets turn choppy.
- Hunt for quality at a discount and use the 7 high quality undervalued stocks to spot businesses where fundamentals and pricing might be out of sync.
- Strengthen your income stream by reviewing a 4 dividend fortresses that focuses on higher yielding payouts with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com