
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Companies Like CSC Holdings (HKG:235) Are In A Position To Invest In Growth
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
Given this risk, we thought we'd take a look at whether CSC Holdings (HKG:235) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
How Long Is CSC Holdings' Cash Runway?
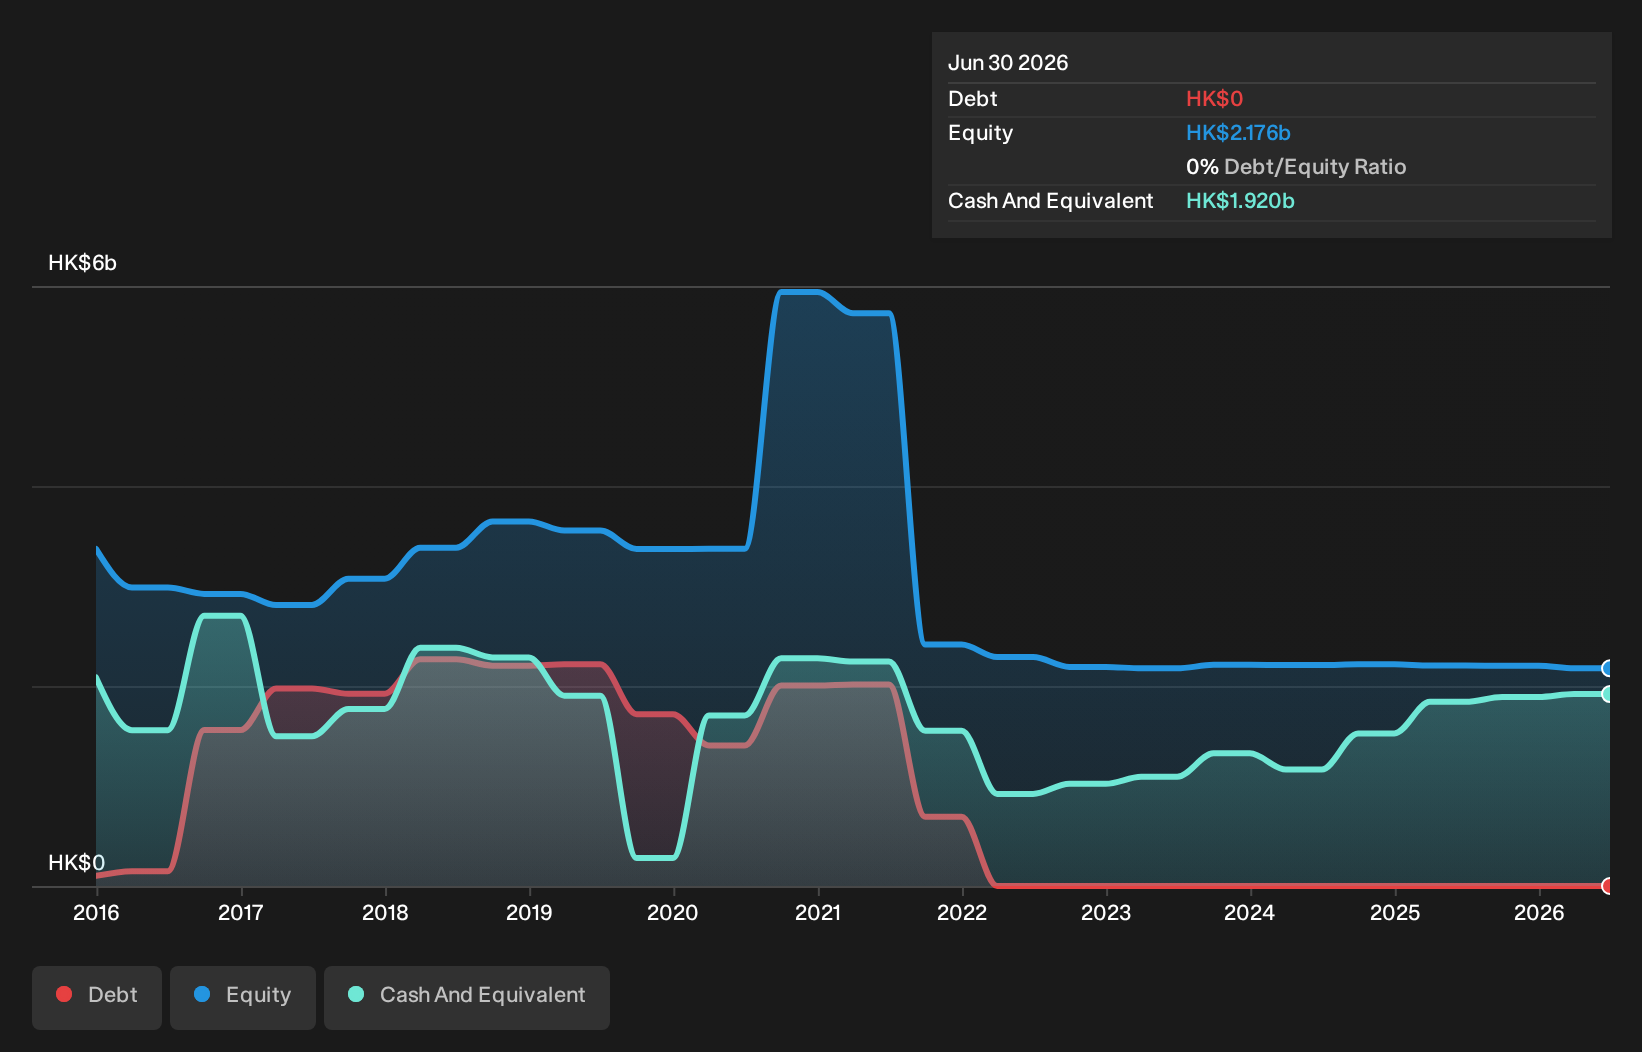
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, CSC Holdings had HK$1.9b in cash, and was debt-free. Looking at the last year, the company burnt through HK$53m. So it had a very long cash runway of many years from June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for CSC Holdings
Can CSC Holdings Raise More Cash Easily?
Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Commonly, a business will sell new shares in itself to raise cash and drive growth. We can compare a company's cash burn to its market capitalisation to get a sense for how many new shares a company would have to issue to fund one year's operations.
Since it has a market capitalisation of HK$367m, CSC Holdings' HK$53m in cash burn equates to about 14% of its market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
How Risky Is CSC Holdings' Cash Burn Situation?
Given it's an early stage company, we don't have a lot of data with which to judge CSC Holdings' cash burn. However, it is fair to say that its cash runway gave us comfort. Overall, we don't think shareholders need to be worried about its cash burn in the near term. Taking an in-depth view of risks, we've identified 2 warning signs for CSC Holdings that you should be aware of before investing.
Of course CSC Holdings may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.