
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Rengo (TSE:3941)'s Cash Flow Recovery Means For Shareholders
- Rengo has attracted attention after analysts projected a shift into positive free cash flow in coming years, raising questions about whether its current valuation reflects the company’s expected cash generation.
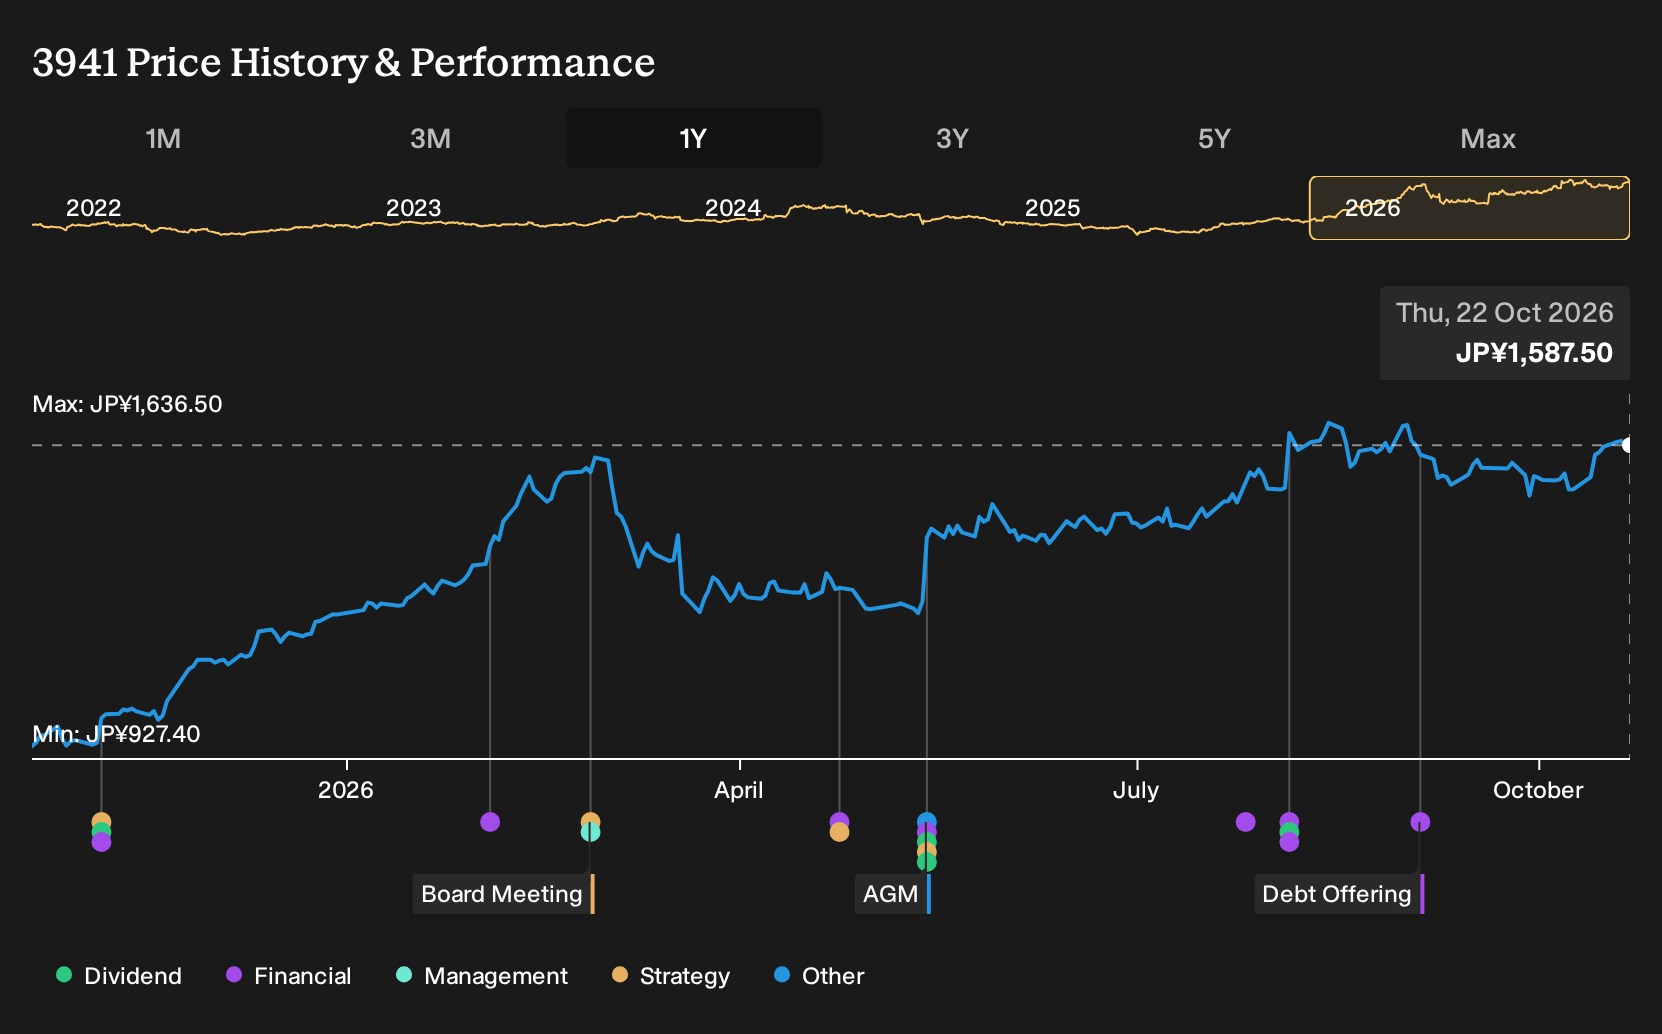
- An interesting angle is that Rengo’s recent operational track record already includes strong share price gains, yet some models still suggest its future cash flows are not fully reflected in today’s market value.
- We will now look at how Rengo’s investment narrative could be influenced by expectations of a recovery in its cash generation profile.
Compare Rengo’s cash flow recovery story with other potential opportunities by scanning our curated list of 14 high quality undervalued stocks that may not yet be fully priced by the market.
What Is Rengo's Investment Narrative?
For Rengo, the big-picture belief is simple. You have to think a 100 year old packaging group can keep turning solid operational execution into steady cash generation. The recent focus on a shift into positive free cash flow ties directly into that story. It matters because this is a capital intensive producer of paperboard, corrugated packaging, and machinery, where cash discipline and pricing power against input costs are just as important as reported earnings.
In the short term, the key swing factors are how consistently Rengo converts its earnings, which grew 26.7% over the past year, into cash while servicing debt that is not well covered by operating cash flow. The new free cash flow narrative may ease some concern around dividend cover, currently flagged as weak based on cash generation, but it also raises the bar on execution. Analysts pointing to undervaluation help the story, yet the real test is whether management can sustain margins, support ongoing investment, and avoid stretching the balance sheet.
Even so, there is a quieter piece of the Rengo puzzle that could unsettle that confidence if it moves the wrong way.
There's only one way to know the right time to buy, sell or hold Rengo. Head to Simply Wall St's company report for the latest analysis of Rengo's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rengo research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rengo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rengo's overall financial health at a glance.
Looking For More Ideas Beyond Rengo?
If Rengo has you thinking about where free cash flow stories and valuation gaps might line up, it can help to compare it with a few different types of opportunities. The Simply Wall St Screener lets you filter for the traits you care about so you can build a watchlist that matches your preferences.
- If you want resilient businesses where financial risk is kept in check, focus on stocks with steadier profiles through the 21 resilient stocks with low risk scores.
- For investors who care about balance sheet strength as much as earnings, use the screener to surface companies with healthier finances through the list of solid balance sheet and fundamentals (22 results).
- When you want to cast the net wider and look for lesser known opportunities with strong fundamentals, scan the market using the 73 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com