
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Comforia Residential REIT (TSE:3282) Could Be 7% Undervalued On Its New Loan
Why Comforia Residential REIT’s New Loan Matters For Unitholders
Comforia Residential REIT (TSE:3282) has arranged a new JPY 1,500 million long term loan with The Fukui Bank Ltd., with an interest rate set at JBA 1 month yen TIBOR plus 0.250%.
The funds, scheduled to be drawn on October 30, 2026, are designated for the early repayment of an existing borrowing. This extends Comforia Residential REIT’s debt maturity profile to October 30, 2033.
Comforia Residential REIT’s latest loan move comes at a time when momentum in the units has been fading. The share price is down 8.01% over the past 30 days and 20.48% year to date, and the 1-year total shareholder return has declined 16.39%.
Compare Comforia Residential REIT’s refinancing move with peers by scanning hand-picked real estate trusts and property owners that prioritize balance-sheet strength using the list of solid balance sheet and fundamentals (22 results).
After a long slide in Comforia Residential REIT’s unit price and a fresh move to push its debt out to 2033, the debate shifts. Is most of the recovery already reflected in the price, or is meaningful upside still on the table?
Price-to-Earnings of 21.1x: Is It Justified For Comforia Residential REIT?
On valuation, Comforia Residential REIT trades on a P/E of 21.1x, which screens as expensive against both its peer group on 17.5x and the wider Global Residential REITs industry on 18.7x.
The P/E ratio tells you how much investors are paying today for each unit of current earnings. For a residential landlord that targets steady income from a portfolio of 175 properties, a richer multiple usually implies the market is putting a premium on earnings quality, perceived resilience or the reliability of future distributions.
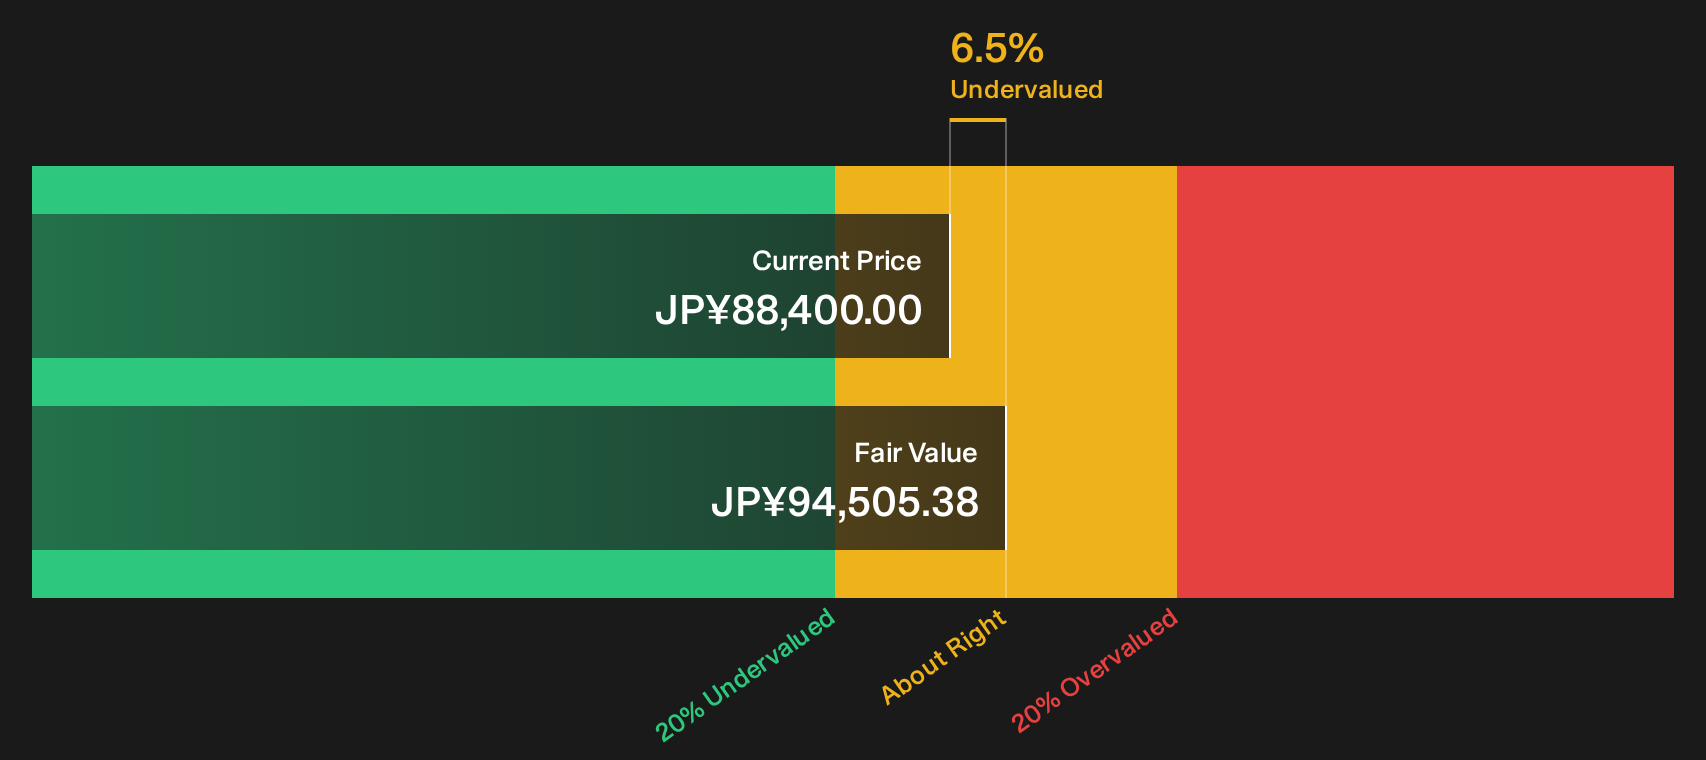
Comforia Residential REIT does offer some support for a higher earnings tag, including 9.5% earnings growth over the past year, high quality earnings and a high yet reliable 4.84% dividend yield. The trust is also trading at a 6.5% discount to the fair value estimated by the SWS DCF model, which puts the cash flow based fair value at ¥94,505.38 versus a last close of ¥88,400. The income stream and cash flows therefore point to modest undervaluation even as the headline P/E ratio runs ahead of peers.
Compared with the Global Residential REITs industry average P/E of 18.7x, Comforia Residential REIT’s 21.1x multiple is meaningfully higher, and it also sits well above the 17.5x peer average. The market is clearly paying up relative to similar trusts, which leaves less room for error if earnings momentum or dividend support weakens.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 21.1x (OVERVALUED)
Still, Comforia Residential REIT’s premium P/E and the recent double digit decline in unit returns leave little cushion if earnings quality or distributions disappoint.
Find out about the key risks to this Comforia Residential REIT narrative.
Another View: What The DCF Says About Comforia Residential REIT
The SWS DCF model points a different way for Comforia Residential REIT. On this approach, the units trade at roughly a 6.5% discount to an estimated fair value of ¥94,505.38, compared with the current price of ¥88,400. A higher P/E, but a discount on cash flows. Which signal carries more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Comforia Residential REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Comforia Residential REIT’s valuation and risk reward profile can feel messy, so move quickly, review the key metrics, and then anchor your own stance on its 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Comforia Residential REIT?
If Comforia Residential REIT has sharpened your focus on valuation and income, do not stop here. Broaden your watchlist quickly before the next move passes you by.
- Target resilience first and filter for companies with healthier balance sheets using the list of solid balance sheet and fundamentals (22 results).
- Hunt for mispriced opportunities and scan a carefully curated pool of potential value candidates with the 14 high quality undervalued stocks.
- Build a stronger income stream and spot companies with robust payouts through the 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com