
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What International Paper Bears Saw Before The Fall
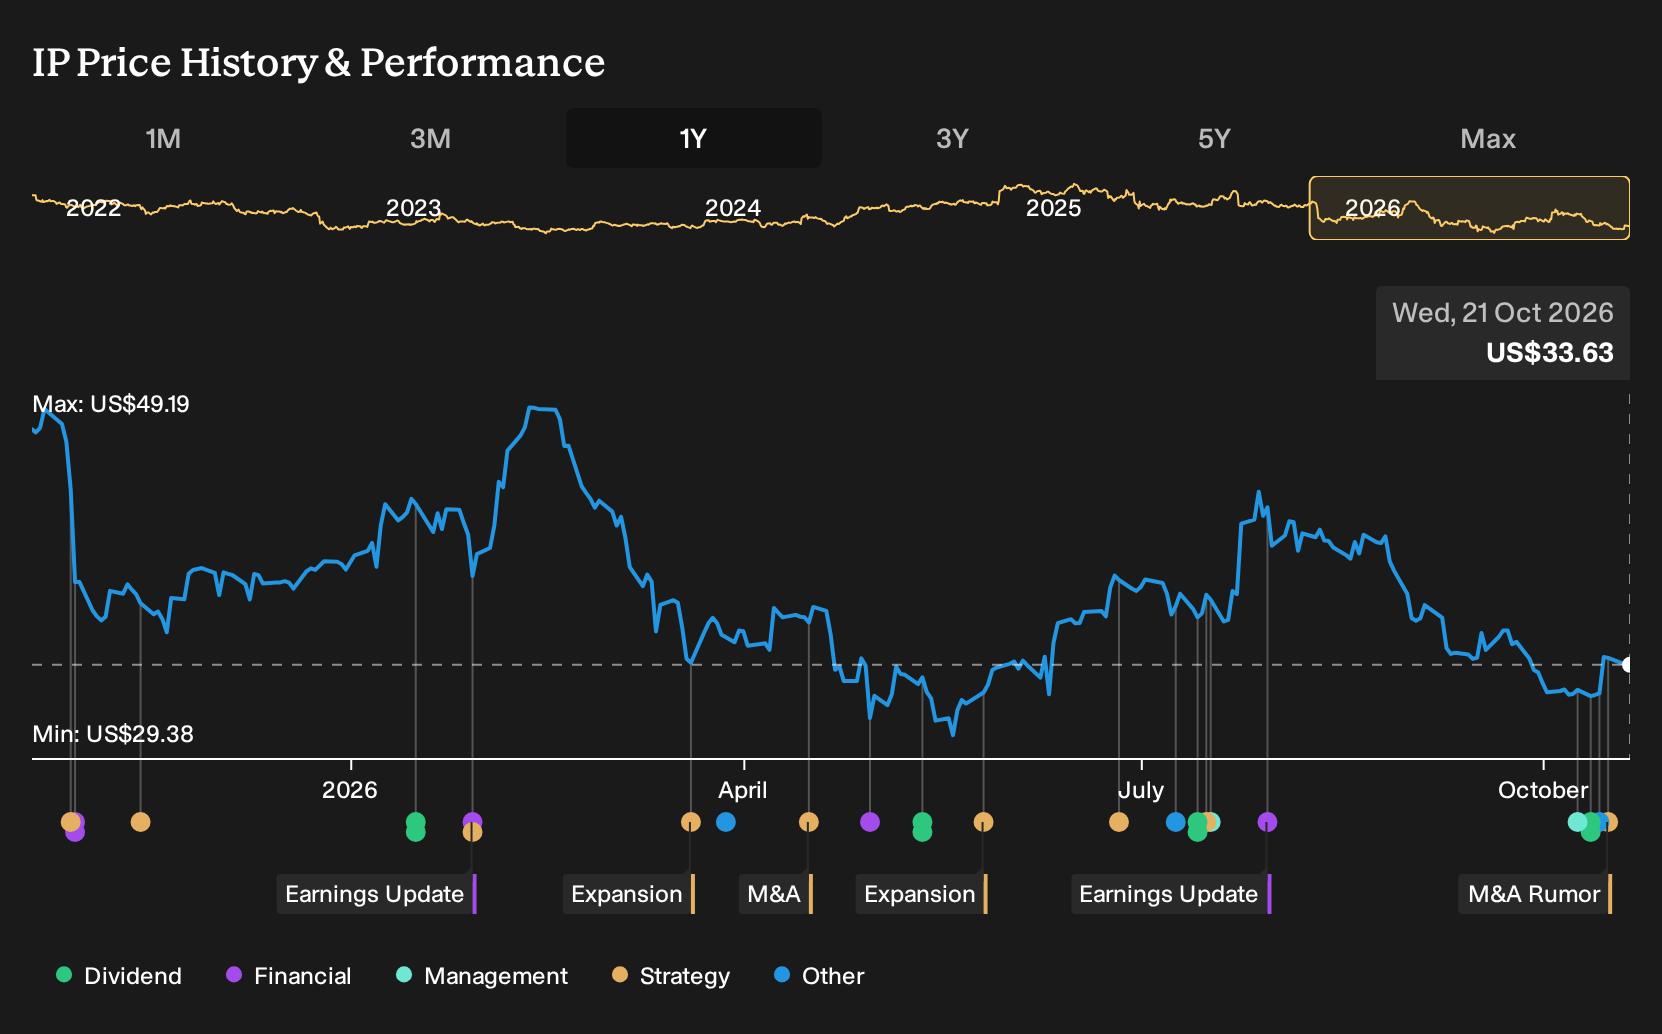
International Paper has spent the past year reshaping itself, from planning an EMEA spin-off to buying mills on both coasts and shutting several U.S. plants. Investors who held International Paper over the past year are down 26.4%, including dividends. That result reflects every twist in the story, not just one headline. If you had bought in back in October 2025, which part of this restructuring drive really deserved your attention?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
International Paper is not the only name tied to this theme. Zero in on 16 top copper producer stocks and compare how each one is priced.
The Two Stories Investors Had To Weigh On International Paper
The shares cost US$47.68 at the start of the period, and International Paper sat between two very different stories about where the packaging group might head next.
The bullish Narrative put Fair Value at US$54.26, built on the belief that a long shift toward fiber-based, recyclable packaging and e-commerce demand would support revenue and pricing. At the same time, automation and mill upgrades were expected to lower costs.
The bearish view set Fair Value at US$42.1 and focused on pressure from digital communication, rising compliance costs around single use packaging, and mill reliability problems that could demand heavier spending and strain free cash flow.
What The Evidence Did To The International Paper Argument
The heaviest evidence came from International Paper’s Q2 2026 figures, where revenue slipped from US$6,142m to US$6,004m and a US$75m profit turned into a US$12m loss. Net margin moved from 1.2% to a loss of 0.2%. That challenged the bullish promise of cleaner profitability and left the cautious case looking closer to the mark.
For your next company, focus on whether a restructuring story actually shows up in net margin. Check if margin trends move in the same direction as all the cost-cut and asset-sale headlines.
What International Paper's Drop Is Asking You To Believe
International Paper trades at US$33.63 after a 26.4% loss over the past year, and the selected Narrative places Fair Value above that level rather than at or below it. The thesis leans on volume gains, defined cost removal and mill reinvestment, plus the planned EMEA separation.
Before treating the fall as opportunity instead of warning, a buyer today would need to believe International Paper can deliver the targeted structural cost-out and on-time capex so upgraded mills and converting plants translate into steadier earnings quality.
"Bullish analysts expect International Paper to turn its structural cost-out program, mill modernization and tighter containerboard supply into higher quality earnings as the current investment cycle flows through. The main thing that has to go right is that International Paper delivers the targeted structural cost removal of more than $1b while keeping elevated capex on time and on budget so that the upgraded mills and converting plants support reliable output and pricing."
The price and this Narrative do not agree. → Uncover what this Narrative says International Paper is actually worth
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 21% below our estimate - supplies liquid cooling and power systems that make dense AI racks workable.
- Company 2 - 40% below our estimate - expands from trackers into storage and inverters to deepen revenue per project.
- Company 3 - 39% below our estimate - scales device trade-in and refurbishment as policy support and recycling habits improve.
Those are three of them. See every one of the 33 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com