
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rorze (TSE:6323) Lifts Outlook And Dividend As Valuation Questions Return
Rorze (TSE:6323) has drawn fresh attention after lifting its full year earnings outlook and guiding to a higher year end dividend for the period ending February 28, 2027.
That guidance shift has landed after a choppy stretch for Rorze’s share price, which is down 17.11% over the past week and 15.59% over the last 90 days, yet still carries a 53.31% year to date share price return and a 1 year total shareholder return of 86.42%. This suggests that long term momentum remains strong even as near term sentiment cools.
Scan for other semiconductor and automation stocks showing similar earnings momentum and shareholder payout shifts with our curated list of 93 robotics and automation stocks.
Rorze has paired a sharp pullback with stronger earnings and a richer dividend outlook, so the tension now is simple: Lean into the reset, or wait and hope for an even cheaper entry before the valuation work begins?
Preferred P/E of 26.8x: Is it justified?
Rorze closed at ¥3,710, and on that price it trades on a P/E of 26.8x, which screens as expensive against both the broader JP Semiconductor industry and closer peers.
The P/E ratio compares the current share price with earnings per share and gives a quick read on how much investors are paying for profits today. For a capital intensive field like semiconductor equipment and automation, a richer P/E can sometimes reflect expectations for earnings growth and relatively resilient profitability rather than just current results.
Rorze is priced at 26.8x earnings while the JP Semiconductor industry sits at 20.4x and the peer average is 20.7x. As a result, the market is clearly paying a premium for this stock. The SWS fair P/E estimate is 31.2x, which is materially higher than the current multiple and indicates that, if that fair level is reached, the market valuation would move toward a fuller earnings multiple for the business.
Explore the SWS fair ratio for Rorze.
Result: Price-to-earnings of 26.8x (OVERVALUED)
Still, Rorze’s heavy exposure to cyclical semiconductor equipment spending and its relatively small life science segment leave the story vulnerable if customer capex or niche projects stall.
Find out about the key risks to this Rorze narrative.
Another view on Rorze’s value
The SWS DCF model presents a very different picture for Rorze. From a cash flow perspective, the shares at ¥3,710 appear expensive relative to an estimated intrinsic value of ¥1,246.64, which indicates limited downside protection if growth or margins are weaker than expected.
Look into how the SWS DCF model arrives at its fair value.
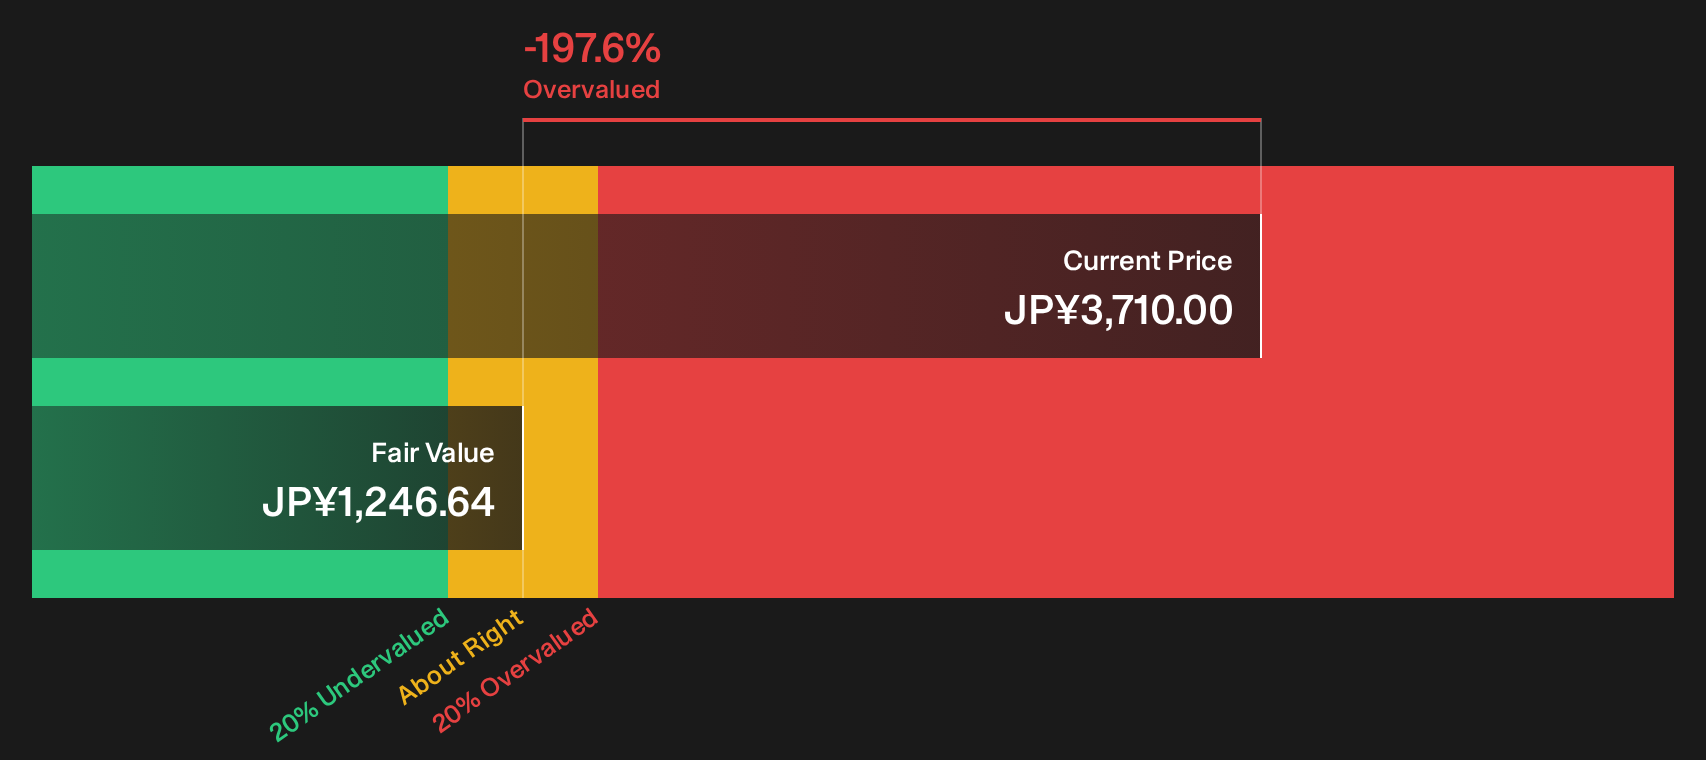
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rorze for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed message or clear signal for Rorze? Use these numbers as a starting point, then pressure test the upside and downside yourself with the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Rorze?
If Rorze has your attention but you want a few fresh angles, use this pullback window to scan for other opportunities before the next move leaves you catching up.
- Target resilience by focusing on balance sheets that look built to handle stress with a list of solid balance sheet and fundamentals (22 results).
- Hunt for mispriced quality by zeroing in on companies that combine strong fundamentals with appealing entry points using the 14 high quality undervalued stocks.
- Lean toward staying power and consistency by reviewing a 21 resilient stocks with low risk scores that filters for businesses scoring well on risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com