
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Earnings Upgrades Change Plains All American Pipeline Stock Narrative
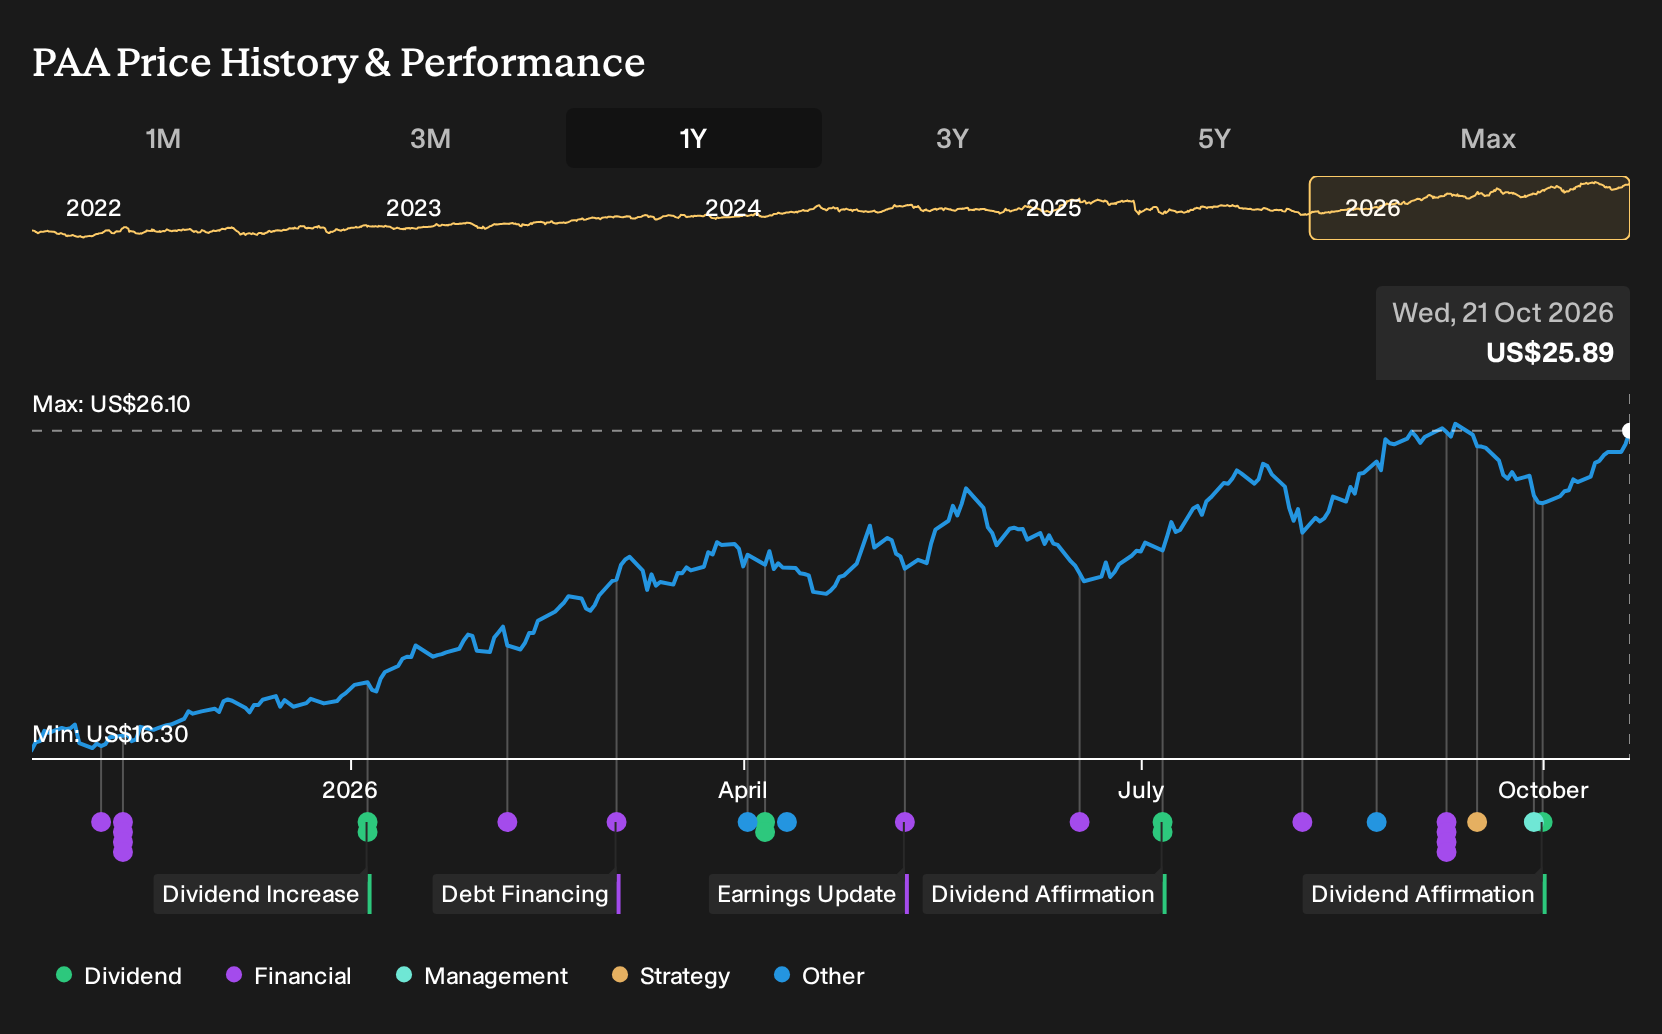
- Plains All American Pipeline recently lifted its quarterly distribution to US$0.4175 per unit with a 6.8% yield, supported by free cash flow coverage of 1.57x and by higher Permian pipeline volumes and updated guidance for adjusted free cash flow and EBITDA.
- The higher payout, together with raised full year targets, indicates that Plains All American Pipeline is placing greater emphasis on cash generation from its crude focused midstream network while continuing to address leverage that remains above its stated range until the NGL sale closes.
- We will now look at how Plains All American Pipeline's higher distribution coverage reshapes the investment narrative investors have been using.
Plains All American Pipeline Investment Narrative Recap
Owning Plains All American Pipeline means buying into a crude focused midstream platform that leans on Permian volumes, fee based contracts and disciplined project returns. The key near term catalyst is whether higher throughput and cost savings continue to support free cash flow after funding a richer distribution and growth capital. The recent increase in payout, backed by 1.57x free cash flow coverage, helps that story but does not change it.
The biggest risk is still concentration in crude oil infrastructure with a sizeable capital plan and leverage above the target range until the NGL sale closes. Any slowdown in basin activity or weaker tariffs would hit volumes and cash generation directly, limiting flexibility on future distributions and debt reduction if conditions soften.
The distribution raise to US$0.4175 per unit with a 6.8% yield is the clearest recent marker for how Plains All American Pipeline sees its near term cash profile. Management paired that move with higher full year targets for adjusted free cash flow and EBITDA, which ties the income story directly to current operating momentum, especially in the Permian and on assets like Cactus III.
For you as an income focused holder, the announcement matters because it tests whether growth capital, acquisitions such as EPIC Crude Holdings and leverage can coexist with a rising payout. If projects such as the Cactus III expansion and Powder River Basin build out stay on track, they support volumes and fee based earnings. If returns disappoint or crude activity eases, those same commitments could tighten the room to keep the higher distribution comfortable over time.
Plains All American Pipeline is currently modelled to grow revenue by 6.8% a year, reaching US$63.8b of revenue and US$1.6b of earnings by 2029. This implies an earnings increase of about US$779m from current earnings of US$821.0m.
Uncover why Plains All American Pipeline's fair value indicates value that aligns with its current price.
Exploring Other Perspectives
Across 2 retail valuations from the Simply Wall St Community, fair value runs from US$26 to about US$73.28, so you are seeing a very wide spread on Plains All American Pipeline. Some contributors lean on debt reduction and cost efficiencies as upside drivers, while others focus on crude concentration and project execution risk. That gap in opinion is your cue to compare several viewpoints before deciding how this fits your income portfolio.
Explore another Plains All American Pipeline fair value estimate, including one that suggests potential upside of up to 183% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Plains All American Pipeline research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Plains All American Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plains All American Pipeline's overall financial health at a glance.
Looking For More Income Ideas Beyond Plains All American Pipeline?
If you like what Plains All American Pipeline offers but want a wider bench of income and quality candidates, the Simply Wall St screener can help you build a watchlist that fits your own risk and return preferences, not someone else's checklist.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses that pair income potential with financial strength.
- Seek out mispriced opportunities by reviewing a 33 high quality undervalued stocks that filters for quality fundamentals at what could be compelling prices.
- Anchor your portfolio around payouts by using a 7 dividend fortresses and compare yields and coverage across a curated set of income candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com