
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
TransAlta (TSX:TA) Could Be 20% Undervalued Following Its Wind Sale And Gas Deal
TransAlta (TSX:TA) has reshaped its power mix by closing the sale of a 49% interest in its 500 MW Oklahoma wind portfolio and buying two contracted gas peaking plants near Denver for about US$1.3 billion combined.
The fresh asset shuffle comes at a time when TransAlta’s share price is CA$18.71, with a 1-month share price return of 8.21%, a 1-year total shareholder return that declined 18.90%, and a 3-year total shareholder return that is up 89.11%, suggesting long-term momentum despite more mixed recent sentiment.
Scan opportunities beyond TransAlta by reviewing our hand-picked list of 4 high quality undervalued stocks with resilient cash flows and balance sheets.
TransAlta now owns more contracted gas capacity and less of its Oklahoma wind portfolio. The business mix looks stronger on paper. The real question is whether the current CA$18.71 share price already reflects that shift.
Most Popular Narrative: 20.4% Undervalued
On the prevailing thesis, TransAlta’s CA$23.50 fair value sits well above the current CA$18.71 share price. The gap comes down to whether the market is underpricing long dated, contracted cash flows tied to its latest reshuffle and growth projects.
TransAlta’s program to acquire and recycle assets into longer term contracted positions, evidenced by the C$1 billion Colorado peaking acquisition with 25 to 30 year contracts and the contracted Far North assets in Ontario, is gradually increasing portfolio contractedness and average contract life, which can stabilize revenue and reduce earnings volatility.
See why 27 investors see TransAlta as 20% undervalued.
Result: Fair Value of CA$23.50 (UNDERVALUED)
Still, softer Alberta power prices already weighing on hydro and marketing earnings, and S&P’s negative outlook on TransAlta’s credit profile, could quickly challenge that undervaluation story.
Find out about the key risks to this TransAlta narrative.
Another View: What TransAlta’s Sales Multiple Is Saying
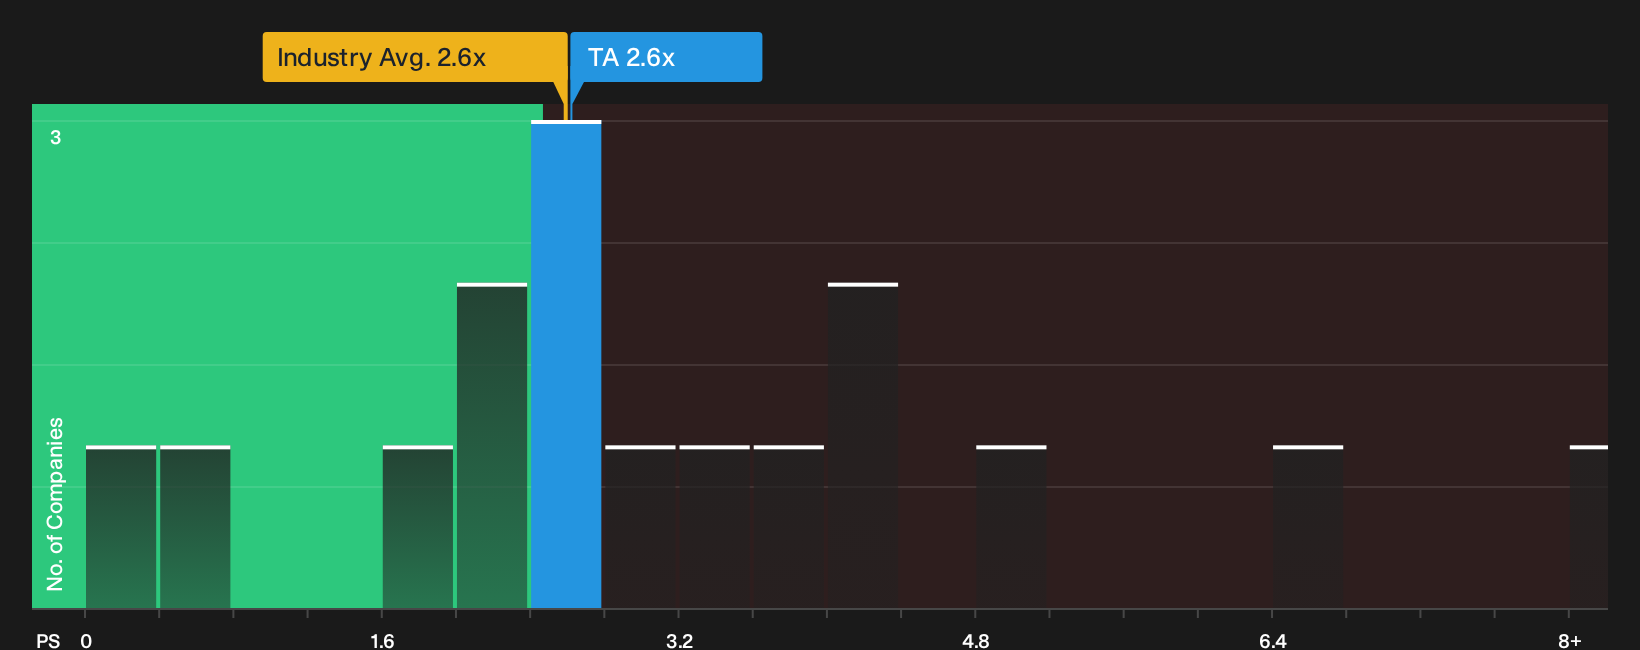
There is a catch. While the narrative and fair value model point to TransAlta as undervalued, the current P/S of 2.6x sits slightly above both the North American renewable peer average of 2.5x and the fair ratio of 1.7x, hinting at valuation risk if sentiment cools.
For a closer look at how this pricing gap could close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on TransAlta can make the story feel murky, so pull up the numbers yourself and pressure test the narrative before it moves. To see exactly what optimism is anchored to, review the 3 key rewards.
Looking for more investment ideas beyond TransAlta?
If you stop with TransAlta, you miss the wider picture. Put a few minutes into fresh ideas and you could level up your whole portfolio.
- Target potential mispricing and sift for quality by scanning our curated set of 4 high quality undervalued stocks that pair strong fundamentals with appealing valuations.
- Build a steadier income stream by homing in on 3 dividend fortresses that combine higher yields with business models focused on ongoing payouts.
- Dial down portfolio stress by reviewing a 8 resilient stocks with low risk scores designed to spotlight companies with more resilient risk profiles and fewer financial red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com