
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Lower Earnings Change NVR Stock Narrative
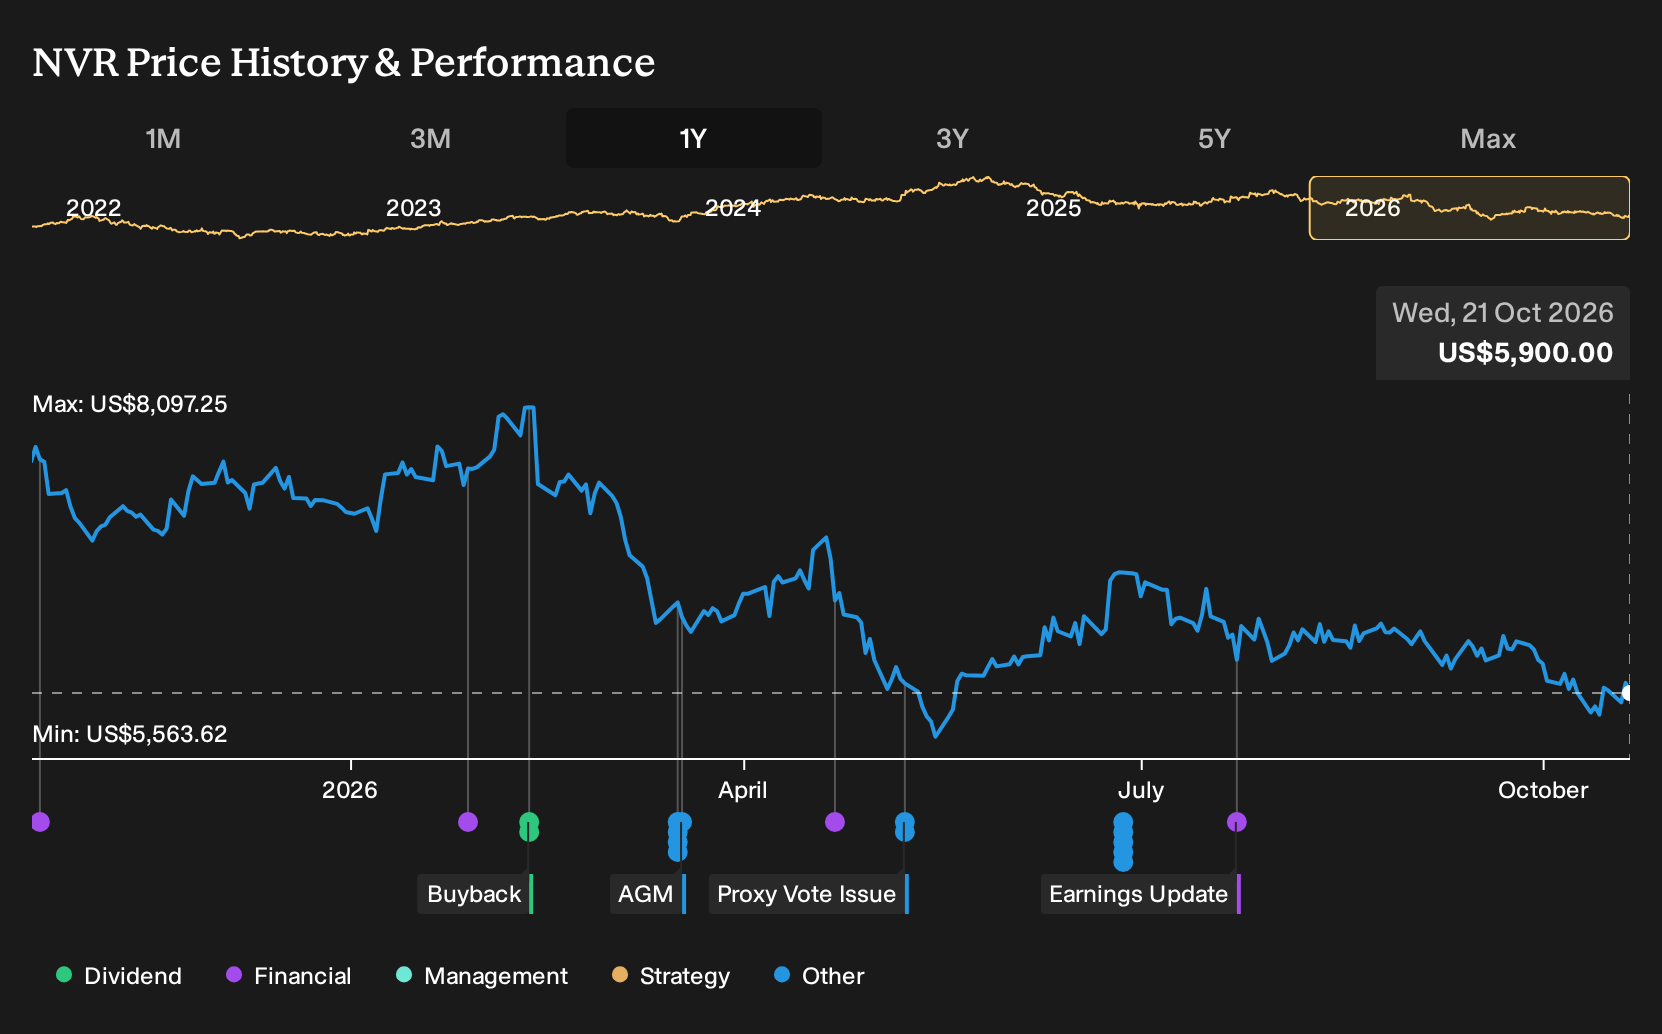
- NVR reported third quarter 2026 net income of US$248.61 million and basic EPS from continuing operations of US$93.49, both lower than the prior year. For the first nine months, net income was US$683.42 million and basic EPS was US$251.99.
- The earnings update highlights pressure on NVR's profitability, as diluted EPS from continuing operations declined for both the quarter and year to date. This points to questions about cost structure and demand quality rather than headline revenue alone.
- The focus now turns to how NVR's investment narrative absorbs this sharp earnings drop and what that may imply for a long term thesis.
What Is NVR's Investment Narrative?
NVR attracts long term shareholders who believe in a relatively disciplined homebuilding model, backed by a seasoned management team, high historical return on equity at 33.7% and a focus on controlled capital use rather than land speculation. That story now has to sit alongside a clear reset in earnings, with third quarter and year to date profit and EPS lower than last year and analysts already expecting pressure on profitability rather than improvement.
The recent miss on earnings quality, together with trimmed exposure from the iShares U.S. Home Construction ETF, puts short term attention squarely on order quality, pricing power and build cost control rather than headline revenue. Forecasts that point to modest revenue growth of 1.3% per year and declining earnings add to that pressure, especially with NVR trading on a P/E of 13.8x and still screening as good value against some fair value estimates.
That said, there is a less comfortable part of the NVR story that hinges on ...
There's only one way to know the right time to buy, sell or hold NVR. Head to Simply Wall St's company report for the latest analysis of NVR's Fair Value.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$3,758 to about US$7,146 per share, so retail opinion on NVR is already wide even before factoring in the fresh earnings decline. Use that spread as a prompt to stress test your own assumptions and to compare several alternative angles on future profitability.
Explore 2 other NVR fair value estimates, including one that suggests as much as 36% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NVR research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NVR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NVR's overall financial health at a glance.
Looking for more investment ideas beyond NVR?
If NVR's earnings reset has you rethinking concentration risk, it can help to widen the lens and compare it with other businesses that offer different combinations of quality, income, and downside protection.
- For investors who care most about stability and financial resilience, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching the balance sheet.
- If capital preservation is your first filter, narrow your search to a 31 resilient stocks with low risk scores that focuses on lower volatility profiles and cleaner risk scores.
- Those hunting for fresh stories rather than well known tickers can scan a 21 high quality undiscovered gems that highlights underfollowed companies with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com