
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ASX Growth Companies With High Insider Ownership October 2026
As the ASX 200 faces a flat start amid global market influences and rising concerns about inflation and geopolitical risks, Australian investors are closely monitoring potential interest rate changes. In this context, growth companies with high insider ownership can offer unique insights into market confidence, as insiders often have a deep understanding of their company's potential amidst fluctuating conditions.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 15.7% | 85% |
| Torque Metals (ASX:TOR) | 13.1% | 70.8% |
| Starpharma Holdings (ASX:SPL) | 17.3% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 14.7% | 28.3% |
| PDI Gold (ASX:PDI) | 11.1% | 62.7% |
| Innovaero Technologies (ASX:INN) | 37.9% | 66.2% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Austral Resources Australia (ASX:AR1) | 22.6% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
Let's uncover some gems from our specialized screener.
Artrya (ASX:AYA)
Simply Wall St Growth Rating: ★★★★★☆
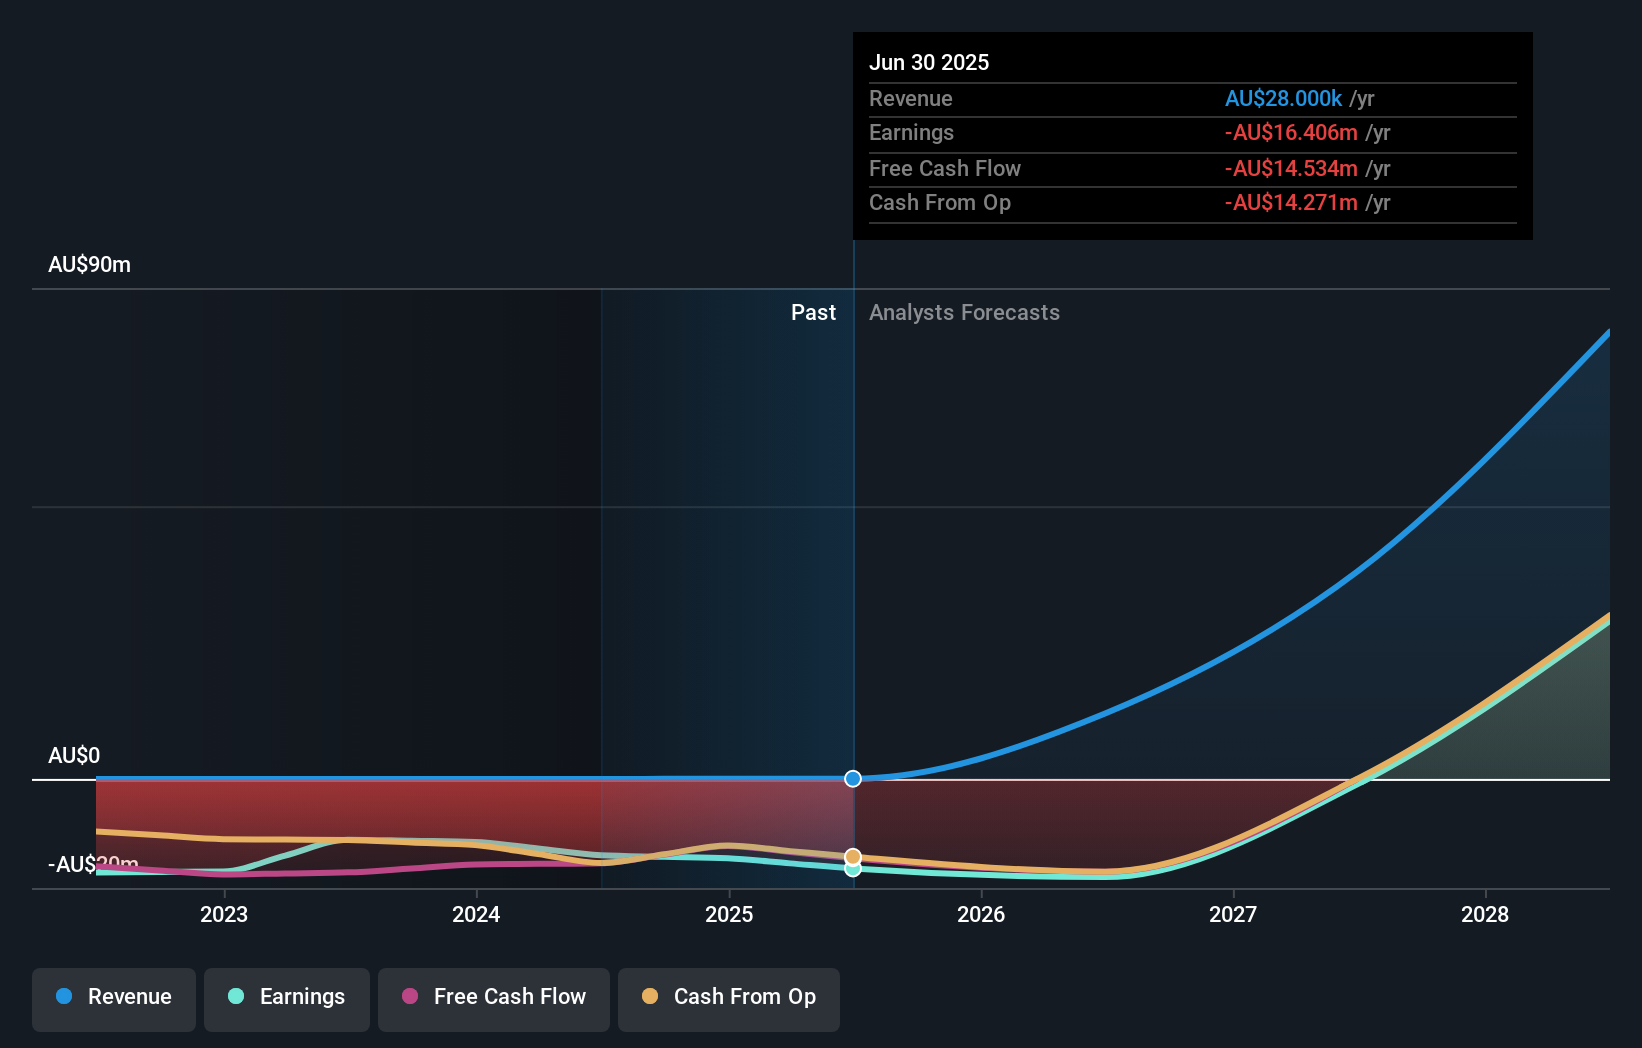
Overview: Artrya Limited is a medical technology company focused on developing and commercializing an artificial intelligence platform for detecting, diagnosing, and addressing coronary artery disease in Australia, with a market cap of A$431.85 million.
Operations: The company's revenue segment includes A$0.03 million from the development of AI-driven CCTA image analysis technology.
Insider Ownership: 10.8%
Earnings Growth Forecast: 56.4% p.a.
Artrya's recent inclusion in several indices, including the S&P/ASX 300, highlights its growing market recognition. Despite reporting a net loss of A$25.18 million for the year ending June 2026, revenue is forecast to grow significantly at 52.2% annually, outpacing the broader Australian market. The anticipated profitability within three years and trading below fair value suggest potential upside. Helen Kurincic's board appointment brings valuable experience in healthcare and ASX compliance to support strategic growth initiatives.
- Get an in-depth perspective on Artrya's performance by reading our analyst estimates report here.
- Our valuation report unveils the possibility Artrya's shares may be trading at a discount.
FDC Consolidated Holdings (ASX:FDC)
Simply Wall St Growth Rating: ★★★★★☆
Overview: FDC Consolidated Holdings Limited offers construction, fitout, and refurbishment services in Australia with a market capitalization of A$1.12 billion.
Operations: The company generates revenue through its construction services at A$1.02 billion and fitout & refurbishment services at A$672.32 million.
Insider Ownership: 14.8%
Earnings Growth Forecast: 73% p.a.
FDC Consolidated Holdings is set to become profitable within three years, with earnings projected to grow 72.99% annually, outpacing the market. Despite a net loss of A$58.2 million in 2026, revenue is expected to reach A$1.9 billion in 2027 and grow faster than the Australian market at 8.4% per year. The stock trades at a significant discount below fair value, with analysts forecasting a price rise of 31.4%.
- Click here and access our complete growth analysis report to understand the dynamics of FDC Consolidated Holdings.
- Upon reviewing our latest valuation report, FDC Consolidated Holdings' share price might be too pessimistic.

Universal Store Holdings (ASX:UNI)
Simply Wall St Growth Rating: ★★★★★☆
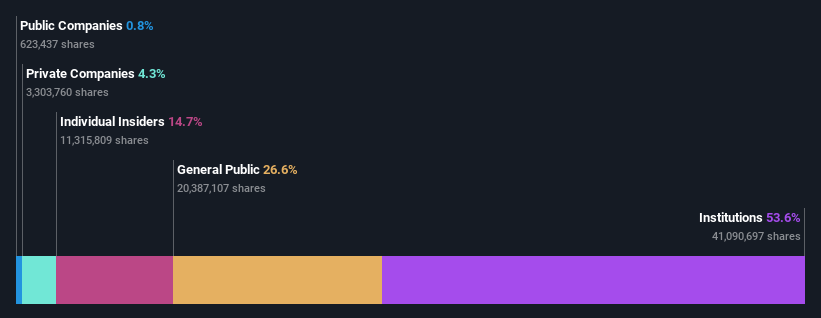
Overview: Universal Store Holdings Limited operates in the Australian fashion retail market, with a market cap of A$611.46 million.
Operations: The company's revenue segments include CTC at A$36.36 million and US & PS at A$349.15 million.
Insider Ownership: 12.6%
Earnings Growth Forecast: 21.3% p.a.
Universal Store Holdings demonstrates potential with earnings forecasted to grow significantly at 21.3% annually, surpassing the Australian market's growth rate. Despite a drop in net income to A$18.23 million from A$23.26 million, revenue rose to A$376.14 million from last year’s A$333.27 million. Trading at a substantial discount below fair value, analysts predict a price increase of 29.2%. However, profit margins have decreased and dividends are not fully covered by earnings.
- Click to explore a detailed breakdown of our findings in Universal Store Holdings' earnings growth report.
- Our expertly prepared valuation report Universal Store Holdings implies its share price may be lower than expected.
Taking Advantage
- Unlock more gems! Our Fast Growing ASX Companies With High Insider Ownership screener has unearthed 116 more companies for you to explore.Click here to unveil our expertly curated list of 119 Fast Growing ASX Companies With High Insider Ownership.
- Interested In Other Possibilities? We've found 9 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com