
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Comfort Systems USA (FIX) Heads Into Earnings As Backlog And Cash Flow Shape Value
Comfort Systems USA (FIX) heads into its third quarter earnings release after today’s closing bell, with attention squarely on revenue momentum, cash generation, and a record backlog tied to data center and technology infrastructure work.
Comfort Systems USA’s share price has pulled back sharply in the run-up to earnings, with the stock down 14.2% over the past month and 23.5% over the last 90 days. It still carries a strong year-to-date share price return of 39.6% and an exceptionally high five-year total shareholder return that is more than 15x, pointing to long-term momentum even as near term sentiment cools ahead of the Q3 release.
Scan beyond Comfort Systems USA and see how other project driven contractors are setting up for their next earnings catalysts with the hand picked 42 power grid technology and infrastructure stocks.
After a sharp pullback yet still strong multi year returns, Comfort Systems USA now sits at a valuation that splits opinion. Does the current setup still tilt the risk reward in favour of new buyers, or not?
Most Popular Narrative: 36% Undervalued
Comfort Systems USA last closed at $1,401.27, which is well below the most followed narrative fair value of $2,197. This figure is based on an 8.78% discount rate and is linked to its backlog, technology heavy mix, and service potential.
Strong gross margin levels in both Mechanical and Electrical, together with nearly US$1b of free cash flow in Q2 2026 and a net cash position of more than US$1.8b, give Comfort Systems USA room to keep investing roughly 5% of revenue in growth projects and acquisitions that can support future earnings and cash generation.
See why 90 investors see Comfort Systems USA as 36% undervalued.
Result: Fair Value of $2,197 (UNDERVALUED)
Still, this narrative can break if AI linked data center and semiconductor projects slow or if investors cut the P/E multiple after recent insider selling.
Find out about the key risks to this Comfort Systems USA narrative.
Another View: Comfort Systems USA Through The P/E Lens
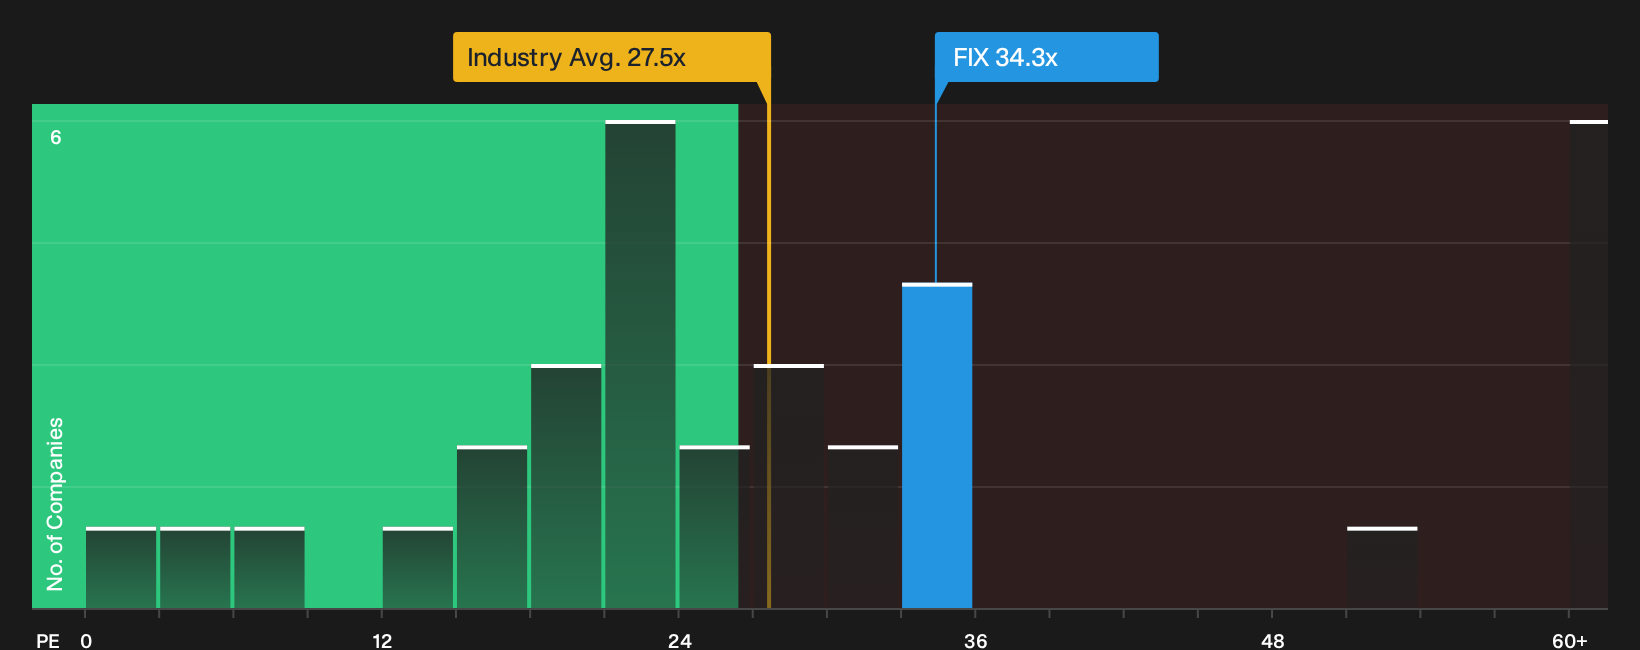
There is a very different picture once you move away from narrative fair value and look at plain P/E math. Comfort Systems USA trades on a 34.3x P/E, which is higher than the US Construction industry at 27.5x but slightly below a 37x peer average and an estimated fair ratio of 40x. That gap suggests the stock already prices in strong expectations, yet still leaves room for the market to move the multiple either closer to the industry level or toward the higher fair ratio, which would have very different outcomes for investors thinking about entry or exit levels.
That is why it can help to step back from the story and test what the numbers imply at different earnings multiples, then ask where you think Comfort Systems USA should really sit in that range, and why. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong views are forming on both sides of the Comfort Systems USA debate, and the data is moving quickly enough that your view should too. To weigh those concerns against the potential upside, spend a few minutes with the 4 key rewards and 1 important warning sign.
Looking for more Comfort Systems USA style investment ideas?
If you want to stay ahead of the next big moves, cast your net wider now and let high quality screeners surface opportunities you might otherwise miss.
- Prioritise valuation first and let the numbers point you toward potential mispricings with the 33 high quality undervalued stocks.
- Target resilience under pressure by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Lock in cash return potential alongside price moves by focusing on payout heavy opportunities through the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com