
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Toronto Dominion Bank (TSX:TD) Could Be 3% Undervalued Following Fresh Funding Moves
Toronto-Dominion Bank (TSX:TD) has been busy in its funding stack, rolling out a series of new fixed-income offerings and covered bonds that give you extra visibility into how the bank is sourcing capital.
That funding activity lands in a market where Toronto-Dominion Bank’s share price has climbed to CA$175.11, with a 1-day share price return of 1.98% and a year-to-date share price return of 34.89%. The 1-year total shareholder return of 59.48% and very strong 3-year and 5-year total shareholder returns suggest momentum has been building over a longer stretch as investors react to earnings strength, AI-led efficiency projects and the recent share repurchase program.
Spot similar momentum and balance-sheet stories by scanning our curated list of 4 high quality undervalued stocks that share some of the same funding and earnings themes as Toronto-Dominion Bank.Toronto-Dominion Bank has just rallied hard, powered by stronger earnings, AI projects and a big buyback. The next step is simple: does the current valuation already reflect that surge, or is patience still rewarded?
Most Popular Narrative: 2.8% Undervalued
On the most followed view, Toronto-Dominion Bank screens as modestly undervalued, with a fair value of CA$180.07 against the latest close at CA$175.11. That gap depends on whether efficiency gains and capital returns continue to provide most of the support.
The main requirement is that TD turns its strong capital position and large AI and cost reduction programs into sustained efficiency improvements that more than offset higher AML remediation and growth spending.
The current valuation implies the share price already reflects a fairly valued, bullish view on TD delivering record-level profitability with a CET1 ratio moving toward 13%, material buybacks of over $13 billion in 2027, and rising contributions from U.S. and wholesale businesses.
See why 185 investors see Toronto-Dominion Bank as 3% undervalued.
Result: Fair Value of CA$180.07 (UNDERVALUED)
Still, this story can change quickly if U.S. AML remediation costs climb further or if AI efficiency gains fail to offset heavier compliance and control spending.
Find out about the key risks to this Toronto-Dominion Bank narrative.
Another View: Toronto-Dominion Bank Looks Expensive On Earnings
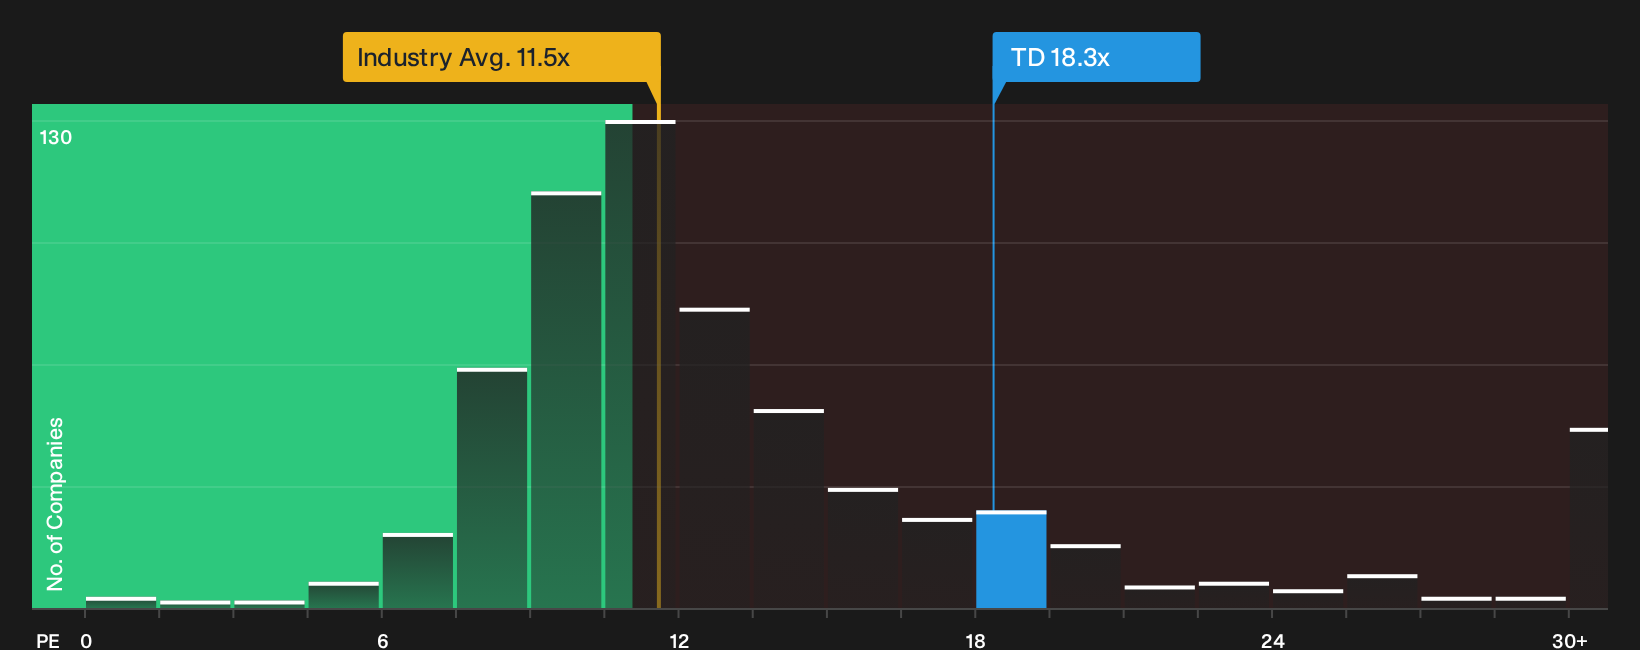
On a simple earnings multiple, Toronto-Dominion Bank screens quite differently. The current P/E of 18.3x sits above both the estimated fair ratio of 16.5x and the North American banks average of 11.5x, which points to less margin for error if growth or returns disappoint.
That kind of premium can reward you if AI efficiency, earnings and capital returns all line up, but it can also amplify any setback in profits or regulatory costs. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Toronto-Dominion Bank feels familiar, act while the data is fresh and pressure test the thesis yourself. To see what investors are excited about in the numbers, start by reviewing the 3 key rewards.
Looking for more Toronto-Dominion Bank style investment ideas?
If Toronto-Dominion Bank has sharpened your focus on quality and timing, now is the moment to widen your watchlist before the next wave of opportunities moves.
- Zero in on quality at a discount by scanning our hand picked 4 high quality undervalued stocks that line up strong fundamentals with more reasonable pricing.
- Strengthen your income stream by reviewing a focused set of 3 dividend fortresses that aim to combine yield with balance sheet support.
- Dial down portfolio risk by searching across a curated 8 resilient stocks with low risk scores that emphasizes resilience and financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com