
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Banco Santander (BME:SAN) Could Be 16% Undervalued After Jefferies Downgrade
Banco Santander (BME:SAN) has moved to tidy up part of its capital stack by pairing a full early redemption of two export finance covered bond series with a separate plan to call outstanding contingent convertible securities.
Recent price moves tell a mixed story. Banco Santander’s share price has slipped over the past month, with a 30 day share price return of 9.56% and a 7 day return of 4.28%. Total shareholder return over one year is 39.60% and over five years is more than 3x, suggesting longer term momentum remains strong even as the Jefferies downgrade and capital actions like the CoCo and covered bond redemptions feed into shorter term swings.
Compare how Banco Santander’s capital moves stack up against a hand-picked 224 resilient stocks with low risk scores that may appeal if you are focused on balance sheet strength and steadier profiles.
So is this latest pullback in Banco Santander telling you something new about the underlying bank, or just marking a reset in expectations after sentiment cooled on the Jefferies downgrade and capital calls as you weigh the current valuation?
Most Popular Narrative: 16% Undervalued
On Simply Wall St’s most followed view, Banco Santander’s fair value of €13.71 sits meaningfully above the last close of €11.48, so the current pullback is being framed as a valuation gap rather than a change in core earnings power.
Continued balance sheet optimisation and risk transfer activity, including plans to mobilise around €30b to €35b of risk weighted assets per year after around €45b in 2025, alongside the integration of TSB and Webster that is expected to add more than €1.5b of sustainable profit by 2028, could support net interest income resilience and improve net margins.
See why 86 investors see Banco Santander as 16% undervalued.
Result: Fair Value of €13.71 (UNDERVALUED)
Still, the Banco Santander story can fray quickly if credit costs in higher risk markets stay elevated, or if UK mortgage competition keeps squeezing spreads and returns.
Find out about the key risks to this Banco Santander narrative.
Another View: What Banco Santander’s P/E Is Really Telling You
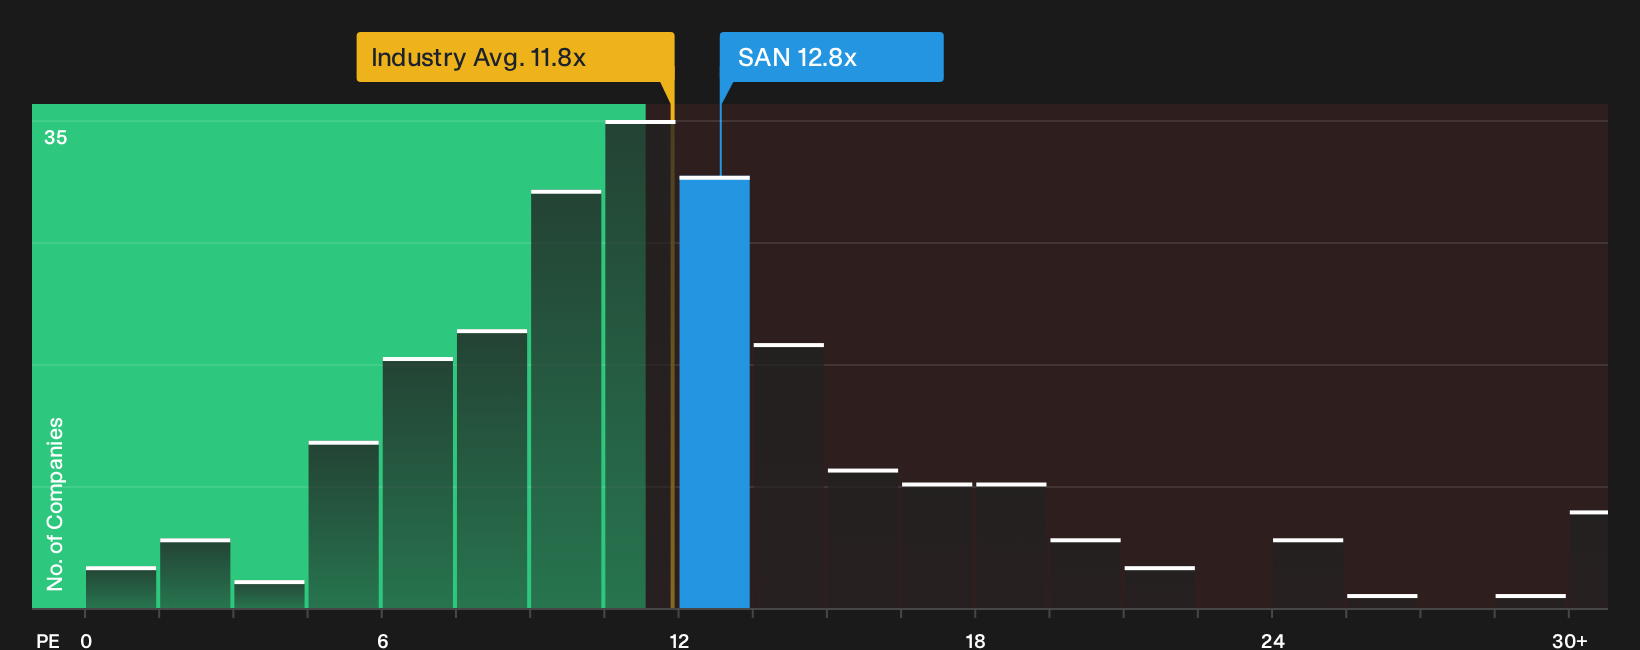
That €13.71 fair value marker leans on detailed cash flow work. A simpler lens, the P/E ratio, offers a different perspective. Banco Santander trades on 12.8x earnings. That is higher than the European banks group on 11.8x, yet below its peer average of 13.5x and under a fair ratio estimate of 16.3x. In practice, you are paying a slight premium to the sector, a small discount to close peers, and a deeper discount to where the ratio could drift if sentiment holds. This combination can be assessed as either a margin of safety or a sign that the multiple has already done some of the adjustment.
To examine whether this earnings multiple still leaves enough room for comfort versus risk, take a closer look at our valuation breakdown, including how the fair ratio has been derived, in the See what the numbers say about this price — find out in our valuation breakdown.
For a visual view of how Banco Santander’s current multiple compares with the wider sector, see the comparative chart in
Next Steps
If this mix of optimism and concern around Banco Santander leaves you undecided, move fast and inspect the evidence yourself through the 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Banco Santander?
Do not park everything in one opportunity. Spread your research across a few different angles so you can judge Banco Santander against real alternatives.
- Target potential upside by scanning for quality businesses trading below estimated value through the 196 high quality undervalued stocks.
- Prioritise stability and income by reviewing companies that appear in the 224 dividend fortresses.
- Zero in on financial resilience by focusing on businesses that feature in the list of solid balance sheet and fundamentals (203 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com