
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
French Bond Stress Has These Eurozone Financial Stocks Back In Focus
French bond markets are flashing red, with 10-year OAT yields above US Treasuries and the gap to German Bunds at levels last seen during the eurozone debt crisis. When funding costs and political risk flare up together, pricing in euro-area financials can move faster than the underlying fundamentals. This piece walks through three stocks closely exposed to that French story and explains where investors may see upside or added caution.
The stocks covered below are just a sample. The full screen on this theme surfaced 2 more eurozone financials with equally compelling French sovereign risk stories that are not included in the article.
Identify and analyze your own highest conviction ideas by heading straight into the Eurozone Financials with Elevated French Sovereign Risk Exposure screener
COFACE (ENXTPA:COFA)
Overview: COFACE is a French trade credit insurer that helps businesses worldwide protect against customers not paying, with services closely tied to euro-area credit conditions.
Operations: COFACE generates revenue mainly from Mediterranean and Africa at about €547 million, Western Europe and Africa at roughly €428 million, and Northern Europe at around €374 million, with additional meaningful contributions from Central Europe, North America, Asia-Pacific and Latin America.
Market Cap: €2.35b
COFACE matters in this screener because it sits at the intersection of French sovereign risk, euro-area corporate credit and real economy trade flows, so shifts in OAT spreads can quickly ripple through its underwriting and investment results.
"Rapid expansion of services such as business information and third party debt collection, which now generate more than €100 million of annualized revenue and are growing around 20% a year, could support a higher share of fee based and services revenue over time."
What really moves the dial for COFACE is how one quiet pressure on its balance sheet and payout policy resolves as French yields keep climbing.
That quiet pressure is exactly what the full narrative for COFACE unpacks, highlighting where French yields could be masking COFACE’s next leg of earnings power.
Caisse Régionale de Crédit Agricole Mutuel de la Touraine et du Poitou Société Coopérative (ENXTPA:CRTO)
Overview: Caisse Régionale de Crédit Agricole Mutuel de la Touraine et du Poitou Société Coopérative is a regional French cooperative bank focused on retail, agricultural, business, and public sector clients. It is closely linked to domestic credit conditions and French government funding.
Operations: The cooperative generates its €316 million of revenue entirely in France, leaving earnings and the balance sheet directly exposed to French economic and sovereign trends.
Market Cap: €653 million
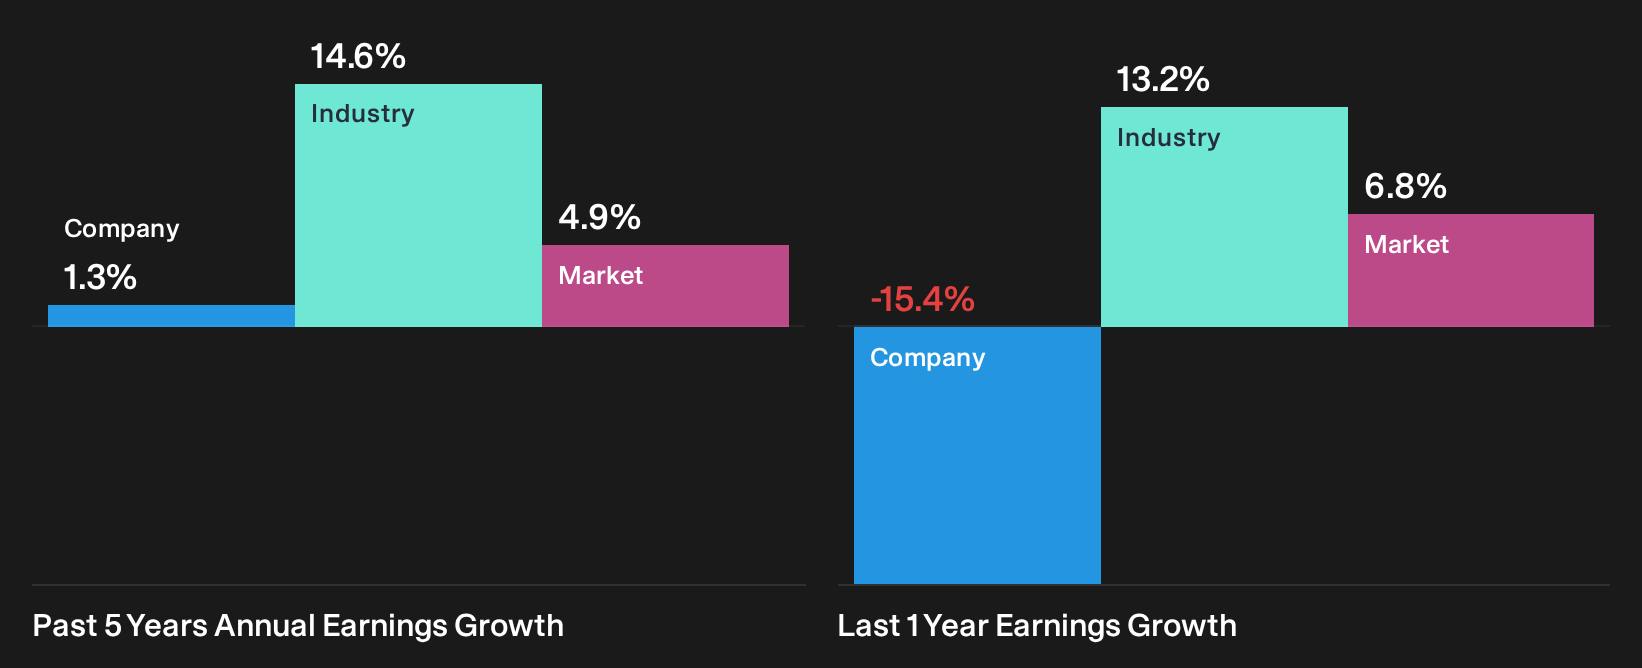
Caisse Régionale de Crédit Agricole Mutuel de la Touraine et du Poitou Société Coopérative offers concentrated exposure to French interest rates, with all revenue generated domestically and a balance sheet likely holding significant French government securities such as OATs. Investors considering rising net interest income and a low P/E may wish to assess how any unresolved pressures on French sovereign yields could affect margins.
Those margin questions are exactly where the Caisse Régionale de Crédit Agricole Mutuel de la Touraine et du Poitou Société Coopérative financial health report comes in, so you can see how French sovereign swings filter through capital strength and regional earnings power.

CVC Capital Partners (ENXTAM:CVC)
Overview: CVC Capital Partners is a global private equity and credit investor, backing leveraged deals and infrastructure assets that are sensitive to European interest rates.
Operations: The group earns most of its €1.75b revenue from €911 million in Private Equity, with meaningful contributions from Credit, Infrastructure and Secondaries strategies.
Market Cap: €12.78b
CVC Capital Partners matters for this French risk screen because its European credit and infrastructure funds rely on financing structures whose economics shift when French sovereign yields and OAT spreads move, so higher funding costs can feed directly into portfolio returns and carried interest potential.
"Strategic expansion into Private Wealth and insurance, with initiatives like CVC-CRED and CVC-PE, highlights a focus on long-term revenue growth and diversification of fee income sources."
What could really reshape the story for CVC Capital Partners is how one rate driven pressure feeds through to future fee margins and carry.
That rate pressure is only half the story, and the full narrative for CVC Capital Partners shows how CVC Capital Partners could turn funding swings into accelerating fee and carry potential.

Seeking Fresh Alternatives Before They Fly?
Markets move fast and the most interesting ideas rarely stay under the radar for long. Spot breakout potential and fading mispricing before the crowd, act now.
- Track future-defining automation trends and scan a curated set of industrial and tech players using the 93 robotics and automation stocks while the theme is still in its early stages.
- Hunt for resilient balance sheets that could help cushion portfolio swings by reviewing a hand picked list of solid balance sheet and fundamentals (203 results) before stress spreads more widely.
- Review potential opportunities related to power grid upgrades and electrification spending by checking a focused pool of 42 power grid technology and infrastructure stocks while they are still being quietly priced.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com