
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
i-80 Gold (TSX:IAU) Stock Looks Fully Priced After Its 50% Run
i-80 Gold has delivered a strong 49.6% share price gain over the past year, helped by a steady flow of Nevada mine development updates, which puts a fresh spotlight on how its current price stacks up against the sales it is generating today. With the story now heavily shaped by future production plans, the core issue for investors is how much revenue progress is already being priced in.
- The 49.6% 1 year return means anyone looking at i-80 Gold now has to judge whether the recent share price strength is aligned with what its sales can reasonably support.
- The updated Nevada plan, which targets future production growth from projects like Archimedes underground and Mineral Point, can shift expectations around future sales capacity and the timing of cash coming through the income statement.
- Your read on i-80 Gold is one view; the desks covering it have another. See what analysts think i-80 Gold's shares could be worth.
The issue now is whether the current valuation of i-80 Gold is adequately supported by its sales performance and sales outlook.
If you are weighing i-80 Gold against other miners, it can help to see how a wider set of producers with similar commodity exposure trade on their current output, so you can line it up beside the 35 elite gold producer stocks
Does i-80 Gold Look Pricey on Sales?
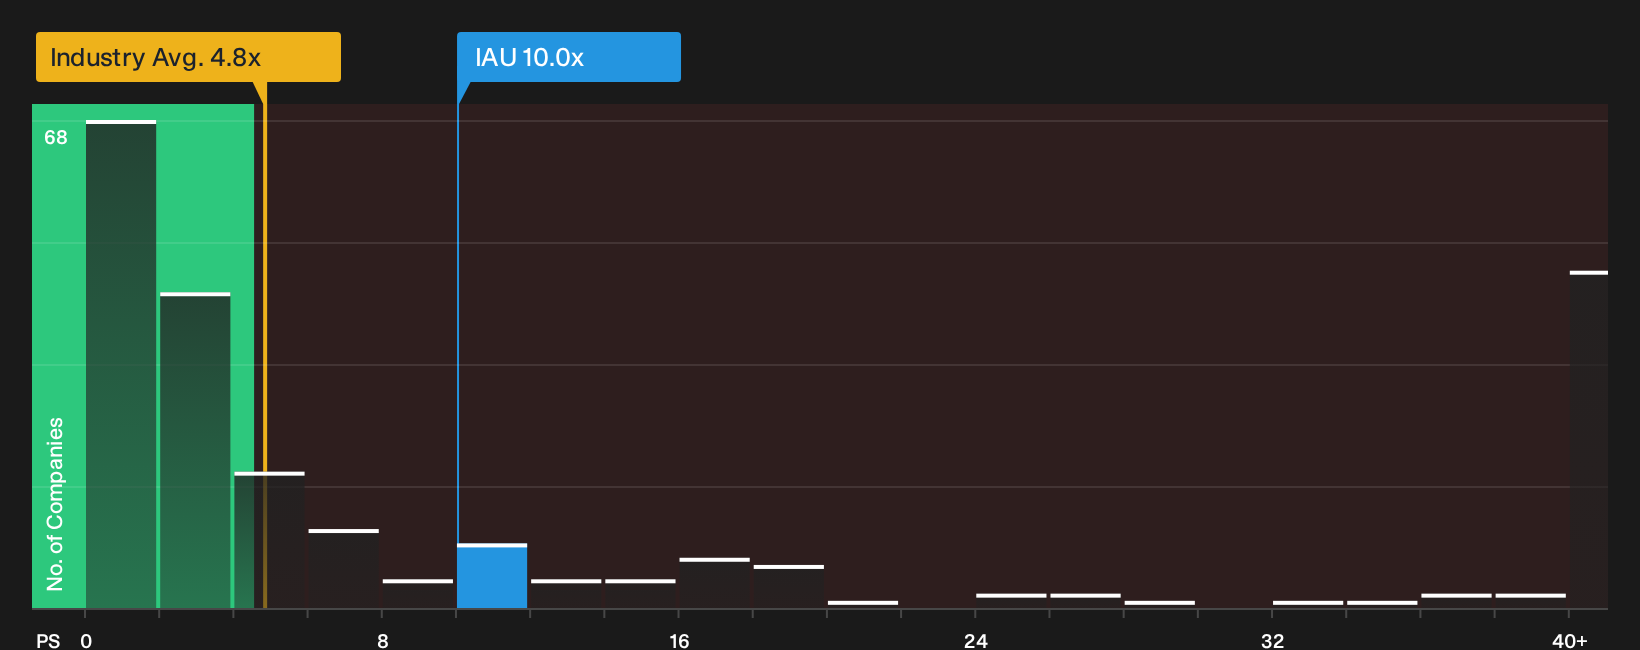
P/S is a useful lens for i-80 Gold because the business is still in a heavy build out phase where revenue and profits do not yet reflect the Nevada plan in full. The stock currently trades on a P/S of 10.0x, which is higher than both the Metals and Mining industry average of 4.8x and the peer group around 5.8x. That puts a premium price on each dollar of current sales compared with similar producers.
On a more tailored view that blends i-80 Gold’s size, margin profile, sector and risk, the implied fair P/S multiple is lower than where the shares trade today, so the stock screens as overvalued on this framework. Because the Nevada development update describes a path to higher planned production from Archimedes and Mineral Point, the current P/S suggests investors are already paying up for that future execution and funding work. Explore the numbers behind i-80 Gold's P/S valuation.
The i-80 Gold Narrative: What Would Justify Today's Price?
Narratives for i-80 Gold pick up where the P/S question leaves off and explain what growth, margin and earnings paths would need to occur for the stock to appear much stronger or weaker than today’s price on Simply Wall St’s Community page. Each scenario connects its figures to a clear view on how i-80 Gold’s future expansion, profitability and risk profile might evolve, so you can revisit those assumptions as fresh information arrives.
One of the top community narratives on i-80 Gold: 49% undervalued
"Industry-wide underinvestment in new gold projects, coupled with i-80's strategic Nevada asset base and in-house processing infrastructure, positions the company to benefit…"
Discover why this Narrative puts i-80 Gold at 49% undervalued.
For i-80 Gold, who is steering the ship and what are they being rewarded for?
Price tags tell only part of the story, because the people setting priorities, allocating capital and tying their pay to specific targets can tilt the whole risk profile. See who runs i-80 Gold and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com