
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CMS Energy (CMS) Could Be 11% Undervalued Following Earnings Beat Expectations
Why CMS Energy Is Back On Earnings Watch
CMS Energy (CMS) has moved into focus again as Wall Street points to an increased likelihood of an earnings beat, supported by a positive Earnings ESP and higher year-over-year EPS expectations.
The recent earnings anticipation around CMS Energy is landing on top of a share price that has climbed 5.30% over the past month but is still down 8.12% over 90 days. Total shareholder return over three and five years, at 37.61% and 31.84% respectively, points to a longer record that investors continue to weigh against the current US$68.13 share price, a fresh dividend affirmation of US$0.57 per share, and a new dividend reinvestment plan shelf registration.
Scan CMS Energy alongside a curated 42 power grid technology and infrastructure stocks that could also be setting up for earnings surprises and dividend stories of their own.
CMS Energy appears to be a solid regulated utility on the surface, with steady electric and gas operations and a reaffirmed dividend. After the recent share price rebound, the important question is whether that stability is already fully reflected in the current valuation.
Most Popular Narrative: 11% Undervalued
Against the last close at $68.13, the most followed narrative for CMS Energy points to a fair value of about $76.92. This frames today’s earnings discussion within a longer regulated capital plan and a Michigan-focused story.
The exit from nonutility renewable development and redeployment of roughly $1.7b of planned capital into Michigan rate-base projects is expected to concentrate CMS Energy earnings on regulated assets that typically carry defined returns. This structure could support more predictable EPS and cash flow.
See why 4 investors see CMS Energy as 11% undervalued.
Result: Fair Value of $76.92 (UNDERVALUED)
Still, the CMS Energy story can change quickly if Michigan regulators take a tougher line on future rate cases or if severe storms continue to drive higher unplanned costs.
Find out about the key risks to this CMS Energy narrative.
Another Look At CMS Energy’s Valuation
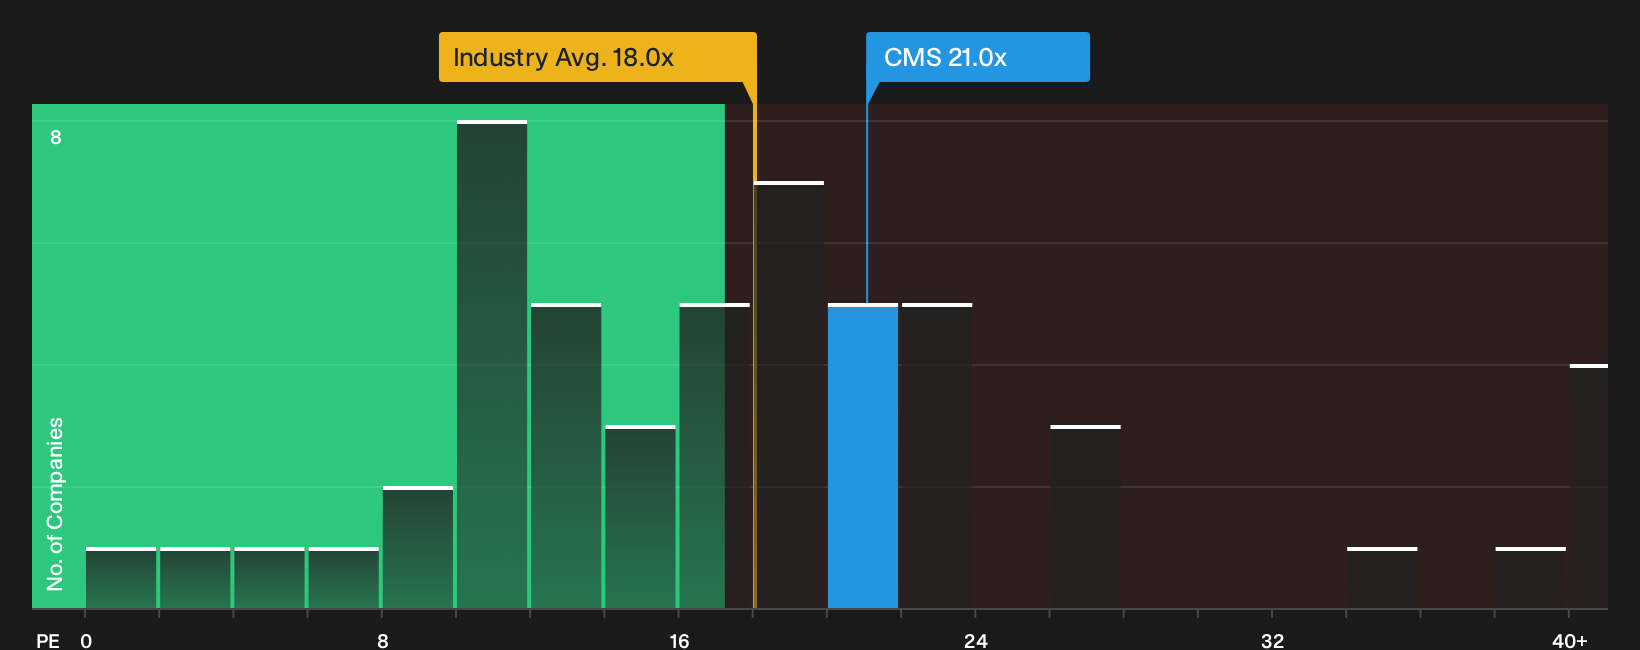
The first narrative paints CMS Energy as about 11% undervalued against a fair value of $76.92. A simple price check using the current P/E of 21x tells a different story. That multiple sits above the global integrated utilities average of 17.9x and also above a fair ratio of 20.5x, which suggests investors are already paying a premium for every dollar of earnings. The peer average of 21.5x softens that signal a little, but it still leaves you asking whether this premium leaves much room for error if growth or regulation disappoint.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If you are uncertain about CMS Energy after all this, or feel pressured to make a decision before the next move, consider both the potential upside and downside in 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond CMS Energy?
If CMS Energy has sharpened your focus on earnings quality and risk, do not stop here. Broader idea hunting can often reveal better fits.
- Target potential mispricing by scanning a focused 33 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen your income game and compare CMS Energy’s payout profile against a curated 7 dividend fortresses built around higher-yielding opportunities.
- Prioritise resilience first and review a 31 resilient stocks with low risk scores that screens for companies with sturdier fundamentals and more controlled risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com