
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
JFrog (FROG) Could Be 16% Undervalued On Its AI Security Push
JFrog (FROG) has just expanded its AppTrust and AI Security offerings with out of the box DORA compliance, repo level governance, and AI driven verification, sharpening the focus on automated software regulation.
Against this product news, JFrog’s share price has kept climbing, with a 1-day share price return of 4.25% and a 90-day share price return of 18.52%. Its year-to-date share price return of 61.66% and 1-year total shareholder return of 101.89% point to strong momentum rather than a brief spike.
Spot 55 AI infrastructure stocks that, like JFrog, are helping enterprises secure AI heavy software pipelines while riding strong momentum in critical infrastructure for machine learning workloads.After JFrog’s strong year-to-date run and sharp product push into AI security and compliance, the real fork in the road is simple: pay up now for that momentum, or wait and hope for a calmer entry point as the valuation detail comes into focus.
Most Popular Narrative: 14% Undervalued
JFrog’s most followed narrative puts fair value at $112 per share, compared with the latest close at $96.30. This frames the stock as requiring investors to weigh a richer implied future against near term execution risk.
Accelerating adoption of AI and machine learning across enterprises is driving increased demand for trusted, scalable artifact and AI model management; JFrog's position as the system of record for binaries and rapid traction as a model registry (including strategic wins with NVIDIA and AI industry leaders) supports strong expansion in data consumption, customer commitments, and revenue growth.
See why 16 investors see JFrog as 14% undervalued.
Result: Fair Value of $112 (UNDERVALUED)
Still, the bullish JFrog narrative could crack if large enterprise deals are delayed, or if competition in security and AI tooling starts to squeeze pricing power.
Find out about the key risks to this JFrog narrative.
Another View: JFrog Looks Expensive On Sales
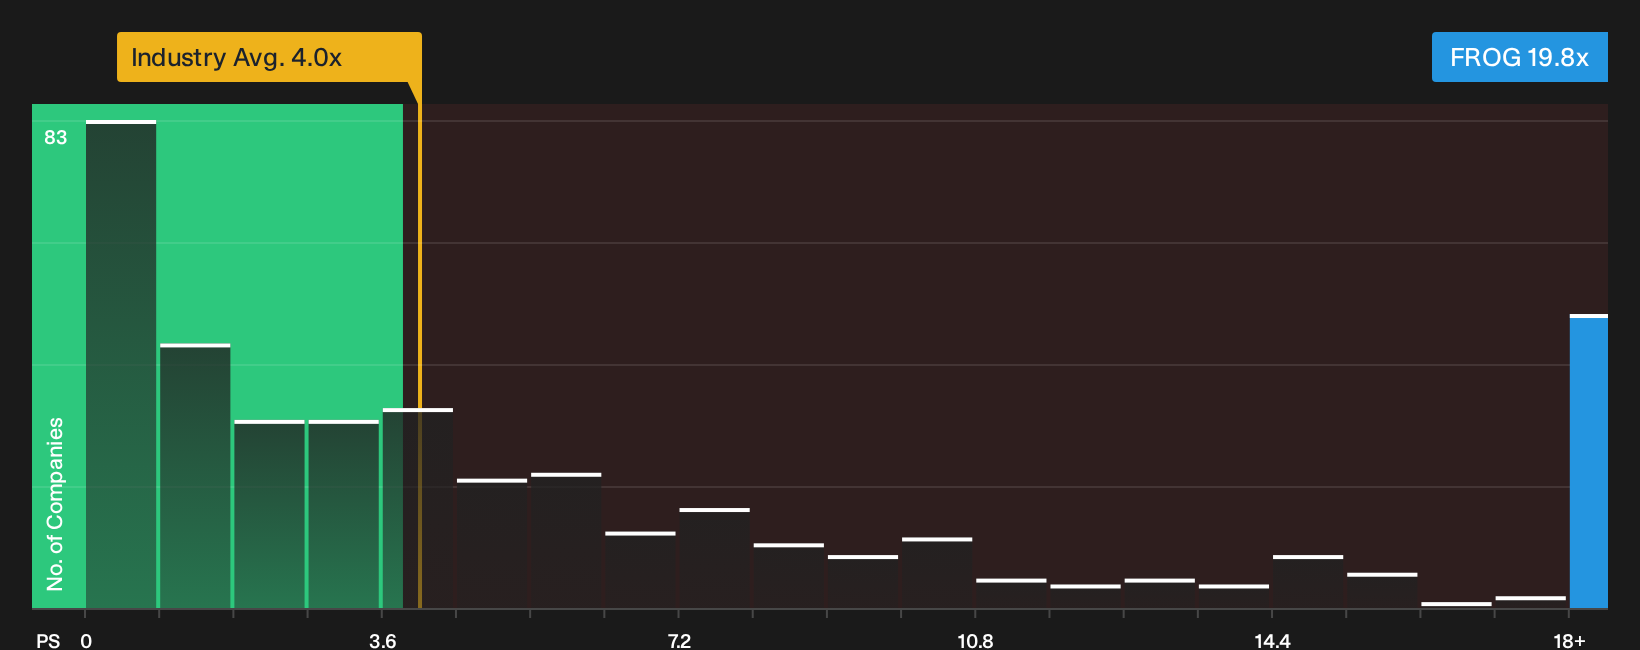
The fair value story around JFrog leans on future growth and AI security upside. A simple P/S check tells a very different story. The stock trades on a P/S ratio of 19.8x, compared with 3.9x for the wider US Software group and 6.1x for closer peers.
Our fair ratio estimate is 7.8x. Current pricing sits well above both industry and peers, as well as where the multiple could move toward if enthusiasm fades. This raises the question: is this a high quality opportunity investors are willing to pay up for, or is execution risk too high at this valuation gap?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around JFrog can either sharpen your thinking or paralyze you, so act quickly on the available data and weigh both sides through 1 key reward and 2 important warning signs
Looking for more investment ideas beyond JFrog?
You have seen how quickly a focused theme like AI security can reshape JFrog’s risk and reward profile. Do not stop here when the broader opportunity set is wide.
- Target potential mispricing by scanning a curated 33 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying strength.
- Build a steadier income stream by reviewing a hand picked set of 7 dividend fortresses designed for investors who want yields with balance sheet support.
- Strengthen your downside protection by filtering for a 31 resilient stocks with low risk scores that prioritise resilient finances and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com