
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does New CTO Appointment Change The Bull Case For Toro Stock (TTC)?
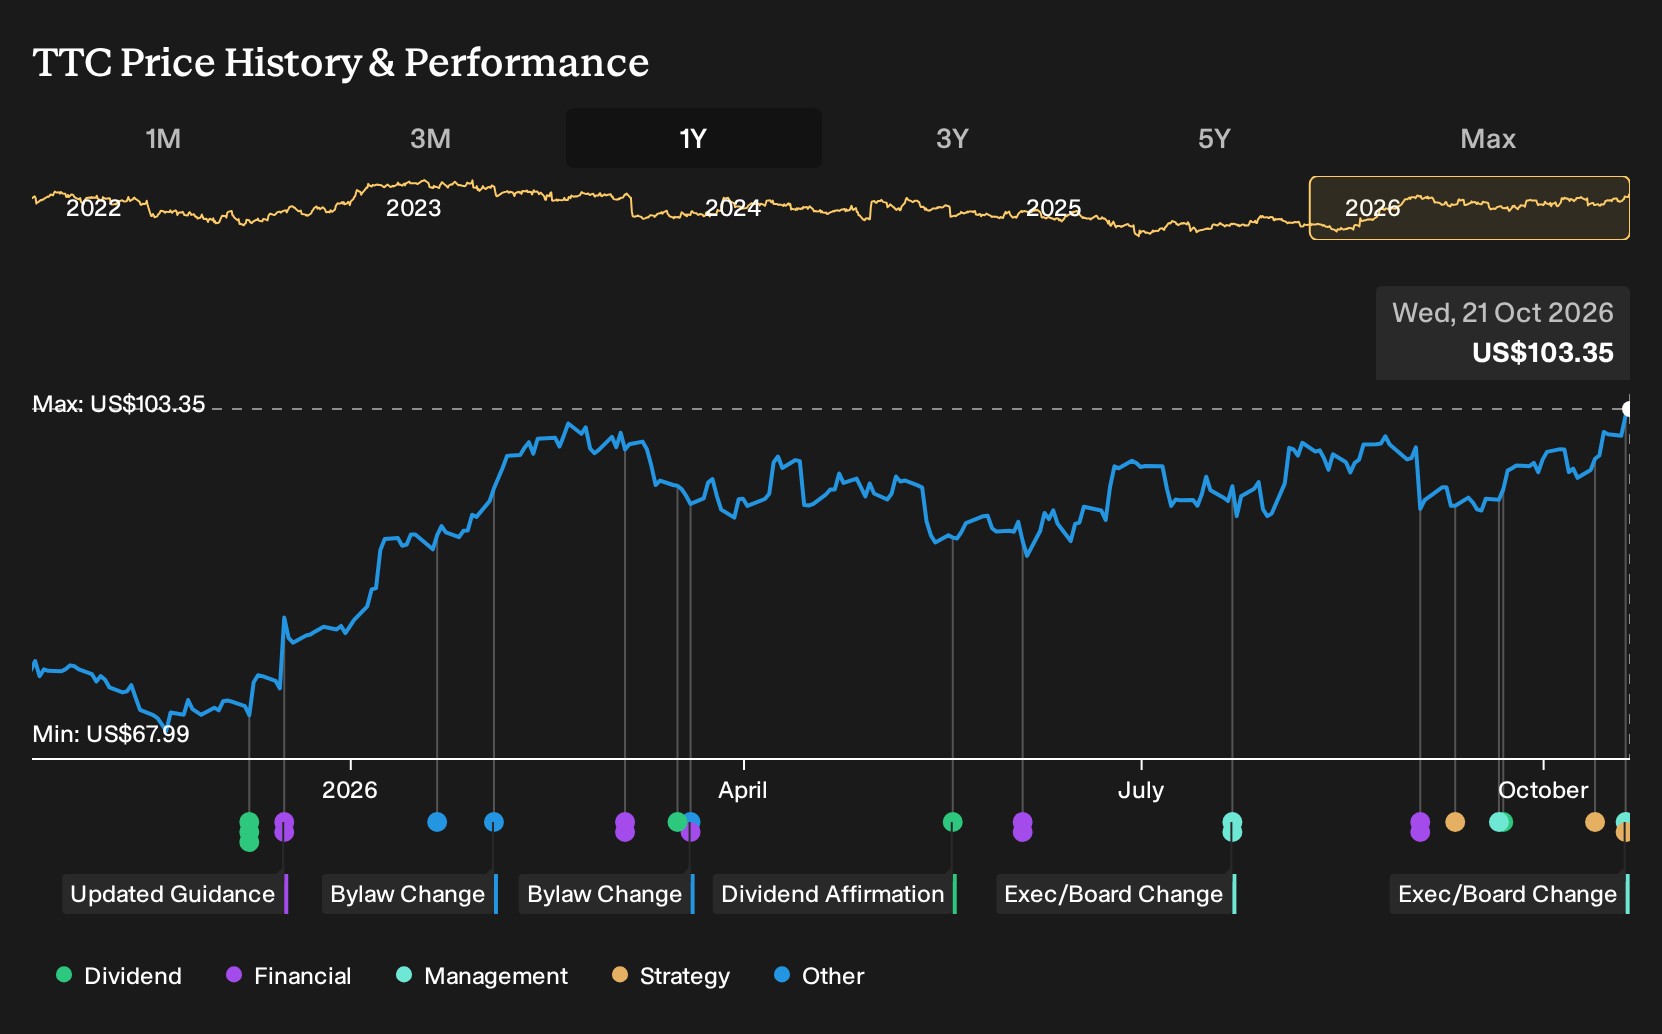
- The Toro Company recently appointed Neal M. Lackritz as chief technology officer and introduced the OneFleet fleet benefits program alongside the HAVEN AM75 autonomous mower and a refreshed TimeCutter range.
- Toro is pairing a new technology leadership role with autonomous and connected product launches that speak directly to cost, productivity and fleet efficiency priorities across its customer base.
- We will now look at how Toro's investment narrative could be affected by the new chief technology officer appointment.
Scan for more equipment and automation plays that could sit alongside Toro in a portfolio by reviewing the 93 robotics and automation stocks tied to robotics, autonomy and next-gen machinery.
Toro Investment Narrative Recap
For a shareholder in Toro, the core belief is that higher value turf, irrigation and underground construction equipment can keep pulling more profit out of fairly modest top line growth. The short term swing factor is whether AMP productivity gains and recent mix shift continue to support margins after a five year stretch where returns had previously softened.
The biggest risk is that efficiency gains plateau while the business still carries meaningful debt and trades on a P/E above machinery peers. The new CTO, Neal Lackritz, mainly affects the medium term technology roadmap rather than near term earnings, so the immediate financial impact of this hire appears limited.
The OneFleet launch is the clearest operational bridge between the CTO news and current catalysts. By tying multiple Toro brands into a shared fleet benefits program, the group is aiming to capture more wallet share from existing professional and rental relationships and to convert channel normalization into higher shipment volumes.
For you as an investor, the focus is on execution. If OneFleet helps Ditch Witch, BOSS, Ventrac and other lines win more orders without eroding pricing power, it may support the AMP margin story and strengthen cash generation. If customers are less responsive, the risk around future revenue assumptions and valuation multiples remains a key consideration.
Toro's narrative projects US$5.2b revenue and US$554.9 million earnings by 2029. This assumes 3.4% yearly revenue growth and an earnings increase of about US$191.6 million from US$363.3 million today.
Uncover why Toro's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bearish twist on Toro centers on whether customers really pay up for autonomy and connected gear. The lowest analysts were already cautious, penciling in US$5.2b revenue and US$546.1 million earnings by 2029 with a lower 20.6x P/E. Those views were set before this CTO hire and the OneFleet launch, so opinions may evolve over time.
Explore 2 other Toro fair value estimates, including one that suggests it could be worth just $111.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toro research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Toro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toro's overall financial health at a glance.
Looking For More Ideas Beyond Toro?
If you want to see how Toro stacks up against other opportunities, broaden your watchlist with a few focused screens that surface different types of companies based on quality, value and resilience.
- For investors who want strong fundamentals and minimal balance sheet stress, start with a list of solid balance sheet and fundamentals (25 results) that can sit alongside more cyclical holdings.
- If your priority is to find potential value setups, scan a 33 high quality undervalued stocks that combine solid cash flows with what may be discounted market expectations.
- Income focused portfolios might benefit from adding a 7 dividend fortresses that aim to pair yield with staying power through different cycles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com