
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Murphy Oil Buyers Were Betting On
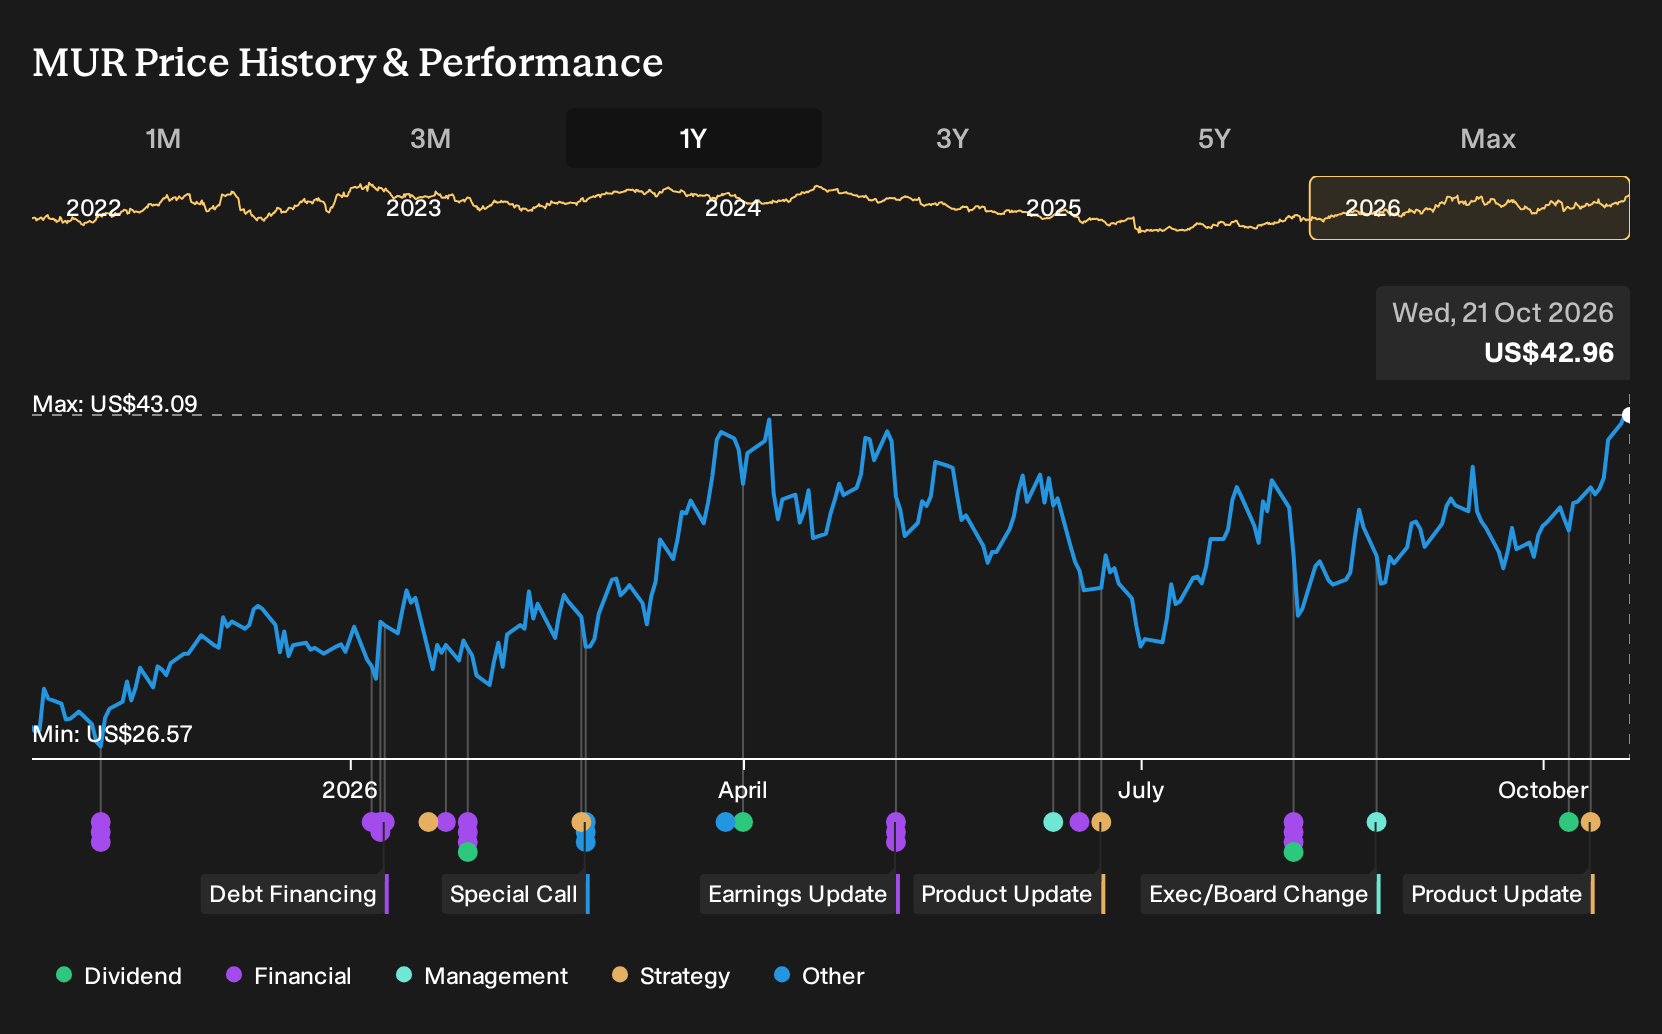
If you had been weighing Murphy Oil back on 21 October 2025, the debate was clear, with bulls pointing to deepwater upside and LNG-linked gas exposure while bears focused on net-zero policies and concentrated, aging assets. For Murphy Oil shareholders, the return over the past year was 63.4%, including dividends. The result is now on the table, but the real question is whether those early buyers were correctly sizing exploration potential against transition and regulatory risks.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Murphy Oil. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing On Murphy Oil
The shares cost US$27.3 at the start of the period. Anyone looking at Murphy Oil then had to choose between two very different but reasonable stories about where the business might go next.
The bullish narrative pinned fair value at US$40, which is 47% above the start price, based on deepwater exploration such as Vietnam and Côte d'Ivoire, and the idea that LNG-linked gas from Tupper Montney could become a long-term cash engine.
The bearish view set fair value at US$23, which is 16% below the start price, warning that net-zero policies and slower diversification could weaken future oil demand and leave Murphy Oil more exposed to regulatory and margin pressure.
What The Murphy Oil Results Put To The Test
The clearest development for Murphy Oil was operational. New discoveries and production start-ups in Côte d'Ivoire, Vietnam and the Gulf of Mexico added fresh barrels, which supported the bullish case that deepwater and international projects could expand the reserve base. At the same time, higher 2026 capital spending of US$1.55b and sector-driven share pullbacks kept the cautious view on capital intensity and volatility alive. The evidence cut both ways.
The real hinge here was not opinion but delivery on cash-generating projects. For a different stock with big exploration promises, it can be useful to track whether exploration headlines convert into higher revenue, rising net profit and healthier net margins in reported numbers, rather than just more spending.
What Murphy Oil's Price Already Assumes Today
Murphy Oil now trades at US$42.96, well above where the earlier debate started. The selected Narrative's Fair Value sits below the current price, framing that gap as a question about how much exploration and development success is already built into today's tag.
The Narrative turns on whether capital heavy offshore and Eagle Ford plans truly convert into lasting free cash flow. A buyer now is effectively assuming these projects earn through their cost of capital. This raises the question of how exposure to longer appraisal timelines and higher spending may pressure that expectation if conditions shift.
"Key Takeaways Bearish analysts expect Murphy Oil to commit to a higher capital spending profile on offshore growth and appraisal that dilutes returns if exploration outcomes and project execution do not validate the added risk. The main thing that has to go right is that Murphy Oil converts its capital intensive Bubale and Vietnam offshore programs and the extra Eagle Ford spend into durable production and free cash flow without eroding balance sheet strength or its long running dividend."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 30% below our estimate - sells full-stack accelerated computing platforms that power expanding AI factory buildouts.
- Company 2 - 33% below our estimate - wins integrated subsea projects that shorten brownfield tieback timelines and deepen services work.
- Company 3 - 40% below our estimate - advises on complex technical failures where rising AI use drives demand for analysis.
Three companies from the same screener. Open all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com