
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Toyo Suisan Kaisha (TSE:2875) Undervalued As Fresh DCF Work Sparks A Reassessment?
Renewed attention on Toyo Suisan Kaisha (TSE:2875) arose from fresh DCF work suggesting the shares trade at a material discount to intrinsic value, prompting investors to recheck assumptions on growth, profitability, and earnings power.
Toyo Suisan Kaisha’s recent 12.46% 1 month share price return has picked up pace after a quieter stretch, and that short term momentum comes on top of a 6.97% 1 year total shareholder return and a very strong 5 year total shareholder return of 161.17%.
Compare Toyo Suisan Kaisha’s valuation story with other potential opportunities by scanning our hand picked 14 high quality undervalued stocks for ideas grounded in cash flows and balance sheet strength.
Toyo Suisan Kaisha has produced strong long term returns and runs a broad food platform, yet the fresh DCF work points to a sizeable valuation gap. Are recent buyers paying a fair price or still getting a bargain?
Preferred P/E of 14.5x: Is it justified?
Toyo Suisan Kaisha trades on a P/E of 14.5x while the SWS DCF model points to a fair value of ¥16,073.56 against a last close of ¥10,950. That combination points to a stock priced below both its earnings based fair ratio and its modelled future cash flows.
The P/E ratio compares the current share price to earnings per share, so it reflects what the market is willing to pay for each unit of profit. For a food manufacturer with established brands and a long operating history, earnings based benchmarks often matter more to investors than rapid top line expansion.
Here the P/E of 14.5x screens as "good value" against both peers at 20.9x and the wider JP Food industry at 16.4x, which suggests investors are paying less for each yen of profit than the sector average. Against an estimated fair P/E of 19.1x, the current multiple also sits below a level the market could move towards if sentiment or earnings quality perceptions converge with that fair ratio.
Explore the SWS fair ratio for Toyo Suisan Kaisha.
Result: Price-to-Earnings of 14.5x (UNDERVALUED)
Still, the Toyo Suisan Kaisha story can be knocked off course if overseas instant noodles slow or if input costs pressure earnings and compress that P/E gap.
Find out about the key risks to this Toyo Suisan Kaisha narrative.
Another View: DCF Paints A Bigger Gap
The P/E makes Toyo Suisan Kaisha look cheap, yet the SWS DCF model goes further by estimating fair value at ¥16,073.56 against a market price of ¥10,950, implying the shares trade about 31.9% below that cash flow based estimate. Which signal would you trust if they stay this far apart?
Look into how the SWS DCF model arrives at its fair value.
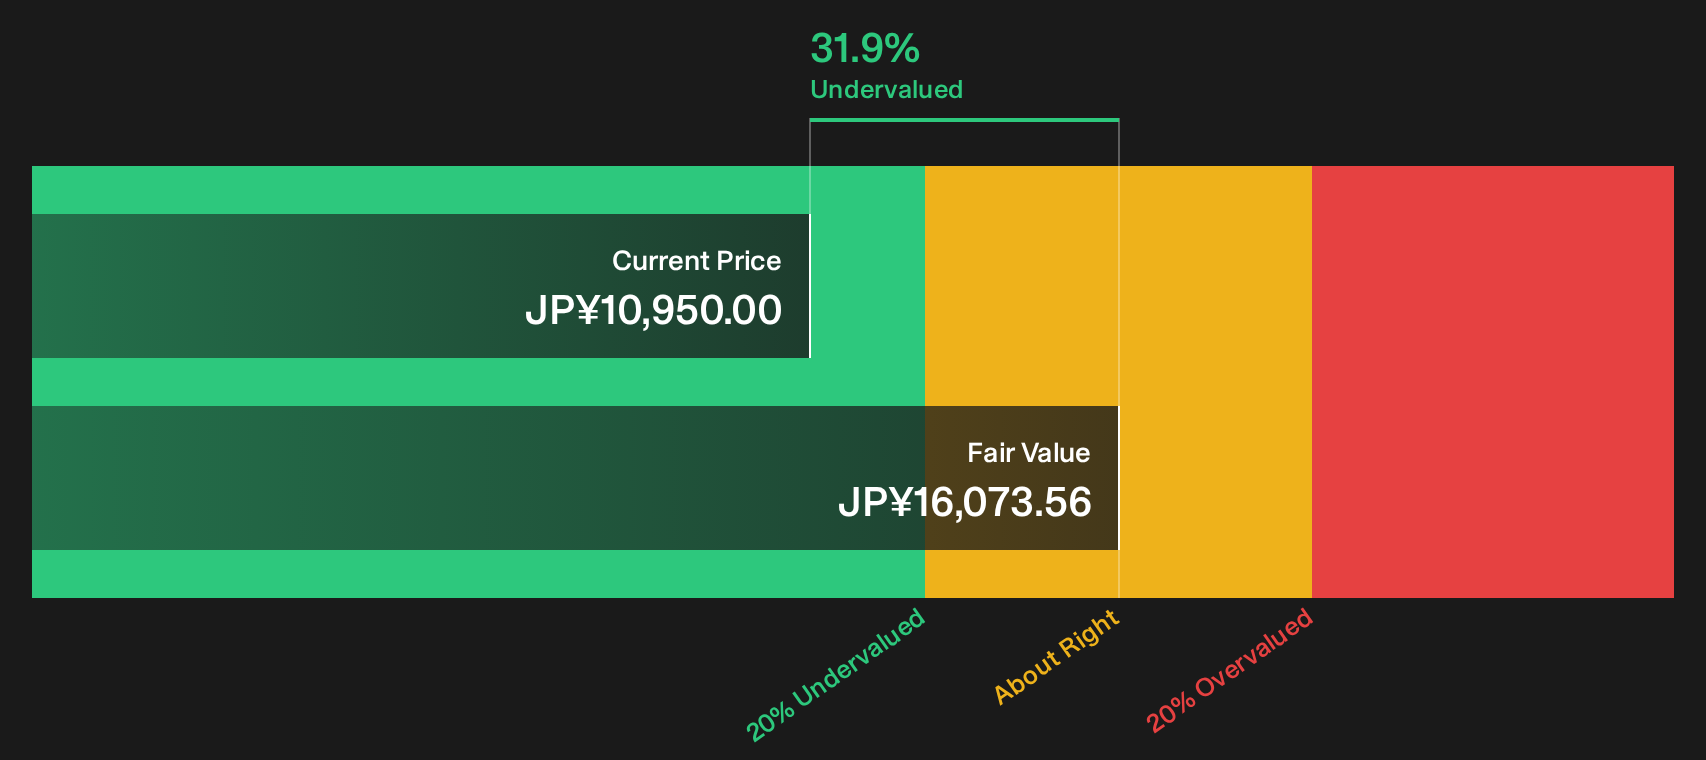
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toyo Suisan Kaisha for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
See something encouraging in the Toyo Suisan Kaisha story, or still on the fence? Act while the data is fresh and weigh the upside for yourself by checking the 5 key rewards.
Looking for more Toyo Suisan Kaisha sized opportunities?
If Toyo Suisan Kaisha has sharpened your focus on price versus value, broaden your watchlist now with a few targeted sets of ideas built from the Simply Wall St screener.
- Hunt for overlooked upside and scan a curated pool of potential bargains using our 73 high quality undiscovered gems.
- Target resilience first and filter for companies where balance sheets and fundamentals do the heavy lifting with this focused list of solid balance sheet and fundamentals (22 results).
- Prioritise staying power and sort for businesses with relatively lower quantified risk profiles through the dedicated 21 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com