
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Applied Materials (AMAT) Stock Could Be 46% Overvalued Despite Its $5 Billion EPIC Center
Applied Materials has powered through a multi year upswing while also pouring billions into new facilities for AI focused chip equipment, which leaves a basic question for you as an investor. Is the current share price in line with the cash flows the business can realistically produce over time, or has sentiment moved ahead of the underlying economics?
- Over the past 5 years the stock has delivered a return of 222.5%, which puts a lot of expectation on the long term cash flows that need to support that kind of performance.
- The new US$5b EPIC Center and deeper AI related partnerships can reshape Applied Materials' future cash generation by affecting both growth potential and the timing and scale of capital spending.
- What if you looked at Applied Materials through its earnings instead? See why Applied Materials's 35.0x P/E tells a different valuation story.
The issue now is whether the current market price is justified by the cash flows implied by a Discounted Cash Flow (DCF) view of Applied Materials.
If you want to test the same cash flow question that Applied Materials now faces across a wider AI and chip related universe, scan the 55 AI infrastructure stocks.
Does Applied Materials Look Pricey on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash that Applied Materials can return to shareholders over time. Latest twelve month free cash flow sits around $6.3b, and the projections assume that this cash generation grows from that base rather than shrinking.
What really jumps out is how much of the DCF value comes from sizeable expected free cash flows in the early 2030s, even though the current share price is $408.94 and the projections put Applied Materials' estimated intrinsic value substantially below the current share price. The new US$5b EPIC Center and AI focused partnerships help explain why the market is willing to pay up for that future story despite the model pointing lower based on cash flows alone. Find out what Applied Materials could be worth using our Discounted Cash Flow (DCF) estimate.
The Applied Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Applied Materials valuation puzzle leaves off, by spelling out which assumptions about future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today, and they sit on the platform's Community page. Rather than lean on a single multiple or DCF output, each scenario lays out the key drivers behind its view of fair value so you can track those inputs against actual results as they are reported.
One of the top community narratives on Applied Materials: 36% undervalued
"The main thing that has to go right is that Applied Materials continues to translate AI related demand, EPIC partnerships and expanded manufacturing capacity into growth in higher value segments…"
Discover why this Narrative puts Applied Materials at 36% undervalued.
One more Applied Materials check that belongs beside the DCF work
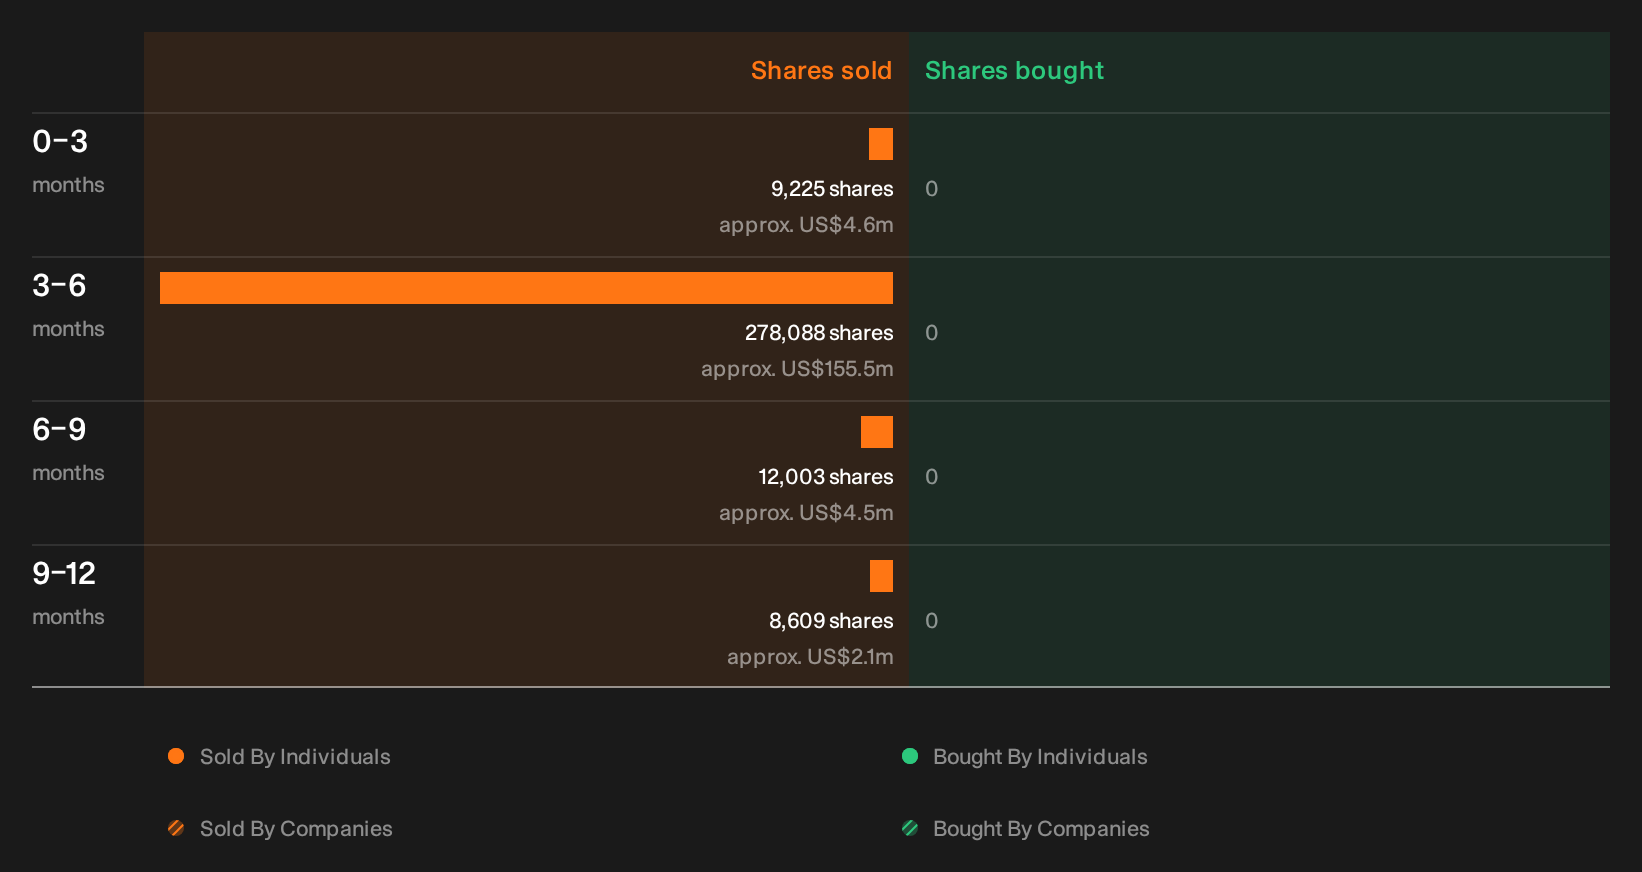
Price, cash flows and growth stories tell only part of Applied Materials' picture, because recent activity from people inside the business has been flagged and the specific sellers, sizes and possible signals are still for you to unpack. See the recent insider selling flagged for Applied Materials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com