
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Discover 3 Leading Growth Companies With Strong Insider Ownership
The United States market remained flat over the last week but has seen a 13% increase over the past year, with earnings forecasted to grow by 17% annually. In such an environment, identifying growth companies with strong insider ownership can be crucial as it often signals confidence in the company's future prospects and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 70.2% |
| Standard Nuclear (STDN) | 20.6% | 64.2% |
| Sable Offshore (SOC) | 11.3% | 71.3% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 23.1% | 22.3% |
| Karman Holdings (KRMN) | 13.6% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 33.1% |
| Dave (DAVE) | 16.6% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 58.3% |
Let's uncover some gems from our specialized screener.
Paysign (PAYS)
Simply Wall St Growth Rating: ★★★★☆☆
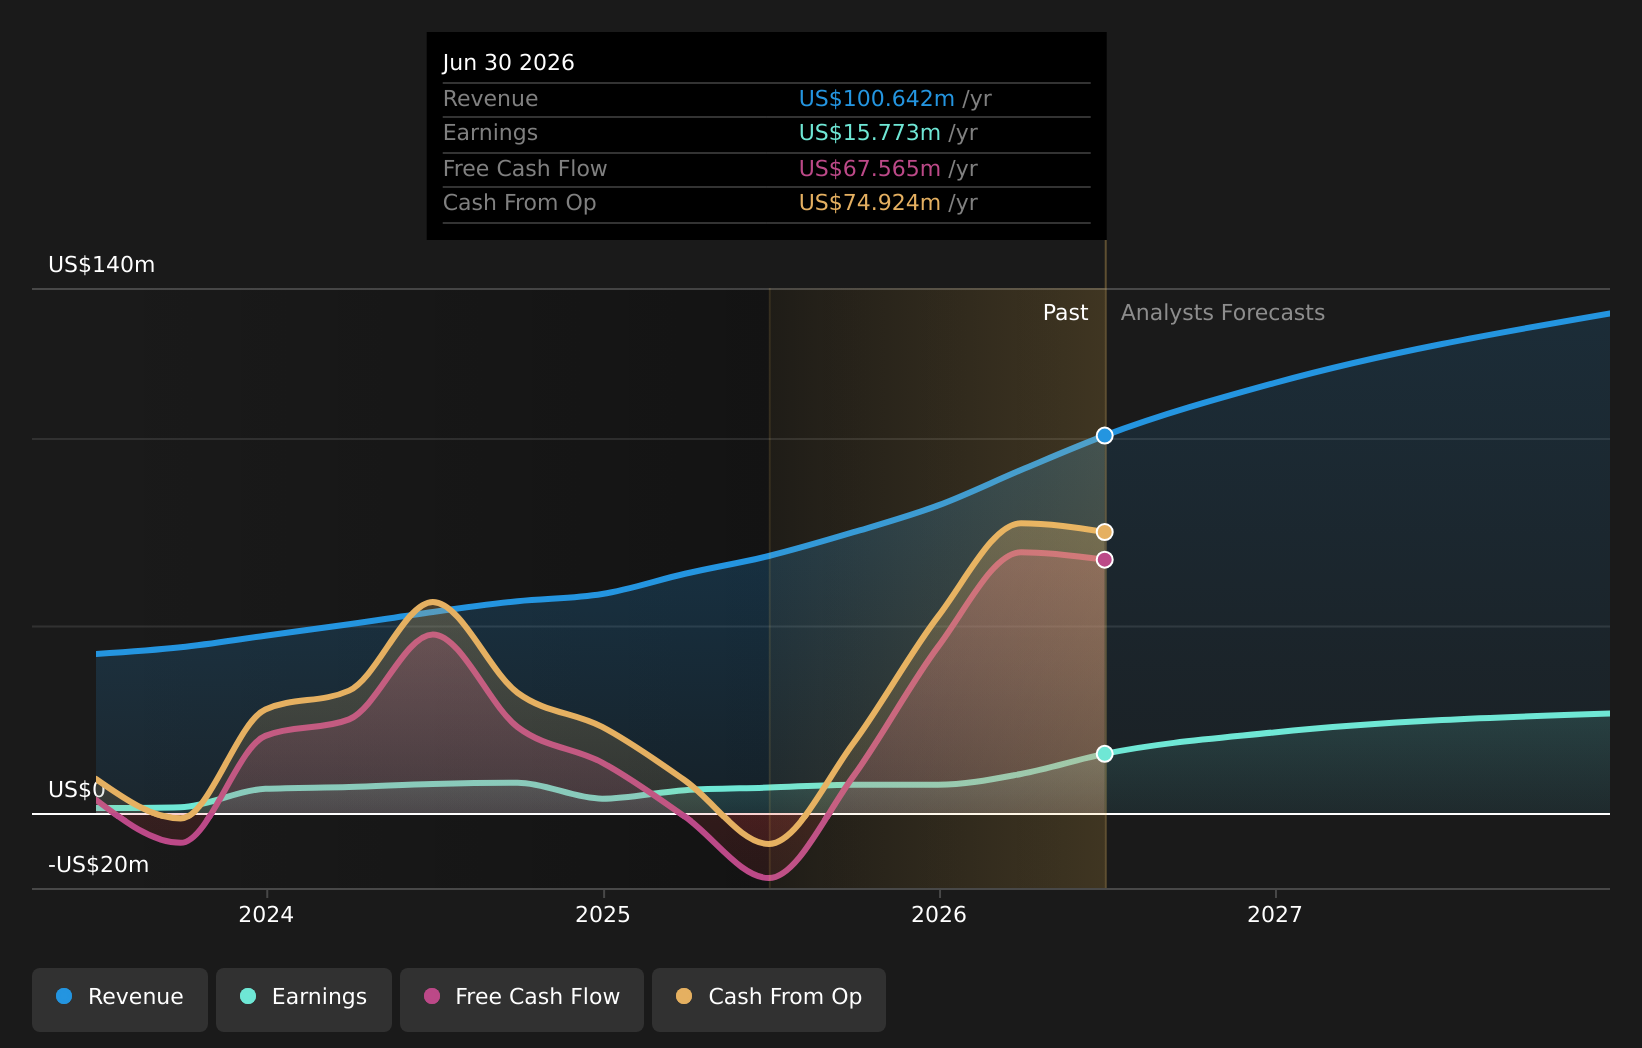
Overview: Paysign, Inc. operates in the United States offering prepaid card programs, patient affordability solutions, digital banking services, life science software technology, and integrated payment processing with a market cap of $858.79 million.
Operations: Paysign's revenue is primarily derived from its vertically integrated provider of prepaid card products and processing services, totaling $100.64 million.
Insider Ownership: 30.9%
Paysign demonstrates strong growth potential with earnings forecasted to grow significantly at 28.1% annually, outpacing the US market's 16.9%. Despite recent insider selling, substantial buying indicates confidence in future prospects. The company raised its full-year 2026 guidance, expecting revenue between US$114 million and US$117 million, driven by improved plasma business trends and patient affordability solutions resonating well with pharmaceutical companies. Recent quarterly results show a marked improvement in profitability and core margin metrics compared to last year.
- Delve into the full analysis future growth report here for a deeper understanding of Paysign.
- According our valuation report, there's an indication that Paysign's share price might be on the expensive side.
Pattern Group (PTRN)
Simply Wall St Growth Rating: ★★★★★☆
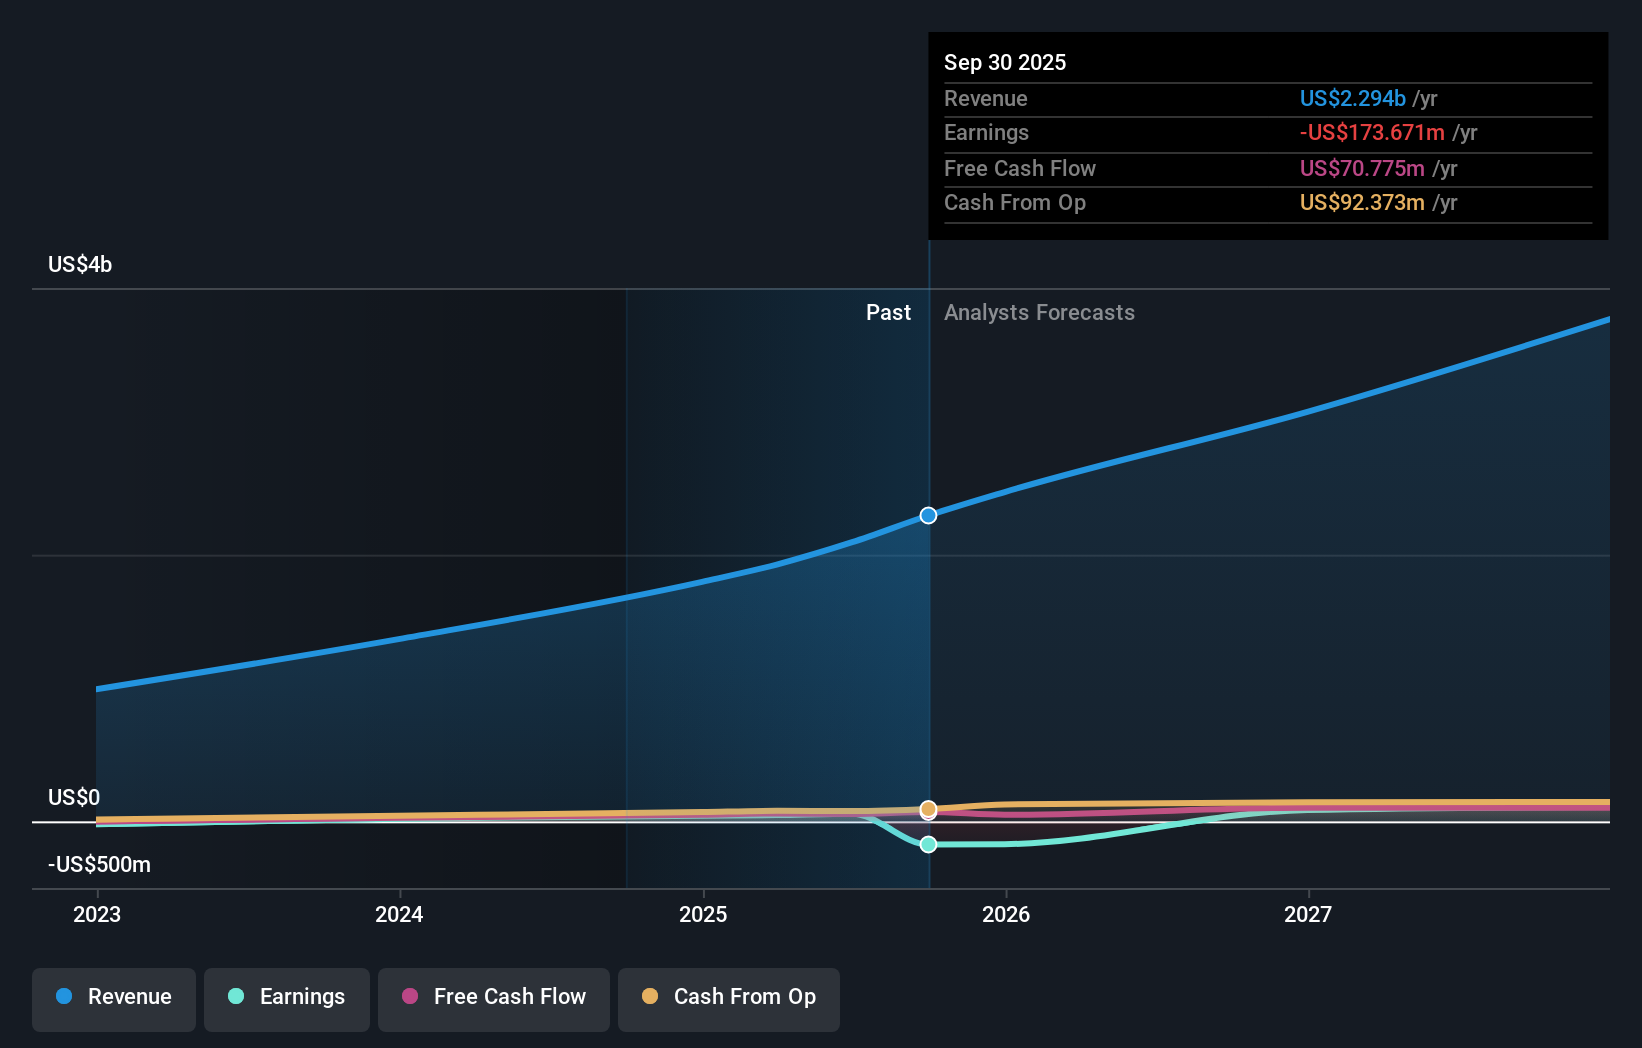
Overview: Pattern Group Inc. is an e-commerce accelerator that leverages proprietary technology and on-demand expertise to assist consumer brands in navigating e-commerce marketplaces both in the United States and internationally, with a market cap of approximately $3.22 billion.
Operations: The company's revenue primarily comes from its online retailers segment, which generated $3.01 billion.
Insider Ownership: 12.5%
Pattern Group is experiencing robust growth, with revenue expected to increase by 21.7% annually, surpassing the US market average. The company raised its 2026 earnings guidance, projecting revenues between US$3.42 billion and US$3.46 billion, reflecting a 37% to 38% year-over-year growth. Recent integration with ChatGPT expands its advertising platform's reach, enhancing brand partner engagement across emerging AI-native channels and established platforms like Meta and Google. Despite low forecasted return on equity, analysts anticipate significant stock price appreciation of 54.7%.
- Take a closer look at Pattern Group's potential here in our earnings growth report.
- In light of our recent valuation report, it seems possible that Pattern Group is trading behind its estimated value.
Upstart Holdings (UPST)
Simply Wall St Growth Rating: ★★★★★★
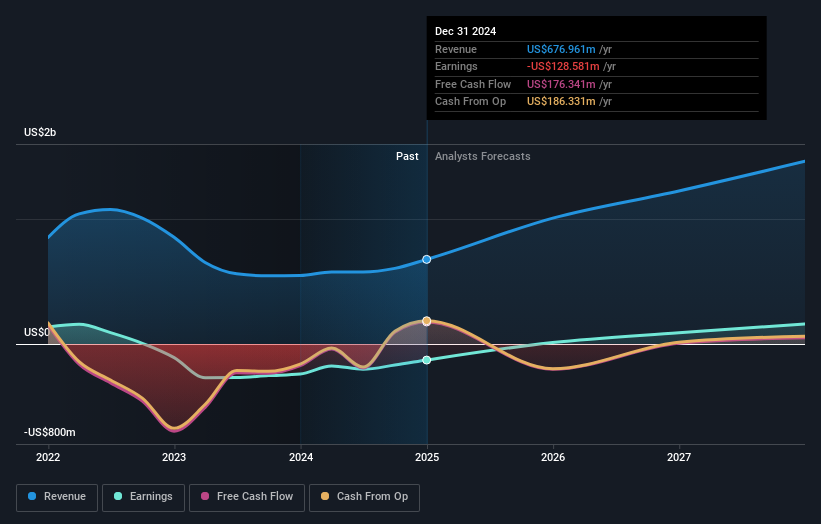
Overview: Upstart Holdings, Inc. operates a cloud-based AI lending platform in the United States and has a market cap of approximately $2.30 billion.
Operations: The company generates revenue primarily from its unsecured lending segment, which amounted to $1.10 billion.
Insider Ownership: 14.0%
Upstart Holdings is positioned for substantial growth, with earnings projected to rise significantly at 70.18% annually, outpacing the US market. Recent partnerships with credit unions and a forward-flow agreement with Castlelake underscore its expanding lending platform. The company's revenue is forecasted to grow by 21.8% per year, exceeding market averages. Insider confidence remains strong, evidenced by substantial insider buying over the past three months, while no significant insider selling occurred during this period.
- Dive into the specifics of Upstart Holdings here with our thorough growth forecast report.
- Insights from our recent valuation report point to the potential overvaluation of Upstart Holdings shares in the market.
Where To Now?
- Discover the full array of 185 Fast Growing US Companies With High Insider Ownership right here.
- Looking For Alternative Opportunities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com