
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SAP (XTRA:SAP) Beats On Cloud And Guidance, Is The Upside Already Priced In?
SAP (XTRA:SAP) just posted third quarter results that beat expectations, with revenue of €10,270 million and net income of €2,249 million, and raised its full year outlook toward the upper end of prior guidance.
Investors have responded quickly to SAP's earnings beat and higher guidance, with a 1-day share price return of 3.52% and a 90-day share price return of 62.60%. This points to strong positive momentum, even though the 1-year total shareholder return declined 10.41% while the 5-year total shareholder return reached 81.42%.
Compare SAP's AI and cloud momentum with a curated group of peers riding similar themes using the 55 AI infrastructure stocks.
SAP shares have surged on the earnings surprise and higher guidance, yet the stock still trades below both analyst targets and some intrinsic value estimates. So where does fair value actually land in that gap?
Most Popular Narrative: 30% Overvalued
SAP last closed at €208.65, while the most followed narrative anchors fair value closer to €160. That gap frames a debate around whether strong cloud and AI demand can outweigh concerns about profitability and capital allocation.
The plan to release close to 50 AI assistants by the end of Q3 2026 and more than 400 Autonomous Suite agents by year end, along with additional ERP migration assistants, requires sustained spending on model inference, productization and customer support that is not yet matched by recognized revenue. As a result, the rollout of this next engagement layer could extend the period of pressure on cloud gross margin and delay any improvement in earnings.
See why 19 investors see SAP as 30% overvalued.
Under this storyline, a discount rate of 6.8% and earnings assumptions out to 2029 are used to arrive at a fair value of €160 per share, which sits well below both the current market price and the analyst consensus target of about €209.81. That signals a view that the recent share price strength already bakes in ambitious outcomes on cloud migrations, AI adoption and margin resilience, while the narrative itself focuses on whether SAP can convert its sizeable contracted backlog into earnings growth without eroding profitability.
Result: Fair Value of €160 (OVERVALUED)
Still, if SAP turns heavy AI usage in major deals into broad production deployments, and customers accept richer contracts, this bearish case could unwind quickly.
Find out about the key risks to this SAP narrative.
Another View: SAP Through The Cash Flow Lens
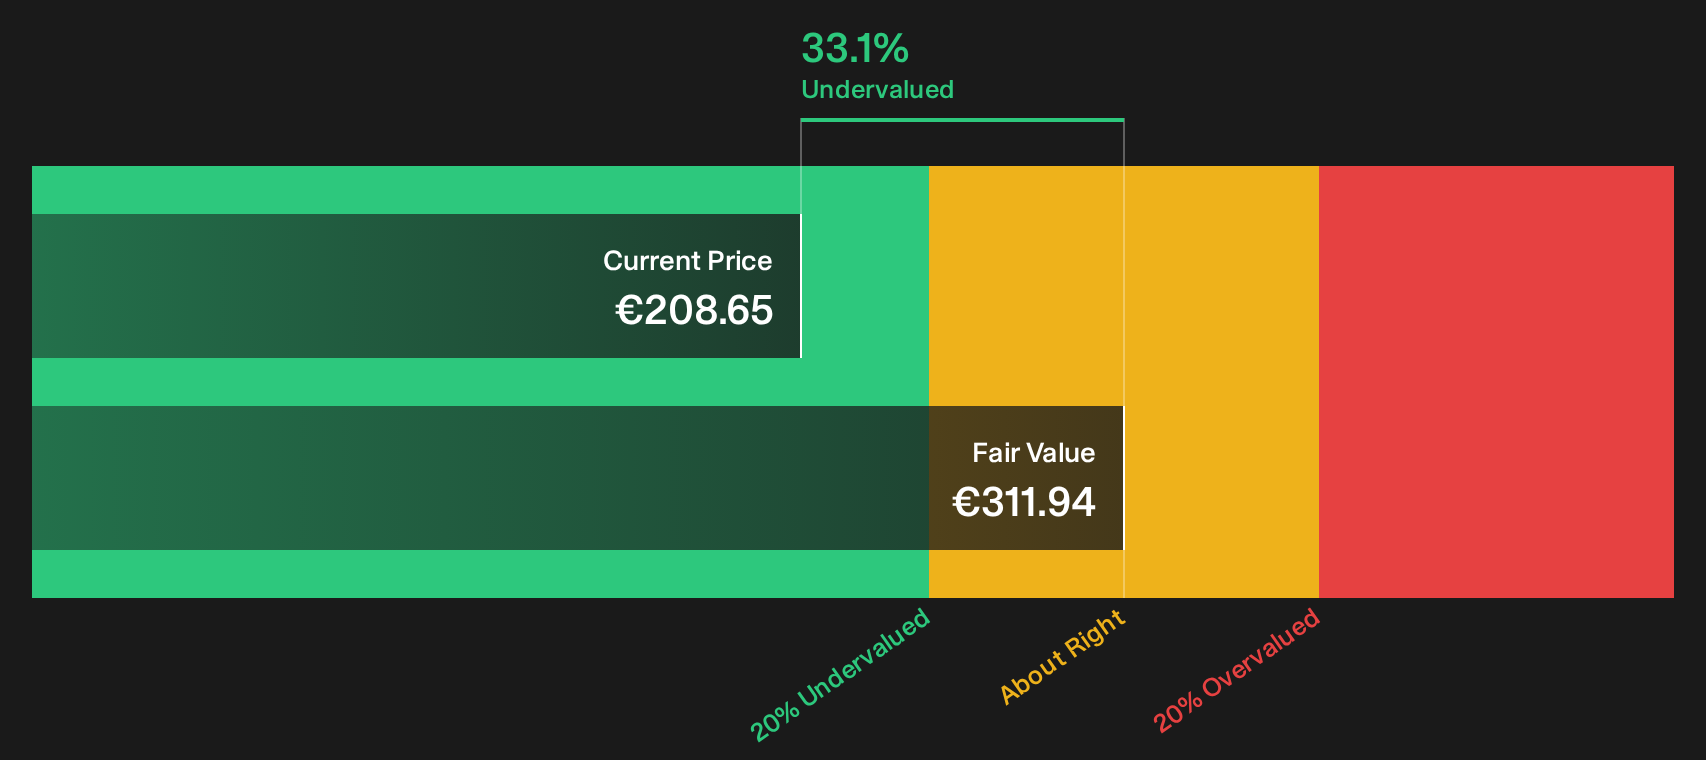
The bearish narrative pins SAP at a fair value of €160, yet our DCF model points in the opposite direction. On that framework, the shares trade about 33% below an estimated future cash flow value of €311.94, which raises a simple question: Is the market overpaying for earnings, or underpricing cash generation?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
With sentiment this split around SAP, the fastest way to cut through the noise is to inspect the underlying data yourself. To see what the optimism is based on, review the 3 key rewards.
Looking for more SAP investment ideas?
If SAP has sharpened your focus, do not stop at one stock. Broaden your watchlist now so fresh opportunities do not slip past you.
- Target quality at a discount and scan a curated set of potential bargains screened on fundamentals with the 190 high quality undervalued stocks.
- Strengthen your core holdings by filtering for balance sheets that look built to endure using the list of solid balance sheet and fundamentals (203 results).
- Get ahead of the crowd and hunt for underfollowed opportunities that still boast solid numbers through the 618 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com