
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oasis Activist Stake Could Be A Catalyst For M3 Stock (TSE:2413)
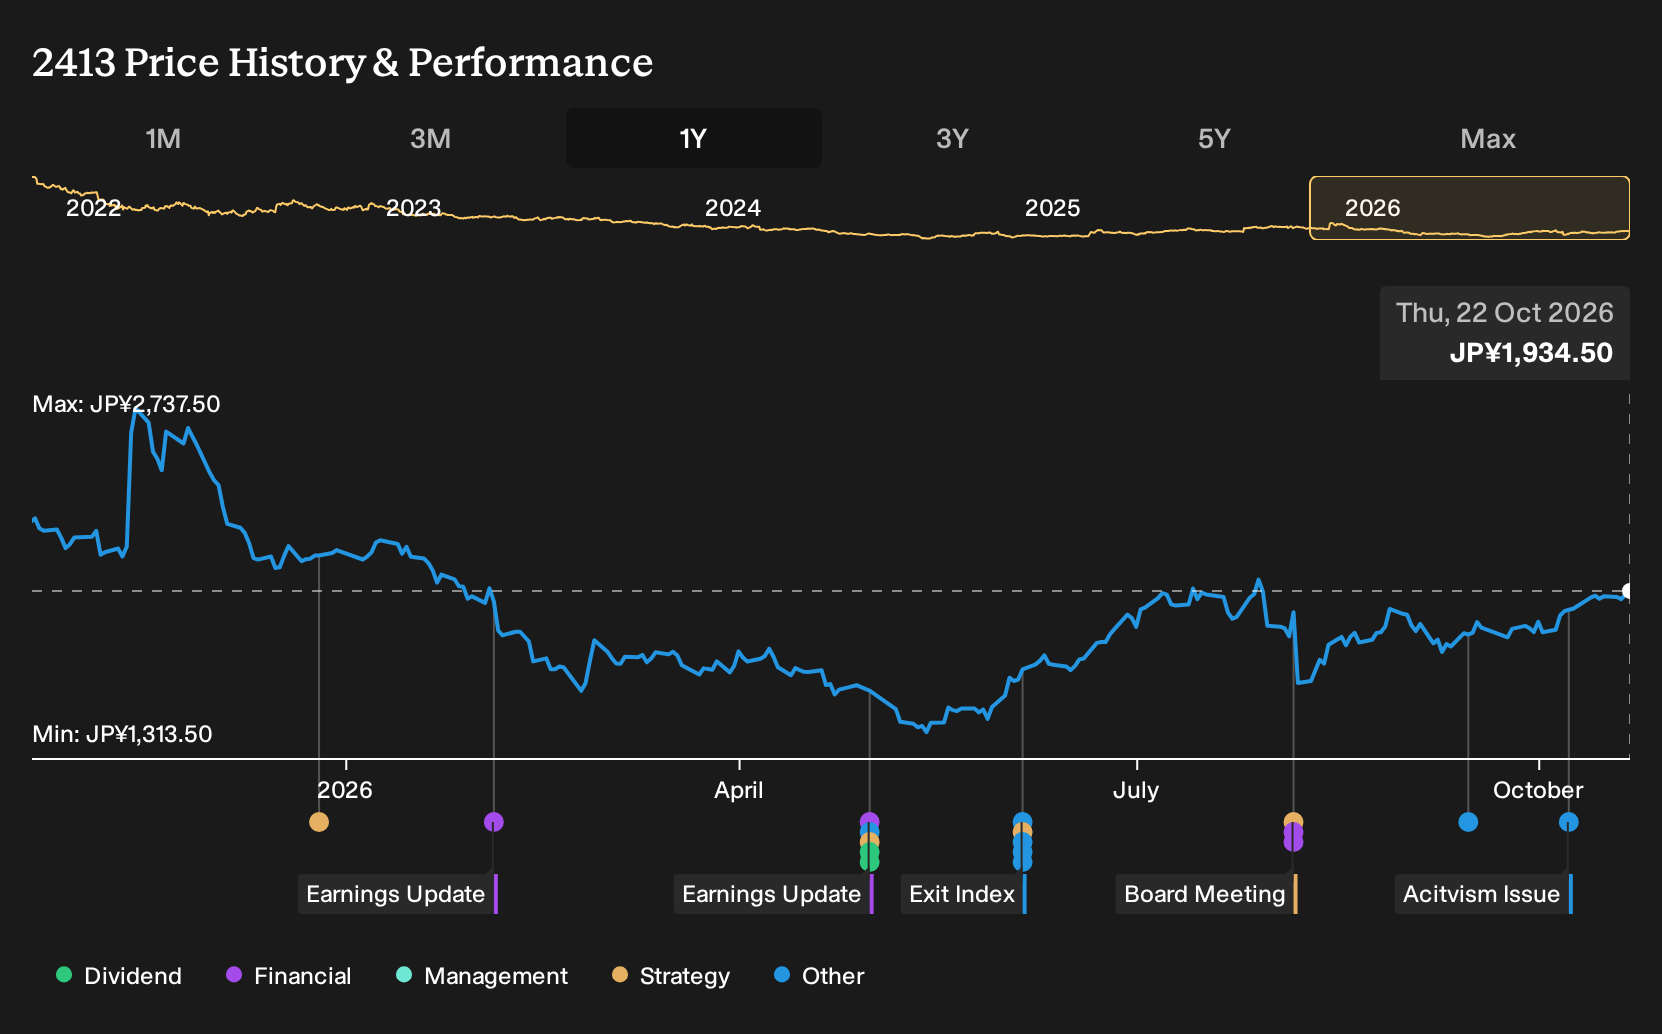
- Oasis Management disclosed that by October 1, 2026 it had raised its stake in M3 to 9.48% and is engaging management on board composition, dividend policy and capital allocation.
- The activist focus on potential director changes and capital policy puts M3’s governance structure and cash use under closer scrutiny for long term shareholders.
- The following discussion will explore how M3’s broader investment narrative could shift as Oasis pushes for board and capital policy changes.
What Is M3's Investment Narrative?
M3 is primarily an execution story. The core bet is that its internet platforms for doctors, pharma clients and healthcare jobs can keep attracting usage and monetisation while staying relatively asset light. Earnings and revenue are both forecast to grow at around low double digit rates, with net income of ¥46,334.0m supported by multiple service lines rather than a single product. That business mix, plus relatively low physical capital needs, is what you need to be comfortable owning here.
In the short term, the bigger swing factors look operational and pricing related, not just the share price, which has been volatile and is down about 11% over 1 year. M3 trades on a P/E of 27.9x, which is higher than the Asian Healthcare Services average and peer multiples, so execution missteps could matter. Oasis Management pushing on dividends, capital policy and directors plugs directly into that, because any change in payout or governance could affect how investors weigh that valuation against forecast growth.
Even so, one piece of the M3 story tends to get glossed over until you look closely at ...
There's only one way to know the right time to buy, sell or hold M3. Head to Simply Wall St's company report for the latest analysis of M3's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your M3 research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for M3. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M3's overall financial health at a glance.
Looking For More Ideas Beyond M3?
If this Oasis driven story has sharpened how you think about governance and capital allocation at M3, it can be useful to scan for other companies that already line up with the traits you care about. The Simply Wall St Screener lets you filter the market through the same lens, so you can spot businesses that fit your own risk, return and balance sheet priorities.
Here are a few angles you can use right now:
- Start with financial resilience and focus on companies that pair sturdy cash positions with measured leverage by reviewing the list of solid balance sheet and fundamentals (22 results).
- If value is the priority, concentrate on stocks that combine quality fundamentals with pricing that screens as potentially attractive using the 14 high quality undervalued stocks.
- For investors who care most about stability and capital protection, narrow the field to companies that score well on lower risk metrics via the 21 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com