
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Red Violet (RDVT) Fully Valued On Its Fortune Ranking Debut?
Why Fortune’s Ranking Put Red Violet In Focus
Red Violet (RDVT) moved onto more investor radars after debuting at No. 43 on Fortune's 2026 list of the 100 Fastest-Growing Companies, a milestone tied to its multi-year revenue, profit, and stock return record.
Recent trading suggests that momentum in Red Violet is building, with the share price at US$78.56 and a 90 day share price return of 31.88%. The 3 year total shareholder return of 331.21% highlights how powerful the longer term move has been.
Attention around the Fortune ranking comes on top of a 52.93% year to date share price return and a 49.70% total shareholder return over the past 12 months. Recent gains appear more like an acceleration of an already strong multi year run than a short lived reaction to headlines.
Scan Red Violet alongside other fast movers by reviewing a curated list of 21 high quality undiscovered gems that have been quietly building strong fundamentals and momentum.
After a move like Red Violet’s, the debate usually splits. Is this where most of the easy upside is already behind the stock, or does the recent surge still leave meaningful room based on valuation?
Most Popular Narrative: 7% Undervalued
Red Violet’s most followed valuation view pegs fair value at $84.50, slightly above the recent $78.56 close. This frames the current move as pricing in solid expectations rather than euphoric excess.
The main factor that has to go right is that Red Violet successfully uses its AI-enabled identity graph and strong balance sheet to deepen adoption in larger enterprise, public sector, and new vertical workflows while maintaining high gross margins and solid customer retention.
The current valuation implies that Red Violet is fairly valued and already reflects volume-based growth with high-30s adjusted EBITDA margins and continued execution on AI, workflow expansion, and upmarket customer mix.
See why 10 investors see Red Violet as 7% undervalued.
Analysts in this prevailing narrative are applying an 8.57% discount rate and arrive at a fair value of $84.50, which is about 7% above the last close and broadly aligned with the $84.50 consensus price target that sits only $5.94 above the current share price.
The assumed path involves revenue rising from $99.0 million to $144.9 million by 2029, profit margins edging from 16.5% to 18.1%, and earnings moving from $16.4 million to $26.2 million, with the share count also expected to climb 7.0% annually over the next three years as Red Violet reinvests and potentially leans on equity funding.
On those 2029 earnings of $1.48 per share, the view requires the market to pay a P/E of 81.2x, compared with 78.2x today and a current US Software sector level of 31.0x. The thesis effectively assumes investors will continue to accept a substantial premium multiple in return for volume driven growth, high gross margins and a balance sheet carrying more than $160 million of cash and no debt.
Against that backdrop, the narrative sees the stock as modestly undervalued relative to its own cash flow and earnings path, not dramatically mispriced. This puts more weight on your conviction around sustained search volumes, retention holding near current levels, and Red Violet’s ability to convert its pipeline in enterprise, public sector and newer verticals like home health care.
Result: Fair Value of $84.50 (UNDERVALUED)
Still, the story can change quickly if softer gross revenue retention and weaker real estate data usage within IDI spread into other key verticals.
Find out about the key risks to this Red Violet narrative.
Another View On Red Violet’s Valuation
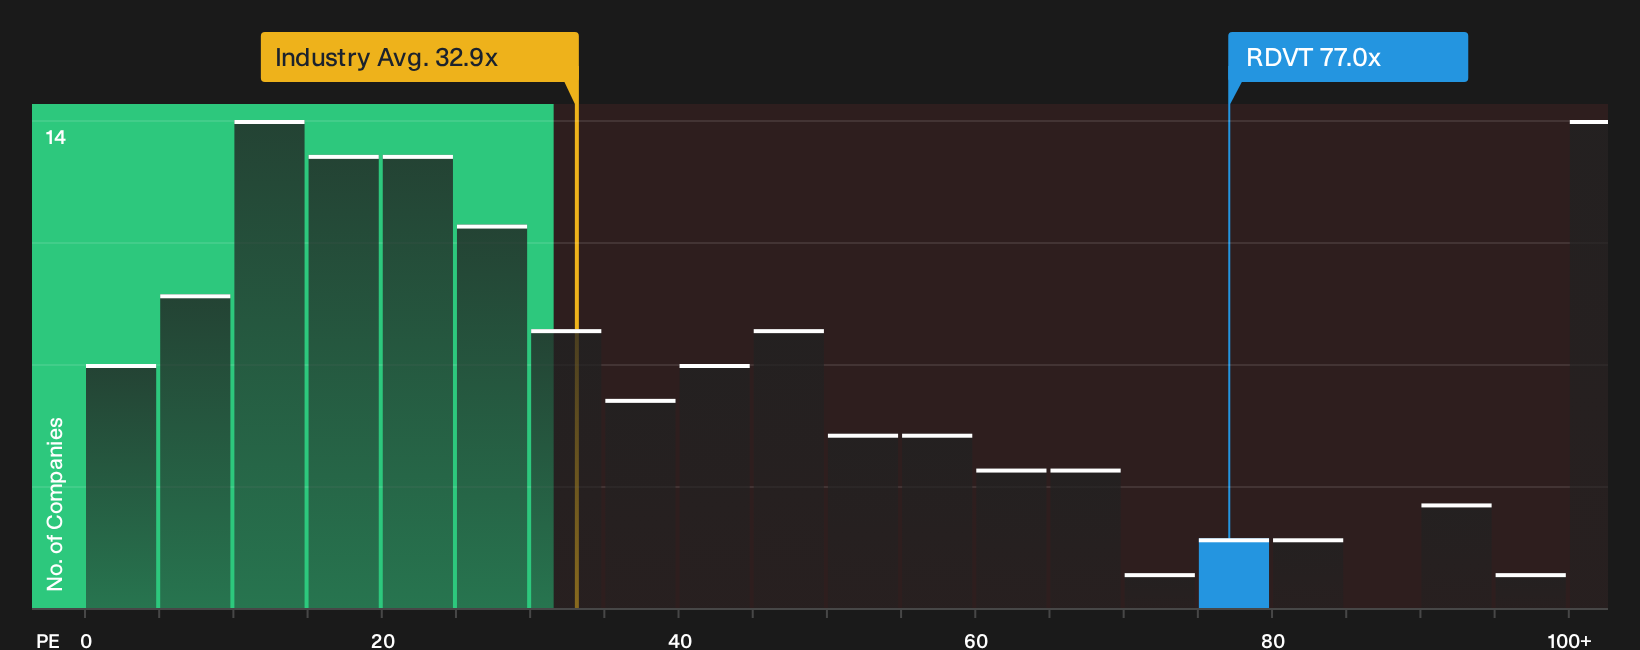
The story shifts once the focus moves from discounted cash flows to the price tag investors are already paying. Red Violet trades on a P/E of 77x, compared with 32x for the wider US Software group and a fair ratio estimate of 24.1x, which points to a steep premium and raises the question of how much optimism is already baked in.
For a closer look at how this premium compares with earnings power and peer pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong enthusiasm around Red Violet can be a useful signal, but your own judgment matters most. Pressure test the upside story against the 2 key rewards
Looking For More Investment Ideas Beyond Red Violet?
If Red Violet has your attention, do not stop there. Broader idea hunting can sharpen your decisions and help you spot opportunities you would otherwise miss.
- Target resilience by scanning a 31 resilient stocks with low risk scores that aims to spotlight businesses with sturdier balance sheets and lower overall risk profiles.
- Chase value by reviewing a 33 high quality undervalued stocks that filters for strong cash flow, healthy finances, and prices that may not fully reflect fundamentals.
- Build income potential by focusing on a 7 dividend fortresses built around higher yields and companies that prioritize regular shareholder payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com