
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Ingredion (INGR)'s Recyclable Paper Packaging Partnership Means For Shareholders
- UPM recently announced collaborations with Ingredion, Paramelt and Siegwerk to create paper based food and secondary packaging, with Ingredion supplying starch based barrier technology aimed at grease resistant, recyclable paper solutions.
- This move puts Ingredion's starch based materials directly into the sustainable packaging supply chain, linking its biomaterials know how to rising regulatory and customer pressure to reduce plastic use in food applications.
- We will now look at how Ingredion's role in grease resistant paper packaging could shape the broader investment narrative around the business.
Scan Ingredion alongside other packaging and materials players positioning for lower plastic use by zeroing in on 31 resilient stocks with low risk scores, which are poised to benefit from regulatory tailwinds in sustainable solutions.
Ingredion Investment Narrative Recap
To own Ingredion, you need to believe the shift toward higher margin Texture & Healthful Solutions and health focused ingredients can offset pressure in more commoditised starch and sweetener lines. The UPM collaboration fits that belief by putting Ingredion into paper based barrier applications, although on its own it does not change the near term story.
The key short term swing factor remains execution on mix upgrade and cost control after issues like Argo and tapioca sourcing. Currency and demand volatility in Latin America, along with price and mix headwinds when passing through lower input costs, still look like the biggest operational risks.
Against that backdrop, the push into grease resistant paper packaging with UPM, Paramelt and Siegwerk slots neatly into the existing Texture & Healthful Solutions catalyst. It expands the use cases for Ingredion’s starch based technologies into packaging, not just food texture or nutrition, which can help support the higher margin portfolio the market is already watching.
For you as an investor, the interest lies in how quickly this type of collaboration can scale into material revenue beside the much larger Tate & Lyle deal, ongoing divestments and digital tools like Ask Ingredion. These projects collectively point to a business leaning harder into specialty ingredients, while still needing to manage exposure to volatile input costs and FX swings.
Ingredion's current analyst narrative points to revenues of US$7.6b and earnings of US$777.7m by 2029. This is based on an assumed 1.8% yearly revenue growth rate and an increase in earnings of about US$185.7m from the current US$592.0m level.
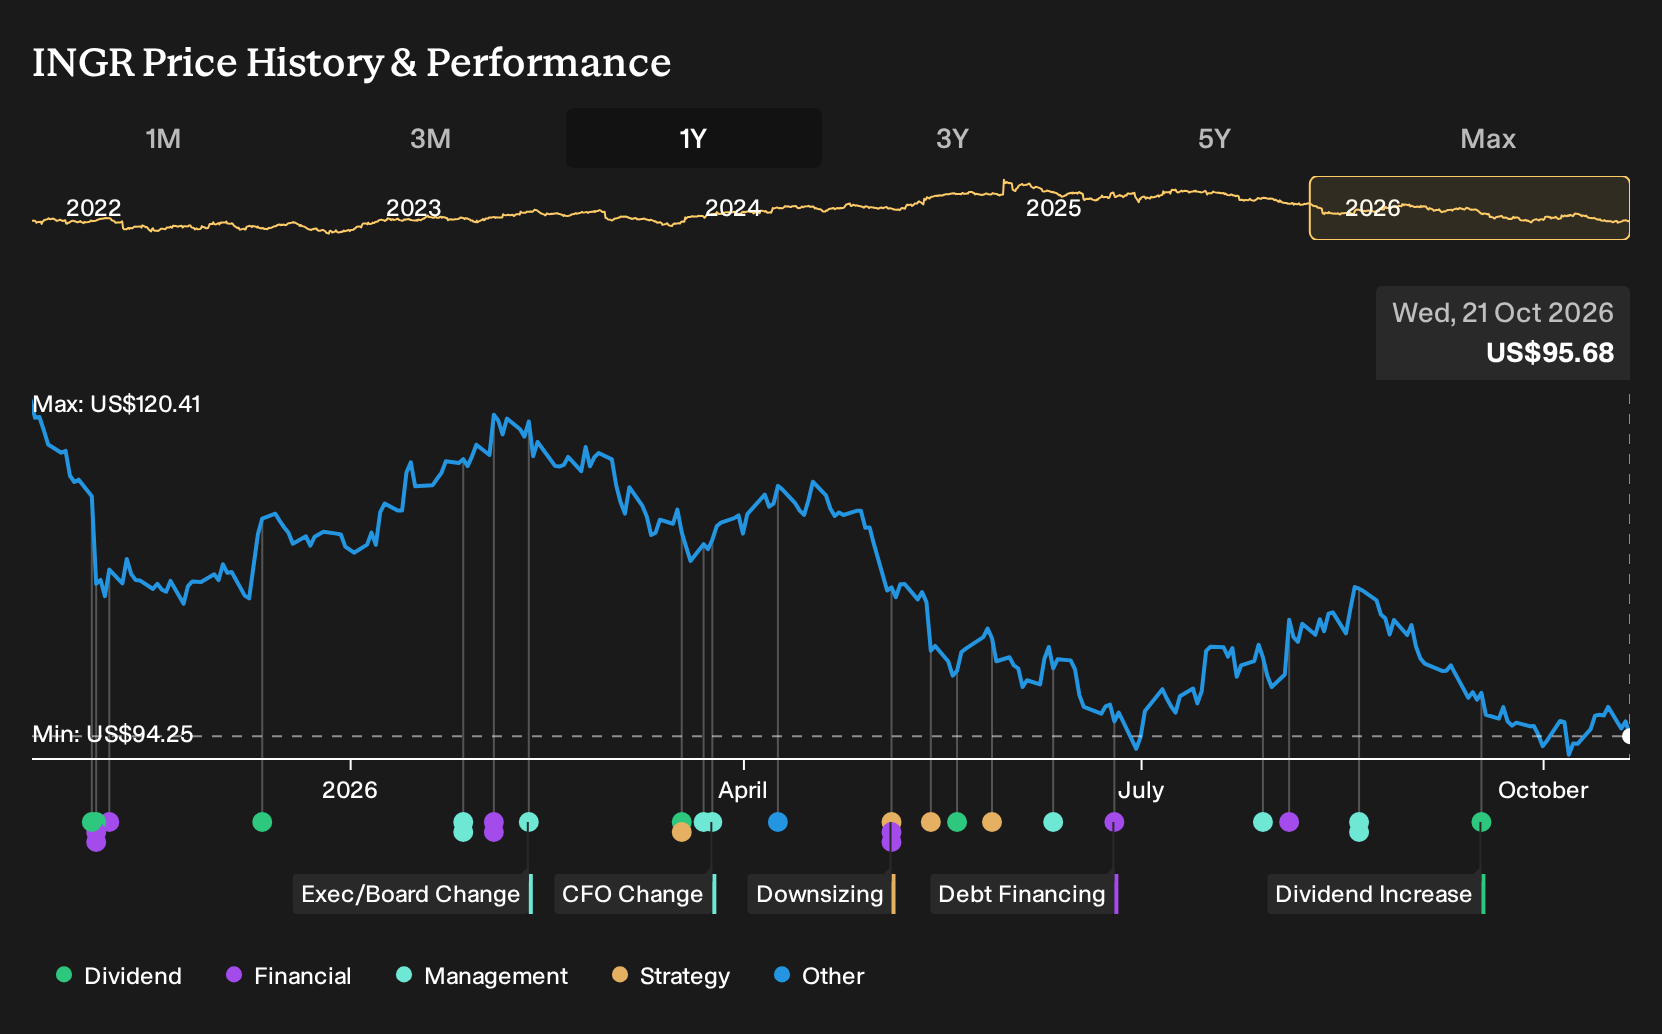
Uncover why Ingredion's fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats Ingredion’s AI driven formulation tools as the real swing factor rather than packaging moves like the UPM deal. The most optimistic analysts were already penciling in US$7.9b of revenue and US$806.7m of earnings by 2029. You can now ask whether this new packaging angle nudges those forecasts higher or reshapes them entirely.
Explore 3 other Ingredion fair value estimates, including one that suggests as much as 27% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ingredion research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Ingredion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ingredion's overall financial health at a glance.
Looking for more investment ideas beyond Ingredion?
If the Ingredion story has sharpened your thinking about where returns might come from next, use that lens across a wider watchlist. The Simply Wall St Screener lets you filter for financial strength, income potential, or mispriced quality so you can line up a broader bench of candidates that match your risk tolerance.
- For a focus on potential underpricing with quality fundamentals, scan a curated set of 33 high quality undervalued stocks that might warrant a closer look.
- If reliability and balance sheet strength matter most to you, filter for companies with sturdier finances through a list of solid balance sheet and fundamentals (25 results) that could handle tougher conditions.
- Income focused investors can concentrate on payout strength by reviewing 7 dividend fortresses that combine higher yields with detailed fundamental data.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com