
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Fiscal 2027 Guidance At WD 40 (WDFC) Has Changed Its Investment Story
- WD-40 reported fourth quarter 2026 sales of US$176.78 million and net income of US$14.36 million, alongside full year sales of US$687.99 million and net income of US$82.35 million, and issued fiscal 2027 guidance for net sales of US$715 million to US$735 million and diluted EPS of US$6.40 to US$6.70.
- The business paired this outlook with a fresh US$100 million share repurchase authorization and a regular US$1.02 quarterly dividend, reflecting management’s view of its maintenance products while balancing capital returns with ongoing margin pressures from higher petroleum based input costs.
- The focus now turns to how WD-40's 2027 sales and earnings guidance could influence the existing investment narrative around the stock.
Scan how WD-40's guidance and capital returns compare with other consumer-focused companies by jumping into our curated list of 33 high quality undervalued stocks.
WD-40 Investment Narrative Recap
To own WD-40, you need to be comfortable with a relatively mature household products business that leans on brand strength, pricing power and steady expansion of its maintenance portfolio. The latest quarter showed higher sales alongside lower net income and EPS, which keeps the focus on whether the firm can protect profitability while petroleum based input costs remain elevated.
The near term hinge is execution against fiscal 2027 guidance for sales, operating income and EPS, since management has now put specific ranges on the table. The key risk is that higher specialty chemical costs and lower margin homecare brands keep pressuring gross margin, which could limit how much of that targeted earnings progress actually reaches the bottom line.
The updated fiscal 2027 outlook is a key development. Management is guiding to net sales of US$715 million to US$735 million, operating income of US$114 million to US$120 million and diluted EPS of US$6.40 to US$6.70. These figures are being compared with a year in which full year revenue was US$687.99 million, while net income and EPS were lower.
For a holder of WD-40, that guidance effectively becomes the scoreboard for the main catalysts such as premium formats, Specialist products and geographic expansion. Delivery in that US$6.40 to US$6.70 EPS band, at a time when input costs are pressured, would indicate that the business is managing mix, pricing and overhead in a way that supports the longer term thesis.
What The WD-40 Forecasts Assume
Analysts are effectively asking you to underwrite a specific path for WD-40 over the next few years. The projections call for revenue to rise at about 6.2% a year, even as profit margins are expected to edge down from 13.2% today to 11.5% by 2029. That mix of higher sales with slightly thinner profitability sits behind the current consensus view of where the stock should trade.
On earnings, the current analyst framework starts with profit of US$89.0 million today and points to US$93.0 million by 2029. That is an increase of US$4.0 million, which is a modest uplift in absolute terms and much smaller than the gap between the present valuation multiple and the implied future P/E of 47.2x on those 2029 earnings. The narrative here focuses less on rapid profit expansion and more on whether the market is willing to keep paying a premium for WD-40 as a branded, cash generative consumer business.
In that context, the share count is expected to shrink by around 0.79% per year for the next three years. That assumption lines up with the new US$100 million repurchase authorization and would support earnings per share even if net income only moves gradually from US$89.0 million to US$93.0 million over the period. For investors, the question is whether this slow and steady profile matches what they want from a relatively mature household products stock at a premium multiple.
WD-40's narrative projects US$809.2 million revenue and US$93.0 million earnings by 2029. This is built on analysts using a 6.2% yearly revenue growth rate and an earnings increase of US$4.0 million from US$89.0 million today.
Uncover why WD-40's fair value indicates a 41% potential upside to its current price. This gap may not stay open for long.
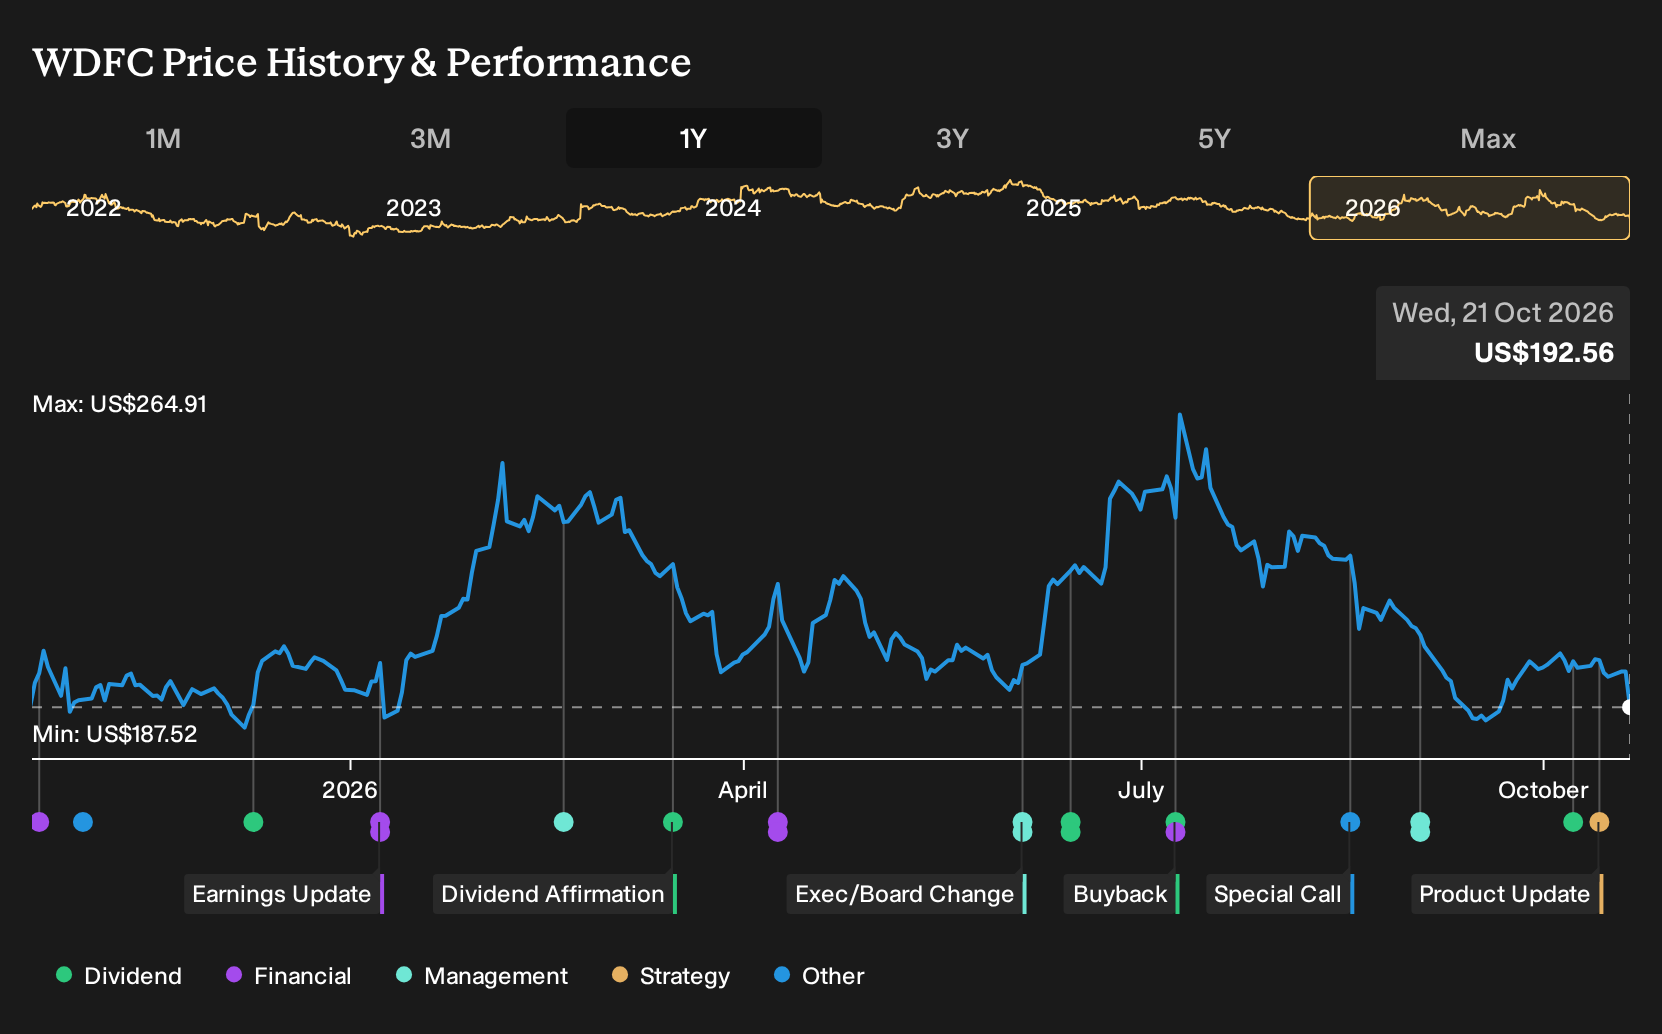
Exploring Other Perspectives
You are not the only one questioning WD-40 after this guidance. The most bearish analysts were already cautious on regional momentum, assuming revenue of about US$800.1 million and earnings of US$95.3 million by 2029. Their slower growth story may look even more conservative or could be revised if this latest outlook changes sentiment.
Explore 2 other WD-40 fair value estimates, including one that suggests as much as 85% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your WD-40 research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for WD-40. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WD-40's overall financial health at a glance.
Looking For More Investment Ideas Beyond WD-40?
If WD-40's guidance has you rethinking your watchlist, broaden your opportunity set by scanning other companies that fit clear, fundamentals based filters in the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, review our 33 high quality undervalued stocks that blend strong fundamentals with potentially attractive pricing.
- If capital preservation and stability rank high on your checklist, focus on companies in the 31 resilient stocks with low risk scores to see which businesses score well on resilience.
- For those hunting for balance sheet strength as a backbone for long term compounding, start with the list of solid balance sheet and fundamentals (25 results) and narrow down to the profiles that fit your style.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com