
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Top Australian AI Healthcare Stocks For October 2026
AI-focused companies just received a powerful reminder of how central their technology has become. A critical PHP security flaw only came to light after advanced models flagged risks that humans had missed for years. That kind of real world stress test matters for Australian healthcare, where data security and accuracy are non negotiable. This article walks through three AI driven healthcare stocks from our screener that may be worth a closer look.
These three Australian stocks are just a small sample, and the full screen surfaced 4 more healthcare AI companies with equally compelling stories that are not covered below. To identify your own highest conviction ideas, head straight into the Transformative Artificial intelligence (AI) Healthcare Stocks screener to filter and analyze the wider opportunity set.
ImExHS (ASX:IME)
ImExHS uses its AQUILA, ALULA, and ANTEROS imaging platforms plus radiology services to power AI ready scan workflows, generating about A$10 million from software and A$21 million from radiology, and carries a micro-cap market value near A$17 million.
For an AI healthcare theme, ImExHS matters because its imaging platforms and radiology services sit directly in the diagnostic workflow, where software speed and data quality decide whether AI tools actually gain traction in hospitals.
"The quarterly release indiates the company is getting through to profitability and cashflow sustainability. They also understand the challenge now is to drive the software sales and revenue much faster in 2026."
What happens to margins if one unseen pressure around how fast hospitals adopt its higher value software tier shifts in either direction?
If that software mix really is the swing factor, the full narrative for ImExHS explains how ImExHS could accelerate or stall as hospitals adjust their workflows.

Paragon Care (ASX:PGC)
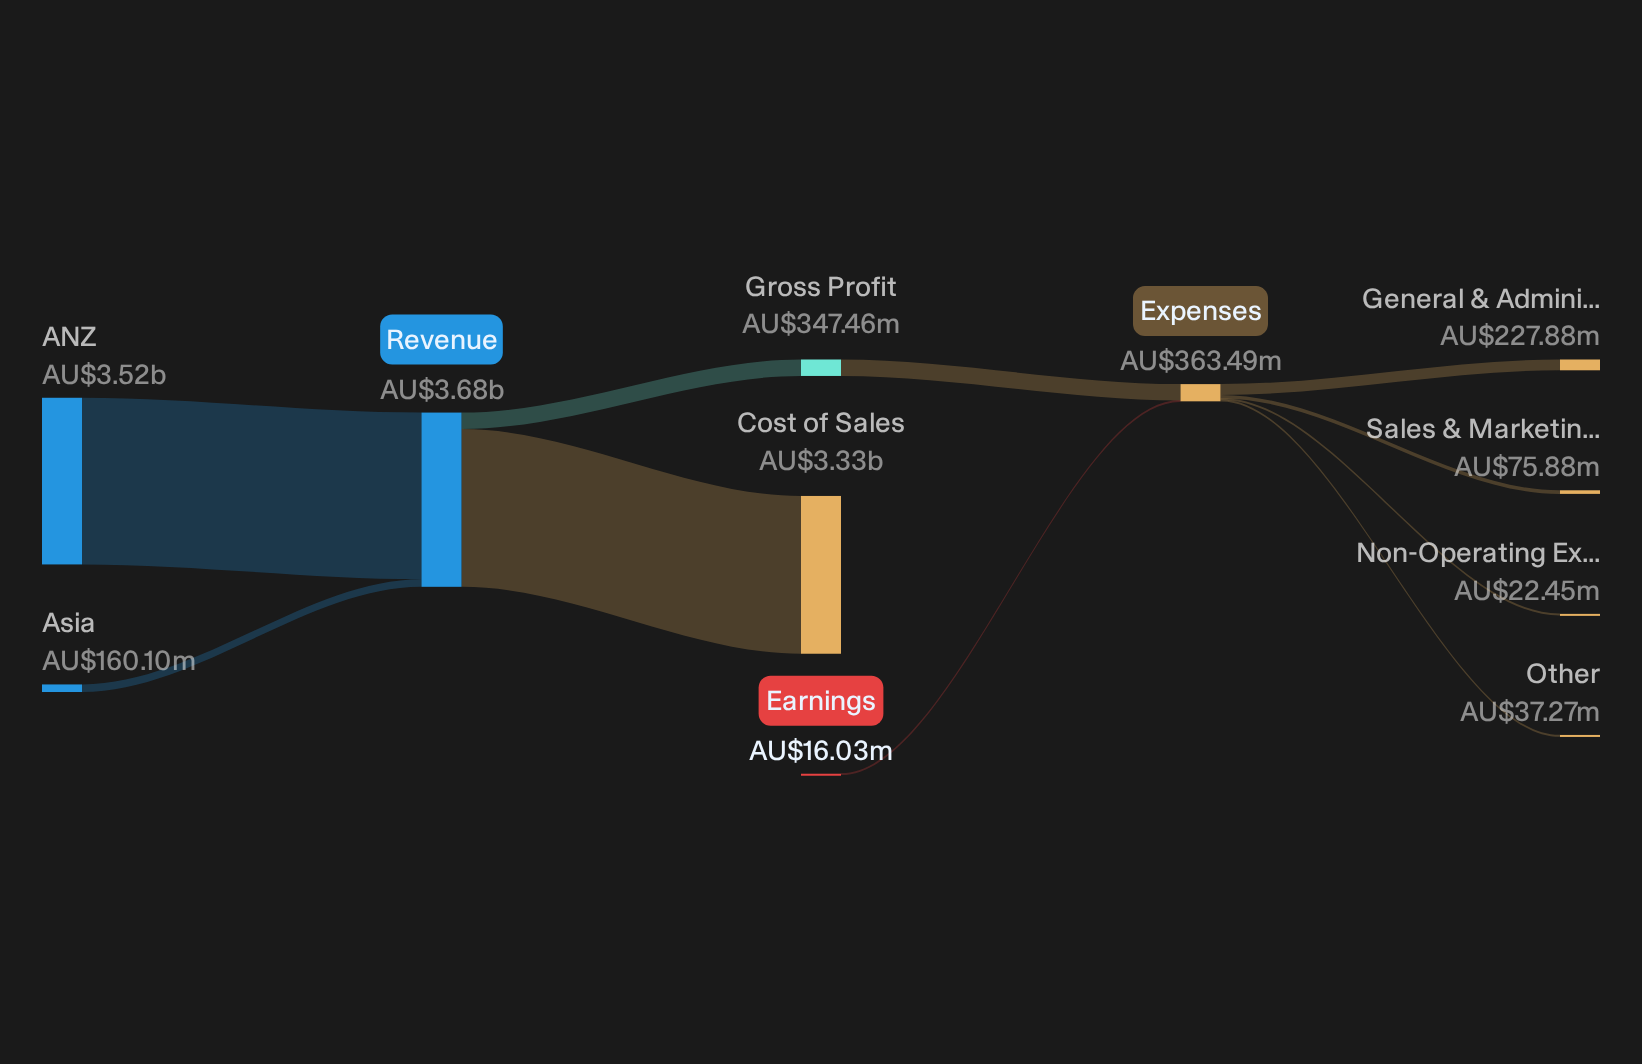
Paragon Care distributes a wide range of medical equipment and consumables across Australia, New Zealand, and Asia. Its AI-driven imaging and diagnostic software line gives it a direct role in how hospitals start to use smarter scan interpretation tools.
Paragon Care generated about A$3.5b from ANZ operations and A$160 million from Asia, and the stock carries a market value near A$248 million.
Where Paragon Care is particularly relevant for AI-focused investors is that behind its broad catalogue of hospital and pharmacy supplies, it also supplies AI-ready imaging and diagnostic software that can plug directly into the kind of clinical workflows this screener targets.
"The integration of recent acquisitions and ongoing operational synergies (with a target of $12 million annual run-rate in FY '26), coupled with the consolidation of business functions onto a unified JDE platform, are likely to improve cost efficiencies and structurally enhance net margins and EBITDA."
What happens to those future margins depends in part on how one unresolved issue around leverage and funding costs evolves over time.
If you want to see how that funding question could accelerate or cap Paragon Care, the full narrative for Paragon Care explains the leverage trade off and outlines the potential upside catalysts.
Artrya (ASX:AYA)
Artrya focuses on using artificial intelligence to read coronary CT angiography scans through its Salix software, aiming to improve how clinicians detect and manage coronary artery disease. It currently reports A$0.03 million from AI-driven CCTA image analysis in Australia and carries a market value near A$432 million.
Artrya plugs directly into the AI healthcare theme because its Salix platform is built to improve how quickly and accurately cardiologists spot heart attack risk from routine scans. This positioning places its business model at the intersection of diagnosis, workflow efficiency, and software based medical decisions.
"Growing adoption of CCTA as a front-line tool for chest pain assessment, together with up to 400,000 scans a year across SAPPHIRE partners at a blended rate of about US$850 per scan across three modules, gives Artrya a clear volume pathway that directly targets future subscription and fee per scan revenue."
What happens to Artrya’s earnings profile if one assumption around how quickly hospitals change their cardiac imaging routines proves too optimistic or too cautious?
If that timing on hospital behaviour is the real swing factor, the full narrative for Artrya shows where Artrya’s adoption curve could accelerate or quietly stall.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while data is still under the radar for now. Do not get caught chasing. Consider acting early instead of waiting for a late entry.
- Spot potential momentum pivots by scanning a curated 4 high quality undervalued stocks that may still be flying under most investors' radar.
- Hunt for smaller opportunities with real balance sheet support by running through the hand picked list of solid balance sheet and fundamentals (12 results).
- Target future facing infrastructure by checking the focused 55 AI infrastructure stocks before capital flows fully catch up to the trend.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com