
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Return To Quarterly Profit At Billerud (OM:BILL) Has Changed Its Investment Story
- Billerud reported third quarter 2026 results with sales of SEK 10,166 million and net income of SEK 212 million, compared with a loss in the same period last year.
- The nine month figures still show a net loss and lower sales year on year, which highlights that the return to profit in the latest quarter comes while broader performance remains under pressure.
- We will now see how Billerud's investment narrative could be affected by this return to quarterly profitability after earlier losses.
See how Billerud's rebound to a quarterly profit compares with other companies showing resilient fundamentals in our 190 high quality undervalued stocks.
Billerud Investment Narrative Recap
Billerud attracts shareholders who buy into a packaging player trying to shift toward higher value board and paper while wrestling with cyclical pressure. The quarterly profit supports the view that cost measures and mix improvements can show through when conditions are less harsh. In the short term, the key swing factor remains how quickly demand and pricing stabilize in Europe.
The main risk still lies in structurally weak volumes, overcapacity and competitive pressure in both Europe and Asian export markets, where price discipline can crack quickly. One profitable quarter does not change the execution risk around the North American Evolution program, which still needs to ramp efficiently to support returns.
The latest quarterly report is the key disclosure here. Billerud reported SEK 10,166 million in third quarter 2026 sales and SEK 212 million in net income, moving from a loss a year earlier. Earnings per share from continuing operations reached SEK 0.85, indicating that the business is at least showing it can earn money in the current setup.
Across the first nine months, Billerud still reported SEK 29,825 million in revenue and a net loss of SEK 71 million. That tension between a profitable quarter and a loss-making year to date keeps the focus firmly on execution, especially cost control, product mix, and the timing of any further capacity or restructuring decisions in its core board and paper operations.
Billerud's current analyst narrative points to revenues of SEK 41.3b and earnings of SEK 2.0b by 2029, based on 1.7% yearly revenue growth and an earnings increase of about SEK 1.9b from SEK 77.0m today.
Uncover why Billerud's fair value points to a 6% potential downside to its current price, a premium that may not hold.
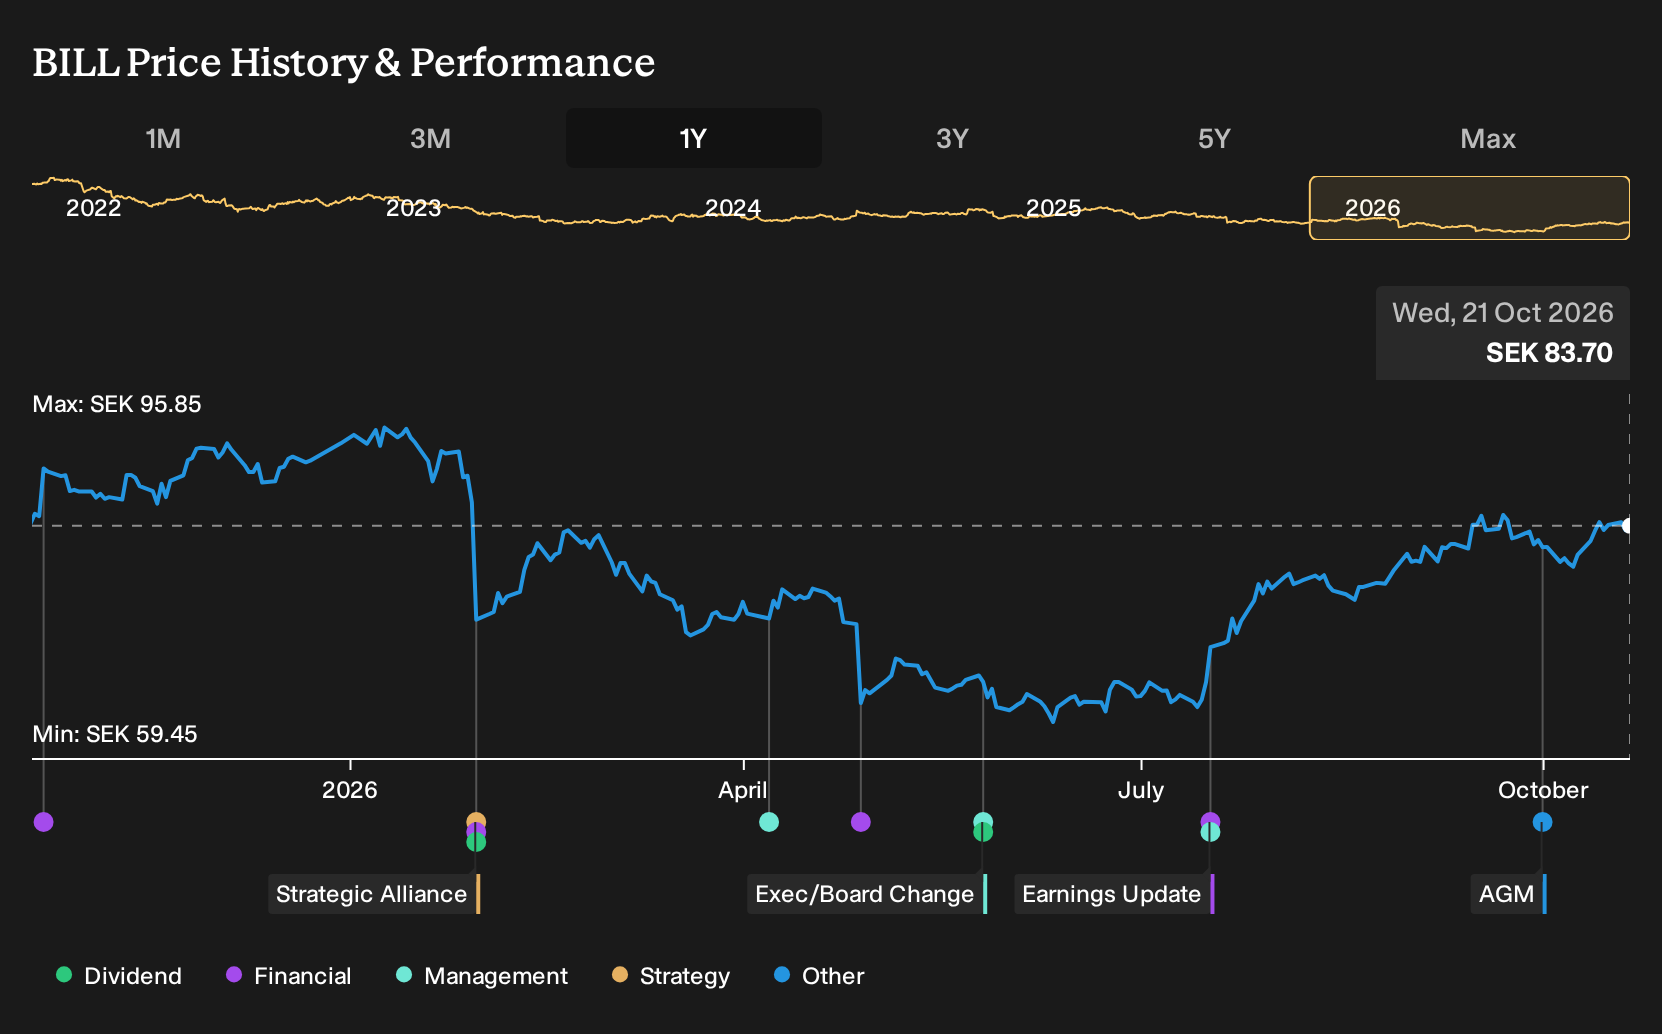
Exploring Other Perspectives
For a different angle, focus on the bullish view that Billerud’s North American push could matter far more than consensus assumes. The most optimistic analysts were already pencilling in SEK 42.4b of revenue and SEK 2.1b of earnings by 2029 before this profit return, so this fresh data may shift those narratives again.
Explore another Billerud fair value estimate, including one that suggests as much as 162% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Billerud research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Billerud. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Billerud's overall financial health at a glance.
Looking For More Ideas Beyond Billerud?
If Billerud has sharpened your interest in packaging and materials, it can help to compare it with companies that show different combinations of quality, balance sheet strength, and risk. The Simply Wall St Screener gives you a quick way to filter for the traits that matter most to you, then build a watchlist that matches your investing style.
- If you want potential value with financial resilience, start with a list of solid balance sheet and fundamentals (203 results) that can handle rough patches without constant refinancing worries.
- For investors who put capital protection first, scan through a 227 resilient stocks with low risk scores that screens strongly on stability and risk controls.
- Curious about opportunities that attract less attention, but still have solid fundamentals? Check out a 618 high quality undiscovered gems that may not yet be on most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com