
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To C.H. Robinson Worldwide Stock As Earnings Near
- C.H. Robinson Worldwide recently drew attention ahead of its September 2026 quarter results, with analysts expecting higher earnings and revenue compared with the prior year.
- The gap between a slightly higher consensus EPS estimate and a lower Most Accurate Estimate highlights fresh questions about how current freight conditions and cost controls could show up in near term profitability.
- We will now look at how C.H. Robinson Worldwide's upcoming earnings report could influence the existing Lean AI focused investment narrative.
Scan how C.H. Robinson Worldwide measures up against a curated list of solid balance sheet and fundamentals (25 results) that could handle similar freight and earnings pressure.
C.H. Robinson Worldwide Investment Narrative Recap
To own C.H. Robinson Worldwide, you need to be comfortable with a freight broker that leans heavily on its Lean AI model and large data set to keep productivity and margins in line, even when pricing is under pressure. The near term catalyst is whether the September quarter shows that automation can support earnings consistency while freight conditions remain mixed.
The biggest current risk is that higher legal and insurance pressure, including the recent US$604m jury award, pushes up the cost of doing business faster than efficiency gains offset it. The upcoming report matters, but it is one data point rather than a decisive shift in the long term thesis.
Recent commentary around C.H. Robinson Worldwide has focused on scaling AI driven automation in NAST, Global Forwarding and LTL, where management has talked about more than 60% productivity gains in some workflows. In the context of the October 28 earnings release, investors will be watching whether higher shipment volumes can be handled without similar increases in headcount and operating expense.
The same automation push that supports the bull case also interacts with risk. If courts continue to scrutinise broker liability and insurance becomes more expensive, the ability to keep handling more quotes and loads with relatively flat staffing could be a key offset. The coming quarter will give you a fresh read on whether the Lean AI model is translating into resilient margins while legal, freight and cost pressures stay elevated.
C.H. Robinson Worldwide's current analyst storyline points to revenues of US$20.4b and earnings of US$953.9m by 2029, built on expected yearly top line expansion of 6.2% and an earnings increase of about US$320.6m from US$633.3m today.
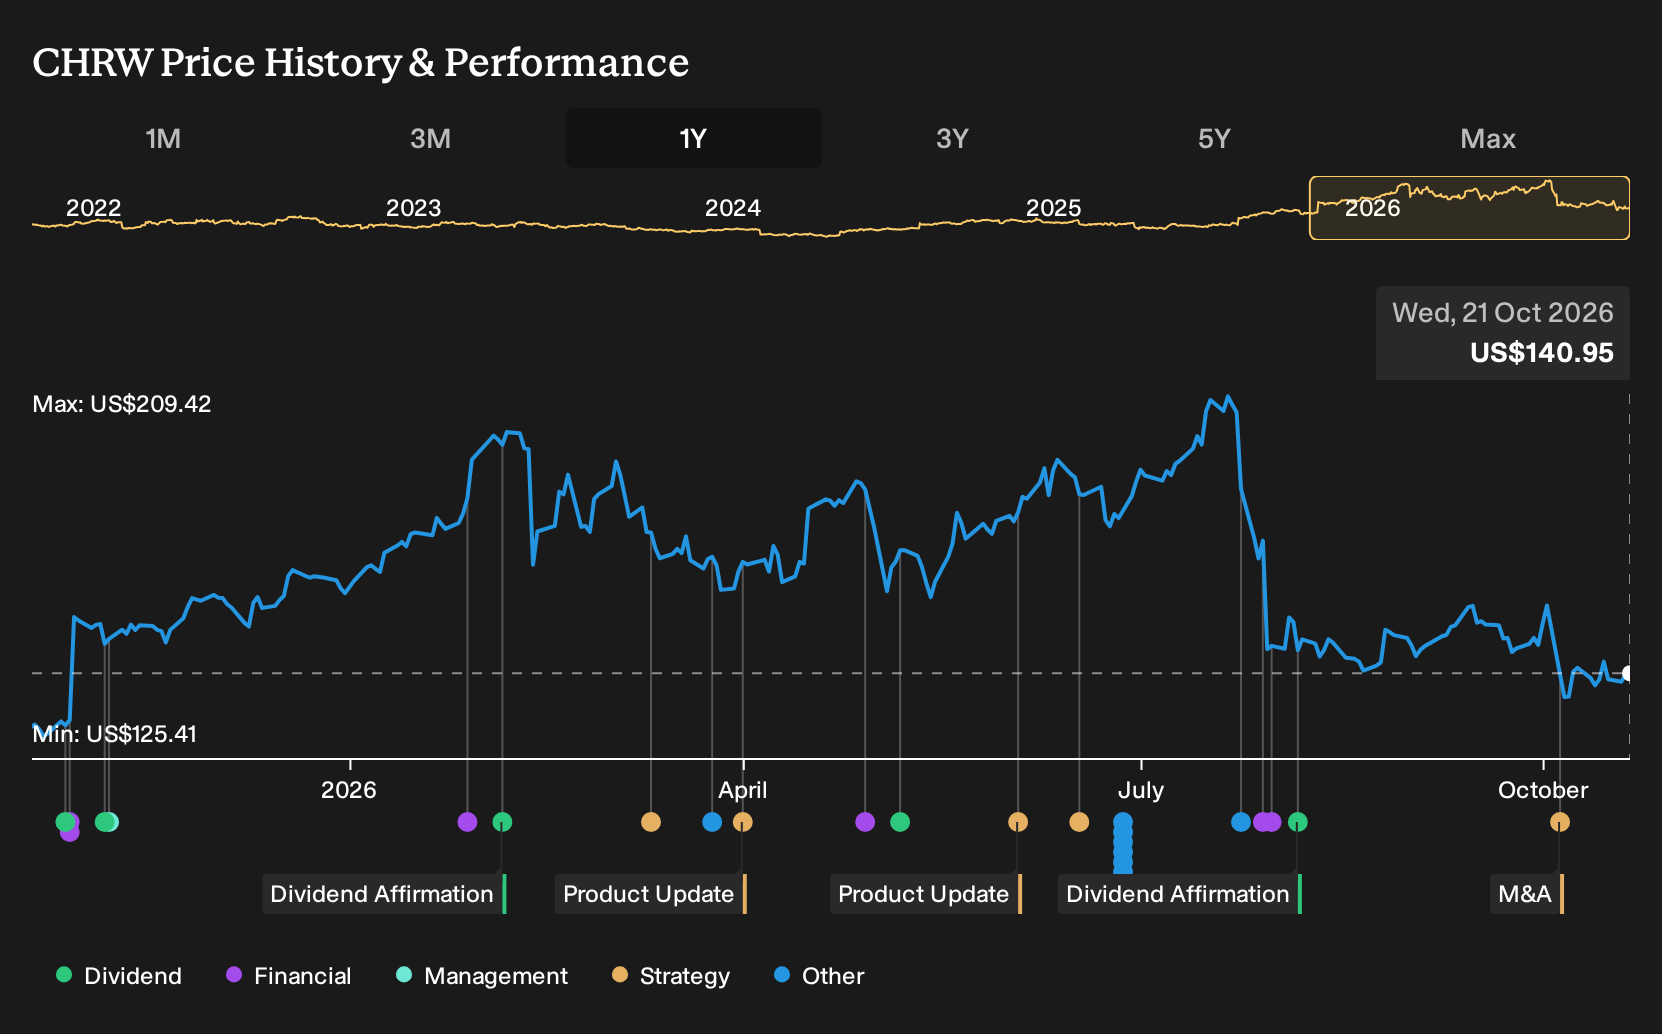
Uncover why C.H. Robinson Worldwide's fair value indicates a 38% potential upside to its current price before the discount narrows.
Exploring Other Perspectives
One alternate view on C.H. Robinson Worldwide puts the legal overhang front and center. That bearish camp worries that nuclear verdict risk and higher compliance work limit the benefit of Lean AI. Those analysts were penciling in around US$20.1b of revenue and US$908.8m of earnings by 2029, so their pre news story already looked more cautious and could shift further depending on what this quarter reveals.
Explore 2 other C.H. Robinson Worldwide fair value estimates, including one that suggests up to 10% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your C.H. Robinson Worldwide research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for C.H. Robinson Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate C.H. Robinson Worldwide's overall financial health at a glance.
Looking for more investment ideas beyond C.H. Robinson Worldwide?
If you want to pressure test your view on C.H. Robinson Worldwide against other opportunities, a quick scan through a few focused stock lists can help you spot businesses with the balance of quality, risk and income that fits your style.
- For investors who care most about resilient finances, compare C.H. Robinson Worldwide with a broader list of solid balance sheet and fundamentals (25 results) that can absorb tougher operating conditions.
- If value is your priority, line up the current price of C.H. Robinson Worldwide beside 33 high quality undervalued stocks that pair strong fundamentals with what could be discounted market expectations.
- Income focused investors can benchmark C.H. Robinson Worldwide's yield and payout profile against 7 dividend fortresses built around higher cash returns and sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com