
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Celanese Stock Could Change Following Guidance Reaffirmation
- Celanese reaffirmed its 2026 adjusted earnings outlook of about $6 per share and free cash flow guidance of $700 million to $800 million, while also declaring a quarterly dividend of $0.03 per share and finalizing committee roles for new director Anne P. Noonan.
- The reiterated earnings and cash flow framework, supported by productivity measures and portfolio actions, keeps attention on how efficiently Celanese converts its operating plans into sustainable cash generation.
- The next step is to examine how Celanese's reaffirmed earnings and free cash flow guidance could influence the broader investment narrative around the business.
Scan how Celanese's reaffirmed cash flow plans compare with other potential compounders by reviewing our hand picked 33 high quality undervalued stocks that also pair earnings power with balance sheet support.
Celanese Investment Narrative Recap
To own Celanese, you need to be comfortable with a chemicals producer that is currently loss making but still presenting US$700 million to US$800 million in annual free cash flow as achievable. The reaffirmed 2026 adjusted earnings outlook of about US$6 per share keeps attention squarely on cost savings, footprint changes and working capital discipline.
The near term swing factor remains how quickly end markets like Engineered Materials and acetyls absorb inventory and stabilize volumes. The main risk stays the same. Weak demand or prolonged customer destocking could limit volume recovery, which would make it harder for Celanese to translate its cost programs into the cash generation it is targeting.
The most relevant fresh data point is Celanese reiterating its full year free cash flow guidance of US$700 million to US$800 million. That target matters because it underpins deleveraging plans, interest expense management and the company’s ability to keep funding footprint changes and growth projects without stretching the balance sheet.
For catalysts, investors will likely watch how that cash flow interacts with the small but ongoing US$0.03 per share quarterly dividend and any progress on portfolio or footprint moves that might support the earnings framework. If order visibility remains patchy or inventory absorption drags, the pressure will fall back on execution against those productivity and cost reduction goals.
Celanese Forecasts Framed Against Analyst Expectations
Celanese's narrative projects US$10.0 billion revenue and US$738.3 million earnings by 2029. This sits alongside analyst assumptions that top line performance remains fairly flat over the next few years and earnings move from a loss of US$1.2 billion today to that US$738.3 million level, which is an increase of about US$1.9 billion.
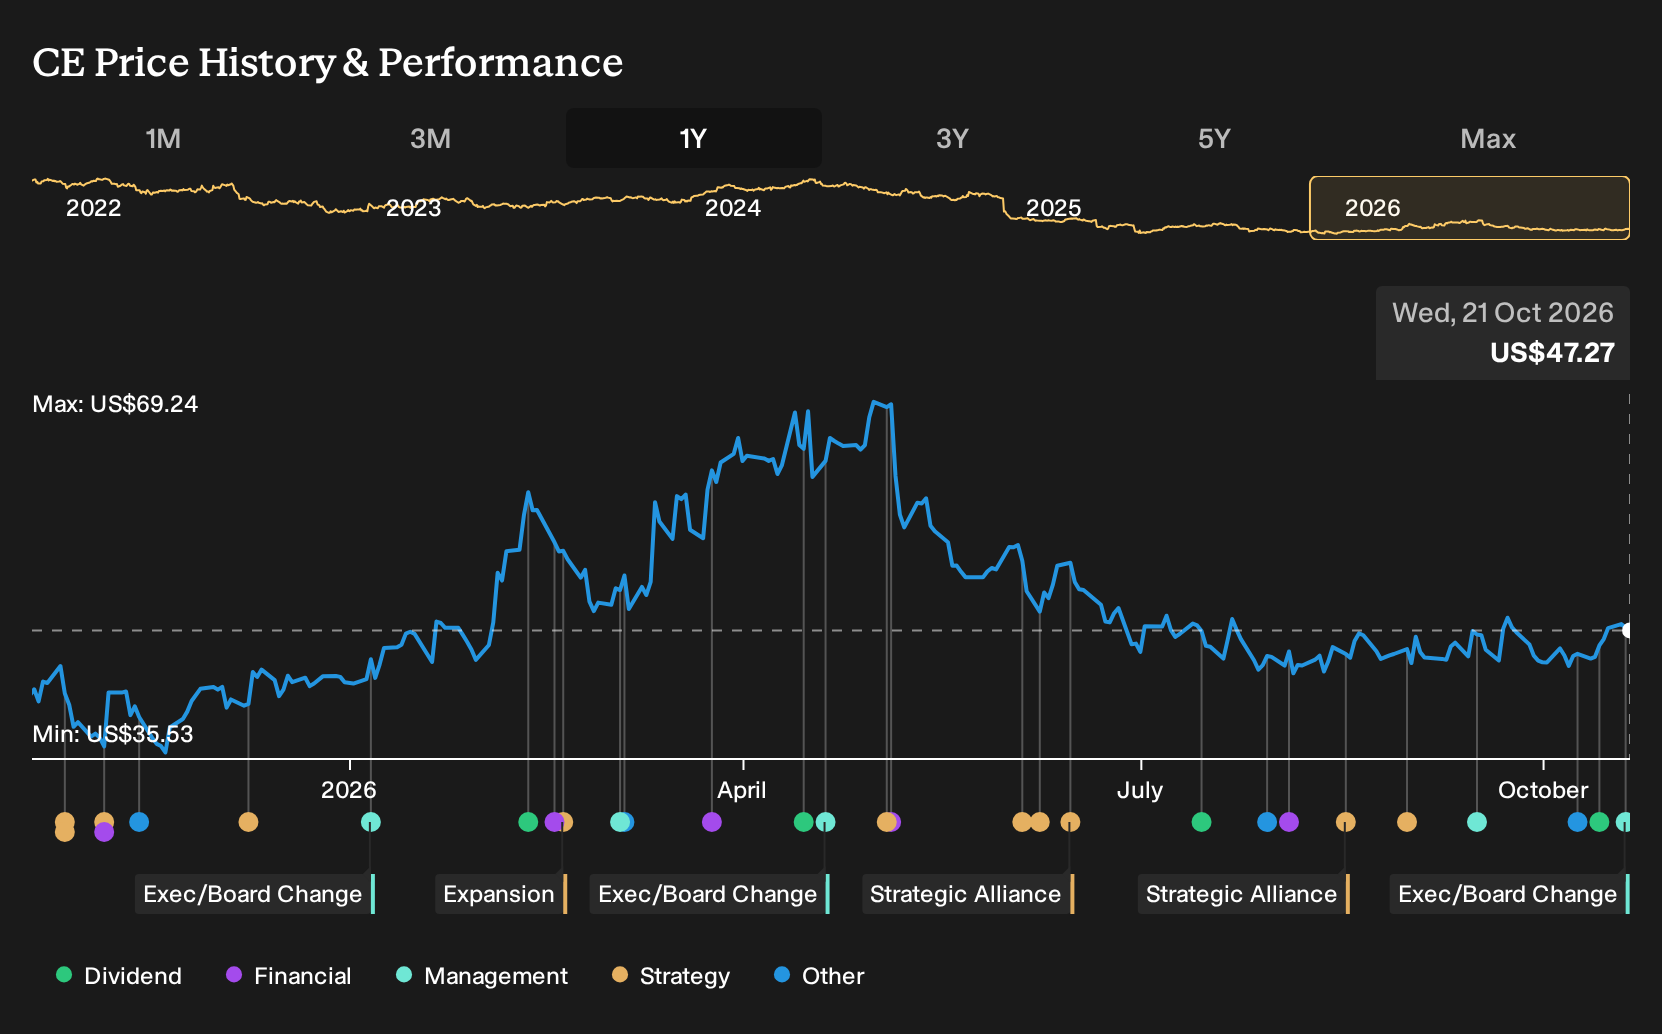
Uncover how Celanese's fair value indicates a 29% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
You see a different angle in the bullish narrative. Those higher conviction analysts focus on execution of working capital and divestiture plans, with earlier expectations that Celanese could have reached US$11.1b in revenue and US$1.1b in earnings by 2029. The refreshed board committees and reiterated cash targets may prompt some of those views to shift.
Explore 3 other Celanese fair value estimates, including one that suggests as much as 142% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Celanese research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celanese. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Celanese's overall financial health at a glance.
Looking for more investment ideas beyond Celanese?
If you are weighing Celanese against other opportunities, it can help to line it up next to peers with different income profiles, balance sheet strength and risk levels using the Simply Wall St Screener.
- For investors who want income to do more of the work, review companies with resilient payouts and balance sheets through the 7 dividend fortresses.
- If capital preservation sits high on your list, compare Celanese with stocks that score well on financial resilience using the 31 resilient stocks with low risk scores.
- When you want to widen the search beyond well covered tickers, scan a 21 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com