
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Aboitiz Power's Run? Here Is What Holders Saw
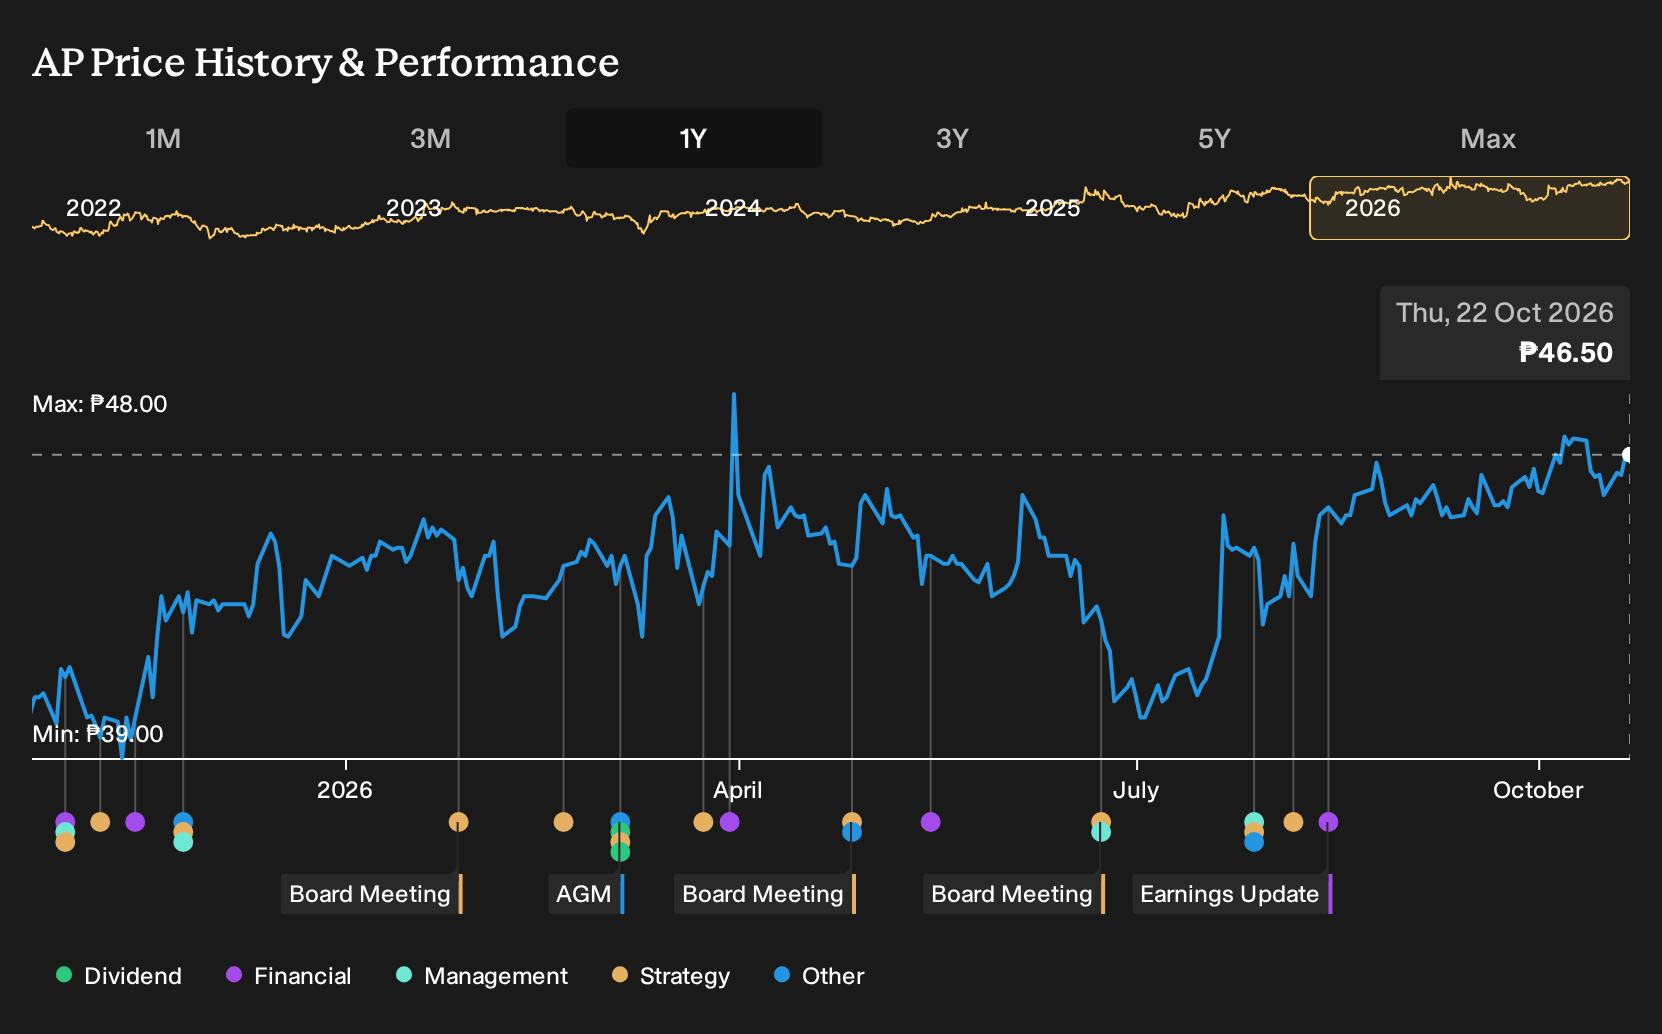
Aboitiz Power’s latest report put hard numbers behind its expanding contracts and renewable build, with Q2 2026 revenue of ₱70,181.855m and net income of ₱10,513.913m on record. Holding Aboitiz Power over the past year would have returned 20.9%, including dividends. If you had been weighing a purchase back on 22 October 2025, what exactly would you have needed to believe about future volumes, pricing power, and contract coverage?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Aboitiz Power harder to judge, start where the gap is still open and scan 190 high quality undervalued stocks.
The Argument You Would Have Had To Settle On Aboitiz Power
The shares cost ₱40.5 at the start of the period, and anyone looking at Aboitiz Power had to pick which story felt more realistic.
The bullish Narrative set Fair Value at ₱45.54, tied to ideas such as 9.6% revenue growth and profit margins settling at 13.9% over a 3-year span.
The bearish Narrative pointed to ₱30 Fair Value, focusing on oversupply risk in Luzon and the possibility that heavy fossil fuel spending could leave assets stranded.
What The Results Changed For Aboitiz Power
Aboitiz Power put Q2 2026 revenue at ₱70,181.855m and net income at ₱10,513.913m, against ₱48,257.824m and ₱8,049.994m a year earlier. Profit rose while net margin slipped from 16.7% to 15.0%. The combination supported the optimistic volume and earnings case, yet left the stronger margin compression in the bearish story still on the table. It cut both ways.
The hinge assumption here was margin durability. When you assess another utility, compare revenue and net income with the reported net margin trend to see whether growth is arriving through healthier pricing or simply heavier volume.
What Aboitiz Power’s Current Price Already Bakes In
Aboitiz Power now trades at ₱46.5, after returning 20.9% over the past year. This selected Narrative places its Fair Value above that level and links the gap to how far the portfolio can tilt toward renewables, contracted baseload and fee-based ancillary earnings.
On that view, today’s price still does not fully credit a larger, more contracted and more diversified Aboitiz Power with steadier EBITDA quality and net margins.
"Aboitiz Power’s shift from a coal heavy portfolio toward more solar, hydro and battery storage capacity, including the integration of the 789 MW CBK hydro complex and multiple new BESS and solar projects, could change the earnings mix toward contracted and ancillary revenues that support higher EBITDA quality and potentially better net margins."
The price and this Narrative do not agree. → Uncover what this Narrative says Aboitiz Power is actually worth
Where Aboitiz Power’s Theme Extends
Aboitiz Power points you toward one version of the future grid. It focuses on contracts, renewables and returns anchored in real assets.
Step sideways and similar demand appears at another utility. It is leaning into renewables, large storage projects and regulated wires.
That business targets rising data center loads with dedicated generation hubs. It is also advancing gas projects supported by long-term contracts.
Both stories revolve around predictable cash flows and grid reliability. If you are testing the Aboitiz Power thesis, that parallel remains hard to ignore.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 23% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com