
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CACI International (CACI) Lifts Outlook, Is The 15% Undervaluation Case Still Compelling?
Why CACI International’s latest earnings matter for shareholders
CACI International (CACI) just reported first quarter results, with sales of US$2.47b and net income of US$130.37m, alongside higher basic and diluted earnings per share from continuing operations versus a year earlier.
The latest move in CACI International’s share price suggests that momentum has been building. The stock advanced 29.7% over the past 90 days and has a 1-year total shareholder return of 19.8%. The current US$623.38 share price compares with a 5-year total shareholder return of 129.1%.
Fresh earnings, a slightly higher fiscal 2027 outlook, and the shift to a calendar year reporting schedule give investors more context for that performance. These developments tighten the link between reported results, contract wins, and how the market is reassessing CACI’s longer term risk and growth profile.
Scan how CACI International’s momentum compares with other defense and government IT contractors by reviewing our handpicked 31 resilient stocks with low risk scores in the same space.
For CACI International, a 30% move in three months can either echo improving contract economics and guidance, or just reflect a mood shift in defense and IT stocks. The valuation now has to carry that story.
Most Popular Narrative: 15% Undervalued
CACI International’s most followed valuation story pegs fair value at $735.21, above the recent $623.38 share price. This puts the recent rally in a different light for anyone weighing upside against execution risk.
The numbers imply that CACI International’s share price embeds a discount to a business generating at least US$900m of free cash flow in FY27 and at least US$2.1b over FY25 to FY27 with EBITDA margins in the high 12% range. This narrative views that setup as consistent with an undervalued and bullish stance.
See why 28 investors see CACI International as 15% undervalued.
Result: Fair Value of $735.21 (UNDERVALUED)
Still, the CACI International narrative leans heavily on turning a record US$32b backlog into higher free cash flow and sustaining a premium P/E multiple; both of these factors could disappoint.
Find out about the key risks to this CACI International narrative.
Another View: What CACI International’s P/E Is Really Telling You
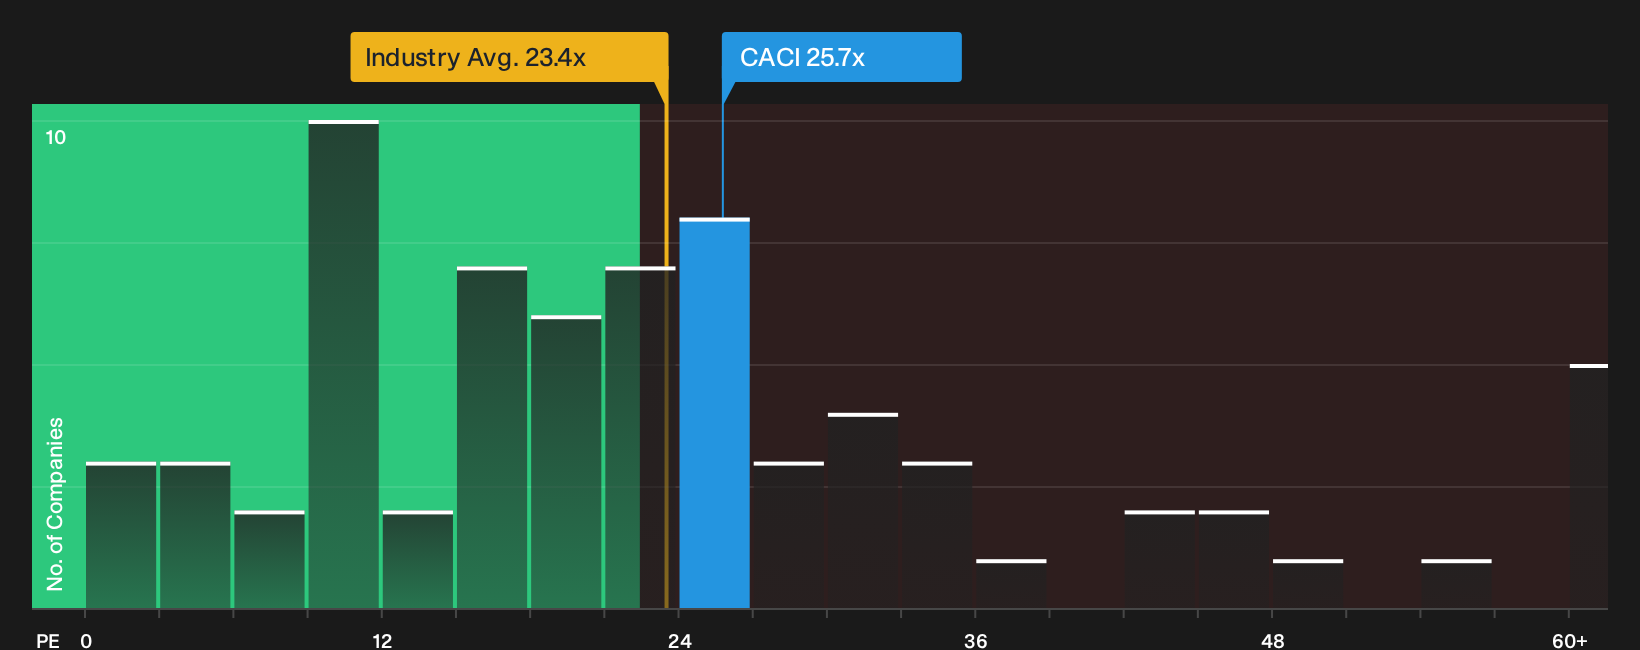
There is a sharp contrast once you move from the cash flow narrative to simple earnings multiples. CACI International trades on a P/E of 25.7x, while the US Professional Services group sits around 23x and the fair ratio flags 21.6x. That means the stock carries a richer earnings tag than both its wider sector and the level the fair ratio suggests the market could drift toward. For investors, the practical question is whether the business has done enough to justify paying up, or if that gap just adds valuation risk if sentiment cools.
For a closer look at how this earnings multiple stacks up against peers and the fair ratio, and what that might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and risk around CACI International feels finely balanced, move quickly, pressure test the numbers, and form your own stance using our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond CACI International?
If CACI International has sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas that match how you like to invest.
- Target stability first and cut portfolio stress by focusing on companies in our 31 resilient stocks with low risk scores.
- Chase value efficiently by scanning for mispriced quality using the 33 high quality undervalued stocks.
- Build an income stream you can actually measure by reviewing the 7 dividend fortresses before the next round of payouts sets up the field.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com