
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FDA Clears Oral Pellets That Could Be A Game Changer For BioCryst Pharmaceuticals (BCRX)
- BioCryst Pharmaceuticals reported that the FDA has approved a 150 mg oral pellet formulation of once daily ORLADEYO for prophylactic treatment of hereditary angioedema in adults and adolescents who prefer an option other than capsules.
- The new, sprinkle-like pellet format broadens ORLADEYO delivery choices, which may influence long-term treatment adherence patterns and prescribing behavior for hereditary angioedema care.
- The focus now turns to how BioCryst Pharmaceuticals' investment narrative aligns with this new oral pellet option for ORLADEYO.
BioCryst Pharmaceuticals Investment Narrative Recap
To own BioCryst Pharmaceuticals, you need to believe ORLADEYO can remain a meaningful hereditary angioedema prophylaxis option while the rare disease pipeline matures. The new 150 mg oral pellets fit that thesis by giving prescribers more flexibility, which may support prescription durability but does not radically change the near term story on its own.
The key near term catalyst is commercial execution and any color on patient adds, adherence and competition when management reports third quarter 2026 results on 4 November. The biggest risk stays the same. BioCryst remains heavily reliant on a single product in a crowded HAE market while carrying losses and negative equity.
The upcoming third quarter 2026 earnings call is the announcement that ties most closely to this approval. Investors get a near dated checkpoint on how BioCryst Pharmaceuticals is handling pricing, payer access and switching behavior now that physicians can toggle between capsules and pellets for ORLADEYO.
Listen for management commentary on prescription trends, gross to net dynamics and any early operational feedback on the oral pellets. It also matters how management describes spending on Netherton syndrome, diabetic macular edema and other programs, because elevated R&D and negative shareholders equity increase the stakes around every new commercial update.
BioCryst Pharmaceuticals' narrative projects US$930.1 million revenue and US$131.3 million earnings by 2029. This assumes 1.6% yearly revenue growth and an earnings change of roughly US$589.3 million from a current loss of US$458.0 million to the forecast US$131.3 million.
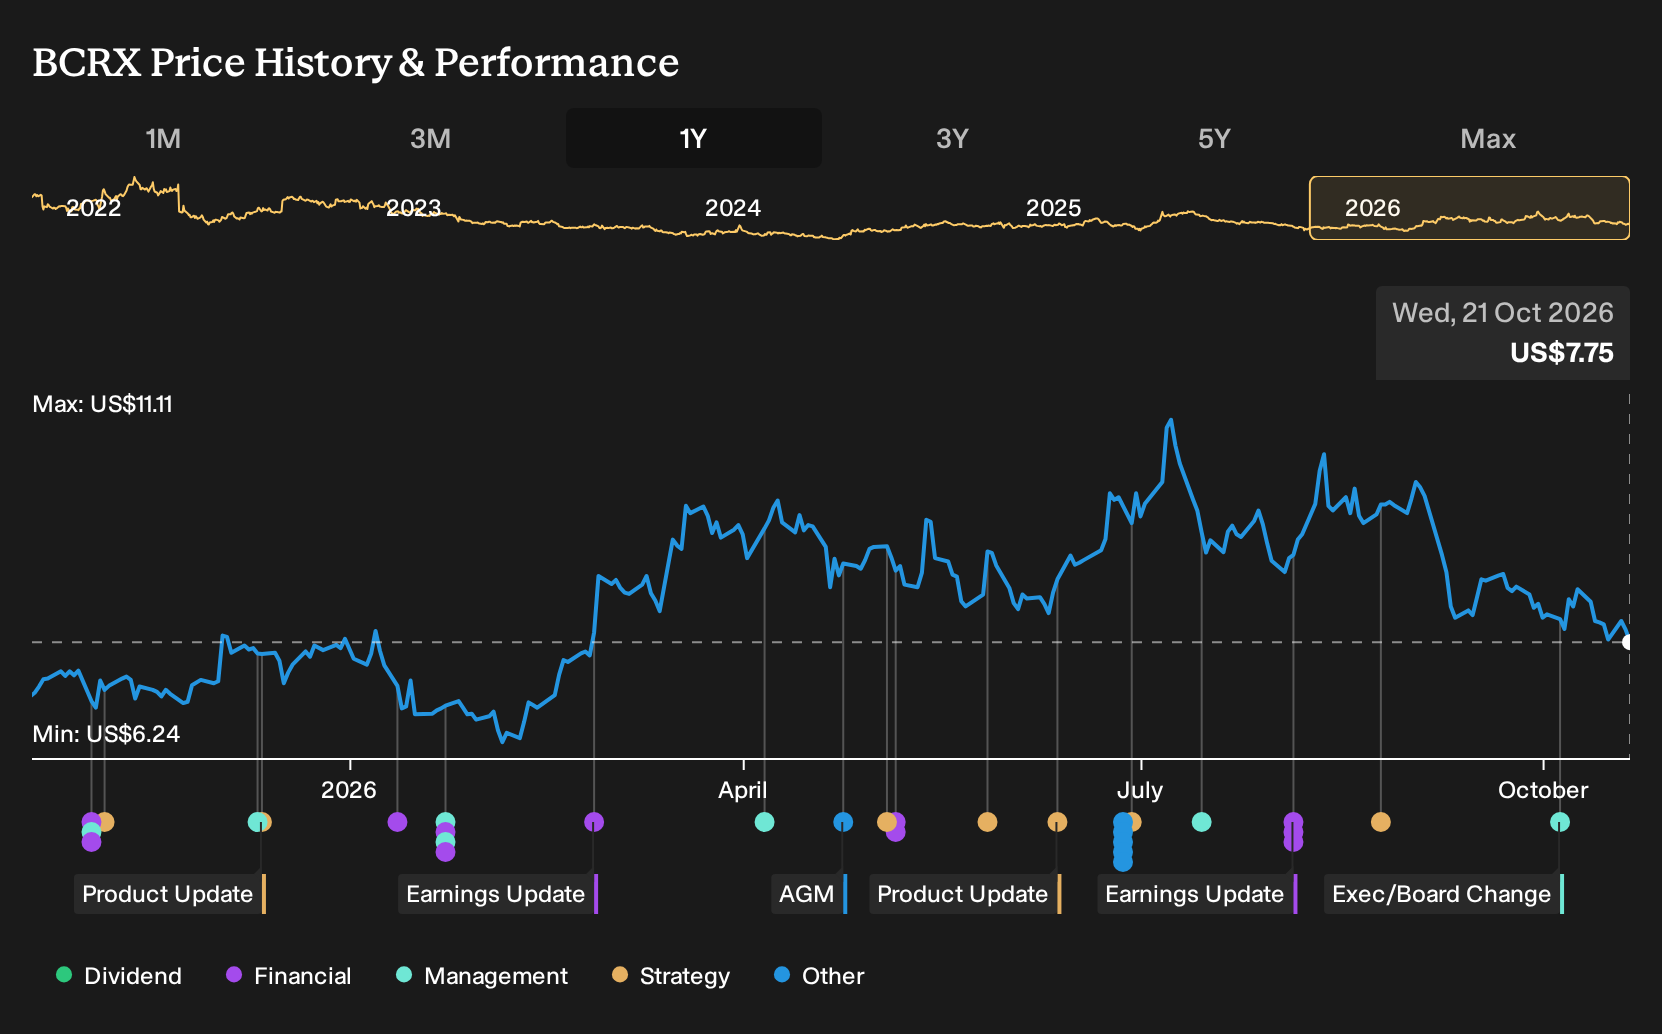
Uncover why BioCryst Pharmaceuticals' fair value indicates a 175% potential upside to its current price. This opportunity could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate angle on BioCryst Pharmaceuticals focuses on the bullish view that early ORLADEYO pellets uptake in children hints at a broader, longer HAE franchise. Those analysts were already pencilling in about US$1.0b of 2029 revenue and US$723.7 million of earnings before this pellet approval. You can compare that optimism with your own expectations and decide whether this fresh formulation could shift forecasts again.
Explore 3 other BioCryst Pharmaceuticals fair value estimates, including one that suggests as much as 1017% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BioCryst Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioCryst Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioCryst Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond BioCryst Pharmaceuticals?
Once you have a view on BioCryst Pharmaceuticals, it can help to compare that with other opportunities that fit your risk profile, income needs, or balance sheet preferences. The Simply Wall St Screener gives you a quick way to do that side by side.
- For investors hunting for smaller companies with higher risk and potentially higher volatility, consider scanning a curated set of 10 elite penny stocks with strong financials that already clear basic financial quality checks.
- If your priority is finding companies that combine quality fundamentals with share prices that may sit below intrinsic value estimates, take a look at this focused list of 33 high quality undervalued stocks tailored to that brief.
- For a steadier profile that leans on financial strength, you can filter for a list of solid balance sheet and fundamentals (25 results) and use it as a starting universe for further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com