
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Deutsche Bank Wants You to Buy the Dip in CoreWeave Stock
Artificial intelligence (AI) is triggering an infrastructure race, and companies that can deliver the computing power behind the AI boom are sitting in an enviable spot. That is where CoreWeave (CRWV) comes in. The specialized cloud provider is riding demand for AI computing, backed by hefty customer commitments and a growing revenue backlog.
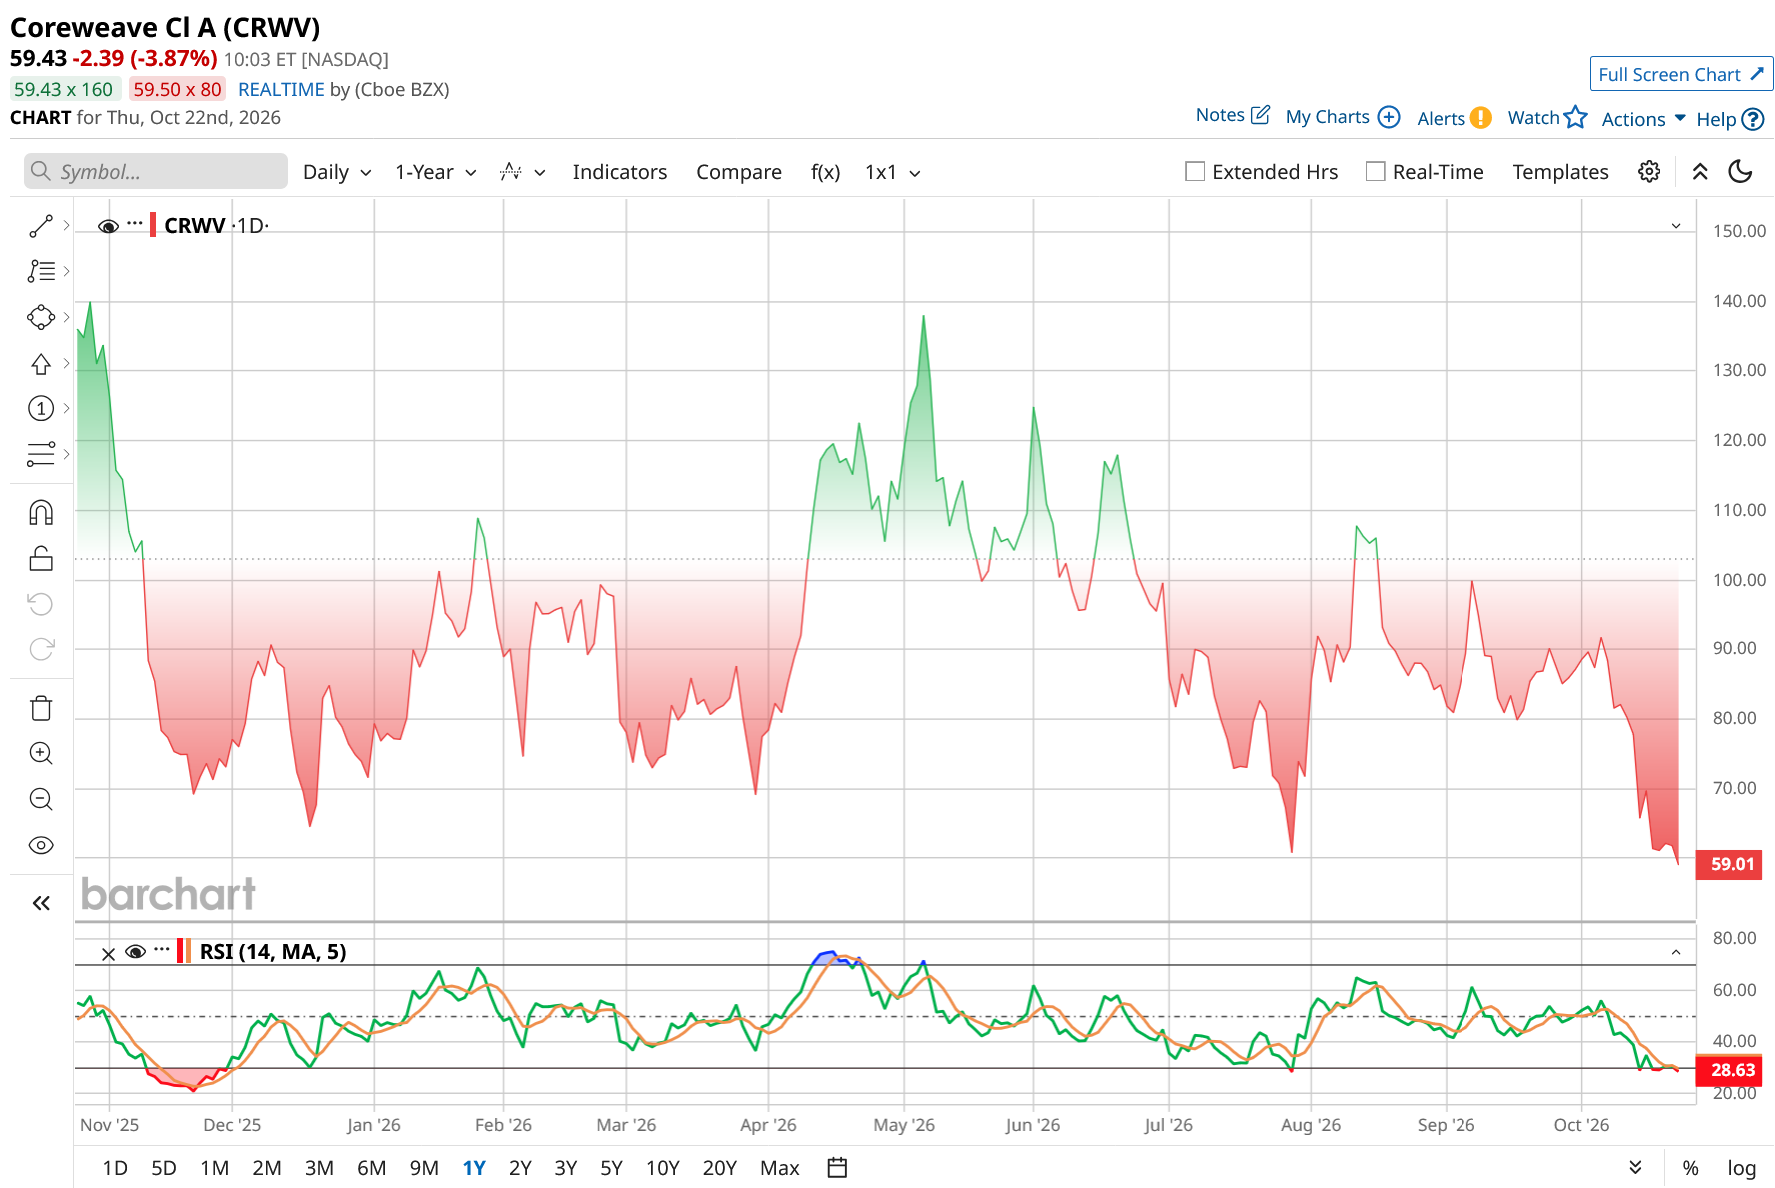
CoreWeave’s stock has been falling hard, and CRWV recently hit a low of $57.24 amid mounting anxiety over its debt load approaching $50 billion, bond yields climbing above 15%, and a broader selloff in AI infrastructure stocks. Apparently, investors love the AI boom until they see the bill for building it.
Deutsche Bank, however, thinks the market may be overreacting. Analyst Brad Zelnick reiterated a “Buy” rating and a $150 price target. He thinks CoreWeave’s long-term, take-or-pay contracts and substantial backlog provide visibility into future revenue and help cover the costs of building and operating its infrastructure.
But with billions more needed to fund expansion, is this dip a golden opportunity, as the analyst thinks? Let’s take a closer look.
About CoreWeave Stock
CoreWeave, founded in 2017 and headquartered in Livingston, New Jersey, has rapidly established itself as a leader in GPU-optimized cloud infrastructure. With a market capitalization of $28.5 billion, the company supports the accelerating AI revolution through systems designed for generative AI and large-scale compute workloads. Its mission is to streamline modern AI complexity and empower enterprises to deploy intelligence at scale, positioning CoreWeave as a foundational pillar of next-generation technology.
CoreWeave has given investors quite a ride since its stock market debut in March 2025 at $40 per share. Fueled by a steady stream of AI cloud deals, strategic partnerships, acquisitions, and federal contracts, the stock rallied to a record closing high of $183.58 on June 20, 2025. But the excitement has since given way to some serious jitters.
Fast-forward to 2026, and CRWV stock hit a low of $57.24 on Oct. 20, recovering about 3% from that level. Even so, the damage has been substantial. Shares are down 52% over the past 52 weeks and 18% on a year-to-date (YTD) basis. Over the past six months, the stock has plunged 52%, including a 32% decline in just over the past month.
Much of the pressure stems from growing concerns about CoreWeave’s debt-fueled expansion. The loss-making AI cloud provider carries roughly $50 billion in debt, while yields on some of its bonds have climbed to around 15% to 16%. Investors are increasingly questioning whether future AI revenue can justify the enormous cost of building data centers. Those worries have also spilled into the broader AI sector.
Technically, the picture remains weak. CoreWeave’s 14-day relative strength index (RSI) sits at 28.63, just below the commonly watched oversold threshold of 30. That suggests selling pressure has been intense, although an oversold reading does not guarantee a rebound. For now, investors are weighing CoreWeave’s growth opportunities against the financial risks of funding its ambitious expansion.
CoreWeave’s Q2 Numbers Top Projections
CoreWeave’s second-quarter 2026 results showed just how much demand for AI computing power is driving its business, but also how expensive it is to keep up with that demand. The AI infrastructure provider reported revenue of $2.6 billion, up a whopping 112.5% year-over-year (YoY) and ahead of Wall Street’s expectations. That kind of growth is difficult to ignore. However, the bottom line was less impressive, with adjusted operating margins slipping and the company posting a net loss of $1.14 per share. However, the loss was narrower than analysts had anticipated.
Still, CoreWeave’s future business pipeline may be its biggest selling point. As of June 30, its backlog had surged 246% YoY to $104.2 billion, supported by broader demand from enterprise and AI-native customers. That figure excludes another $25 billion in new customer commitments. Better yet, newly signed agreements carried terms that were five to 10 percentage points more favorable than those secured in the previous period, potentially setting the stage for better operating leverage as deployments scale.
Cash generation also improved considerably. CoreWeave produced $679 million in net cash from operating activities, compared with an outflow of $251 million a year earlier, and ended June with $5.5 billion in cash.
Looking ahead, management expects third-quarter revenue of $3.45 billion to $3.60 billion, implying 159.2% YoY growth at the midpoint. Adjusted operating income is projected at $200 million to $260 million. For fiscal 2026, revenue guidance stands at $12.4 billion to $13.2 billion.
The catch is the price of expansion. Q3 capital expenditures are expected to reach $11.5 billion to $13.5 billion, while full-year spending is forecast at $35 billion to $39 billion.
CoreWeave expects to finish 2026 with 1.85 gigawatts (GW) of active power capacity, up from its previous 1.7 GW target. During Q2, it added nearly 500 megawatts, bringing active capacity to 1.5 GW and total contracted power to 3.7 GW.
CEO Mike Intrator says the company remains firmly on track to reach at least 8 GW by 2030. The opportunity is enormous, but so is the spending commitment. For investors, the key question is whether CoreWeave can turn its staggering backlog and rapid expansion into sustainable profits without letting infrastructure costs get out of hand.
Analysts tracking CoreWeave anticipate the company’s Q3 revenue to be around $3.5 billion, while losses are estimated at $1.46 per share. Fiscal 2026 revenue is expected to be around $12.9 billion, while losses are expected to continue, pegged at $4.95 per share, widening by 84% YoY. The turnaround might start showing in fiscal 2027, when losses are expected to shrink by 35.8% annually and come down to $3.18 per share.
What Do Analysts Expect for CRWV Stock?
CRWV stock's recent selloff appears more like an opportunity than a reason to run for the exits, according to Deutsche Bank analyst Brad Zelnick. He maintained a “Buy” rating and a $150 price target, arguing that market fears have overshadowed the strength of the company’s underlying contracts.
Zelnick acknowledges that CoreWeave’s fortunes are closely tied to AI demand and shifting investor sentiment. Still, he points to long-term take-or-pay agreements that cover associated operating and capital costs while generating returns. He estimates that 60% to 65% of the company’s backlog came from investment-grade customers at the end of Q2. These contracts also help CoreWeave secure project-specific financing at rates at or below its parent-level cost of capital.
Deutsche Bank forecasts roughly $10 billion in operating cash flow over the next 12 months against about $45 billion in capital spending. Zelnick believes the funding gap can be addressed gradually, supported by the backlog, despite the need to raise more capital.
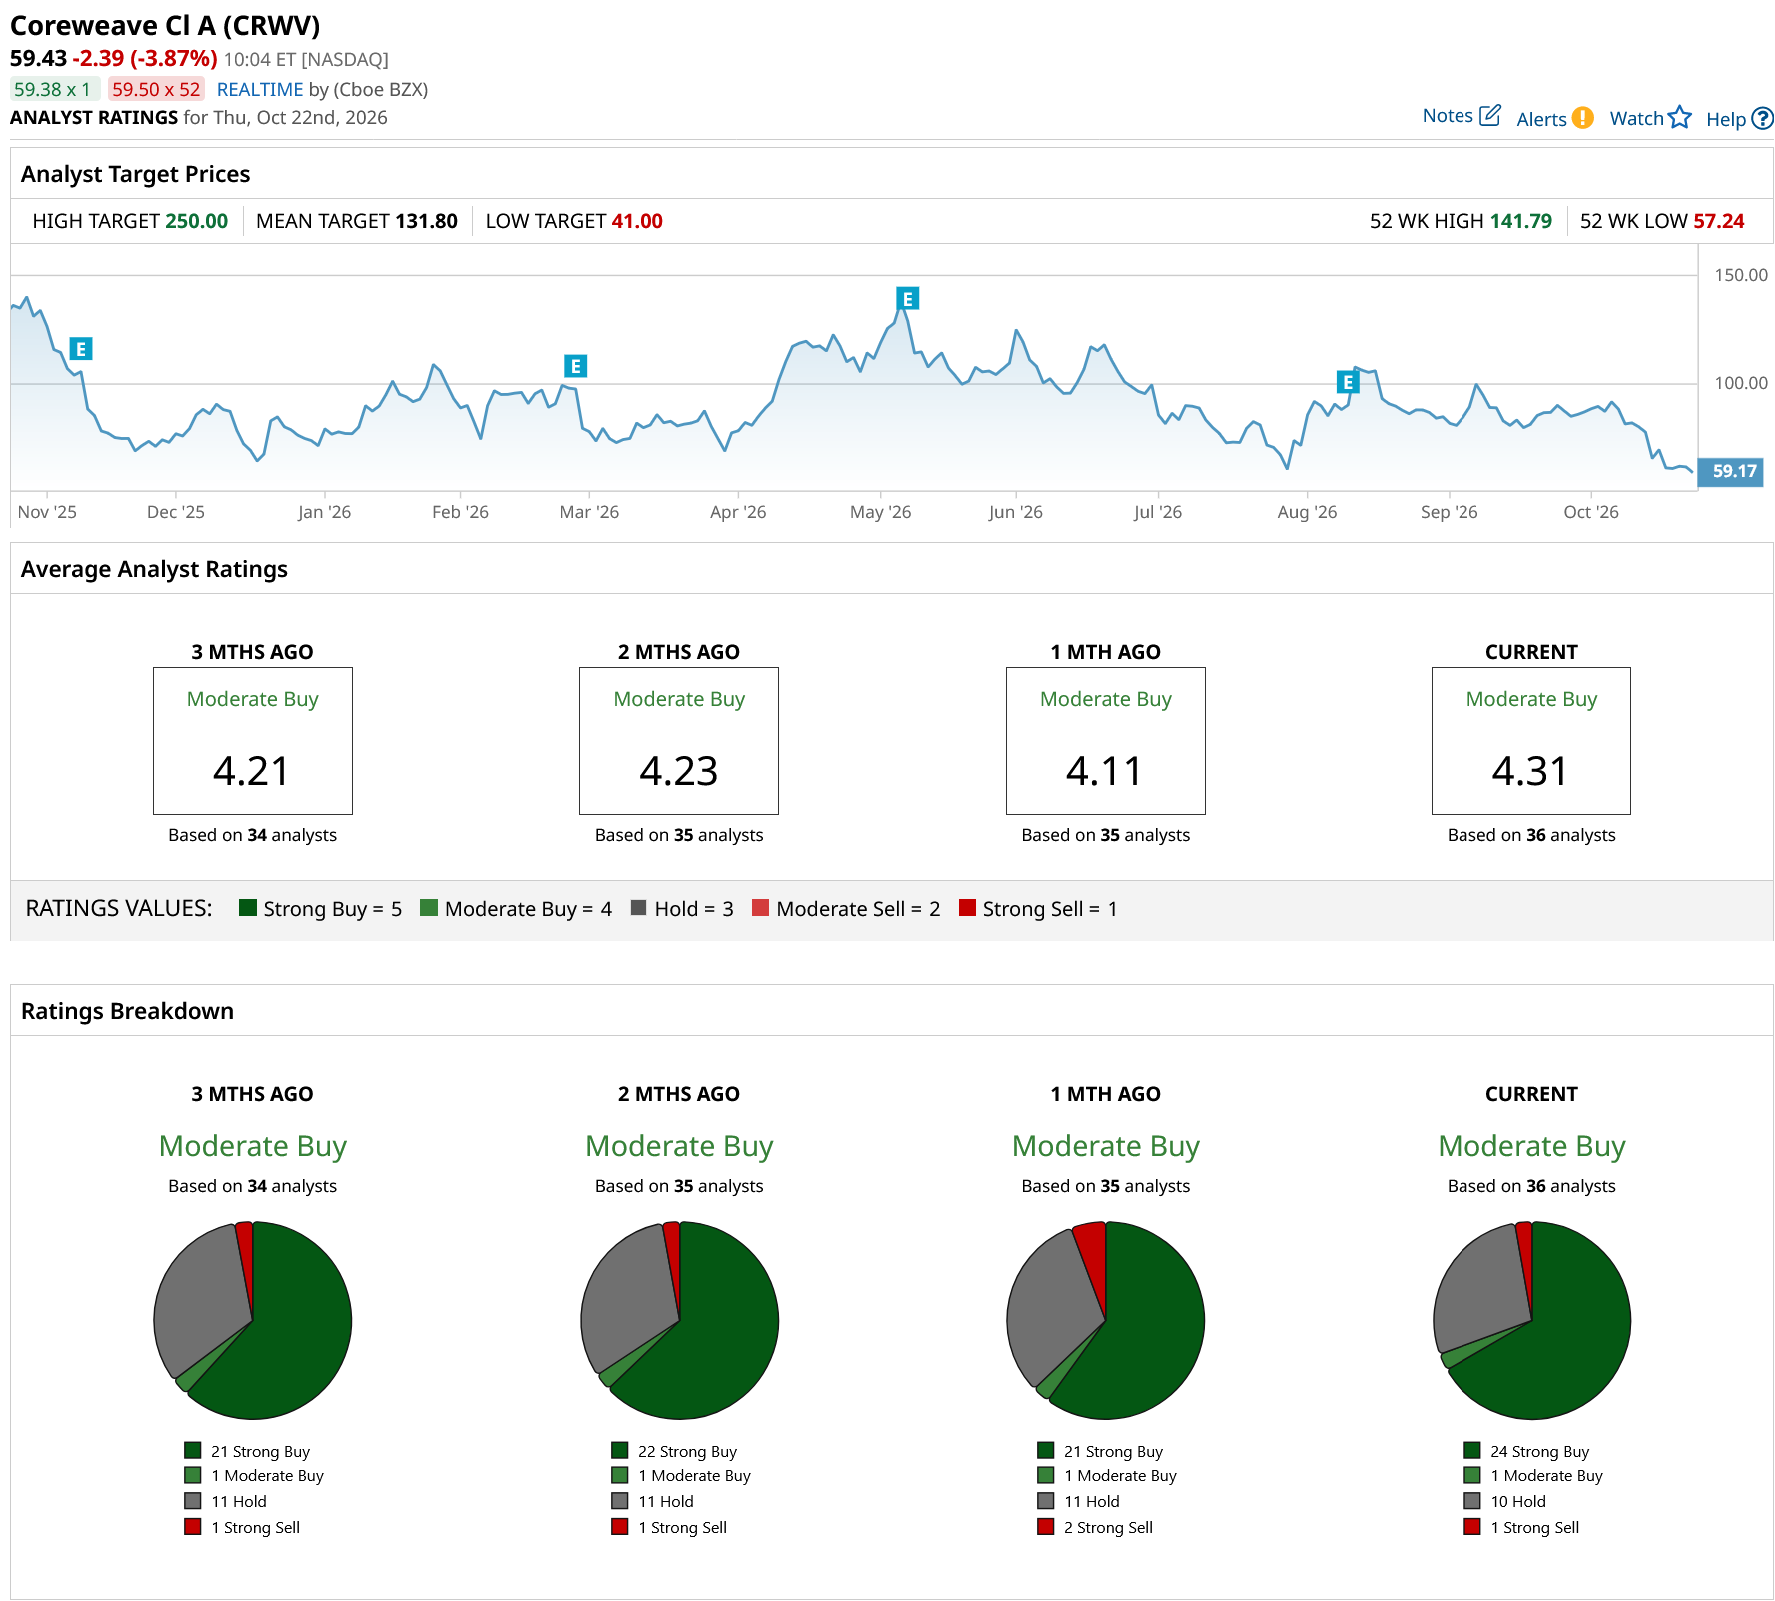
The consensus rating on CRWV stock remains at “Moderate Buy.” Among 36 analysts covering the stock now, 24 advise a “Strong Buy,” one suggests a “Moderate Buy,” 10 analysts are playing it safe with a “Hold” rating, and the remaining one analyst remains skeptical with a “Strong Sell.”
The average target of $131.80 signals nearly 122% rebound potential, and the Street-high target of $250 suggests that the stock could rise as much as 321%.
On the date of publication, Sristi Suman Jayaswal did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.