
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should AI Security Expansion Require Action From Palo Alto Networks (PANW) Investors?
- Palo Alto Networks is pushing deeper into AI-driven security, combining its new agentic endpoint strategy after the Koi acquisition with more than 100 recent customer wins and closer NVIDIA collaboration on securing autonomous AI.
- The emergency PHP vulnerabilities that affected much of the web have sharpened attention on vendors like Palo Alto Networks that focus on high stakes, large scale threat protection across applications and devices.
- We will now look at how Palo Alto Networks' push into AI-driven endpoint protection could influence its broader investment narrative.
Palo Alto Networks Investment Narrative Recap
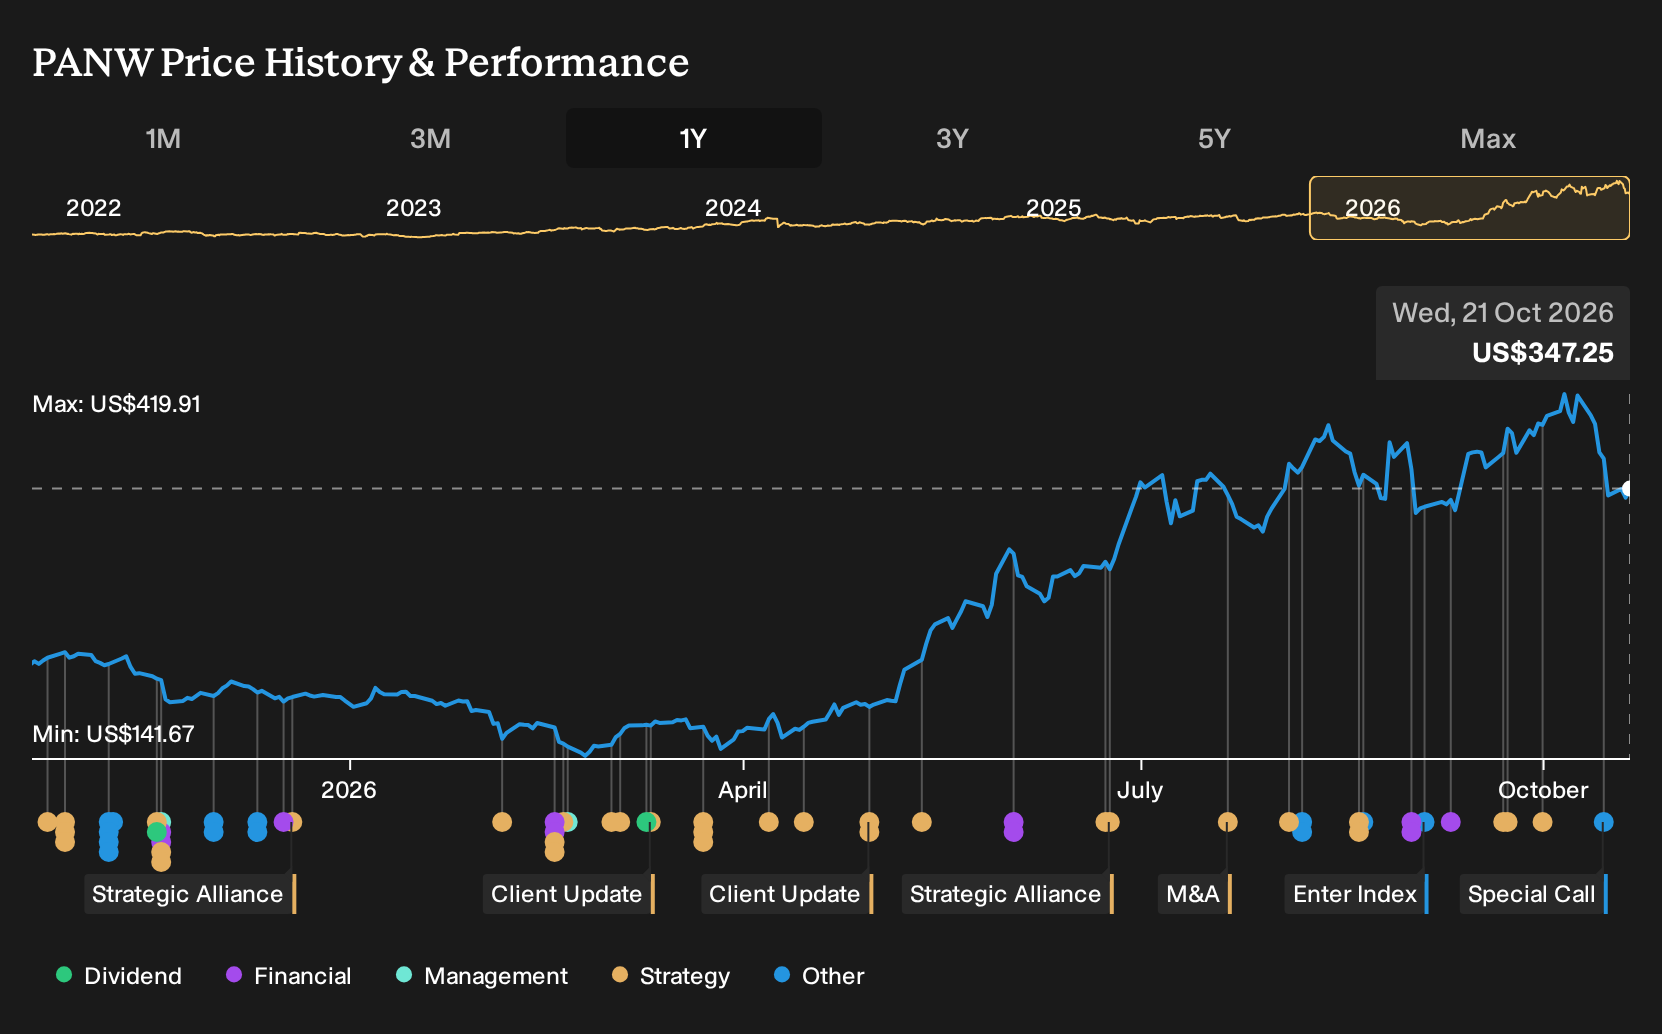
To own Palo Alto Networks, you need to believe its broad security platform and AI-led offerings can turn today’s elevated investment in acquisitions and AI into durable subscription revenue. The recent pullback while the market rose highlights how sensitive the stock is to expectations for the next earnings report and any sign of slower adoption.
The key near-term catalyst is execution on AI-focused products like Prisma AIRS and the new agentic endpoint push, alongside evidence that Next Generation Security ARR is scaling efficiently. The biggest risk is that integration complexity, rising cloud and hardware costs, and high stock-based compensation keep margins and earnings per share from tracking that growth.
The most relevant update is Palo Alto Networks’ expanded AI security collaboration with NVIDIA through the OpenShell Reference Architecture. That puts the company directly in the conversation for securing autonomous AI workloads, where paying customers will care less about hype and more about measurable protection from real-world attacks.
For you, this matters because it tightens the link between Palo Alto Networks’ AI narrative and concrete deployment on high-value infrastructure. Execution risk remains, from integrating past acquisitions to controlling gross margin pressure and dilution, yet each new embedded partnership like this one gives the firm another potential on-ramp for recurring software and services revenue tied to AI security budgets.
Palo Alto Networks' current analyst script points to revenues of US$18.5b and earnings of US$2.6b by 2029, based on an assumed 17.3% yearly revenue growth rate and an earnings increase of roughly US$2.3b from US$307.0m today.
Uncover why Palo Alto Networks' fair value indicates a 14% potential upside to its current price, a discount that could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate view plays up Palo Alto Networks’ AI exposure much more aggressively. Bulls were already modeling revenue to reach US$21.6b and earnings of US$3.6b by 2029, compared with the consensus US$18.5b and US$2.6b. Those projections came before this AI security news, so you may see those narratives shift in very different directions.
Explore 5 other Palo Alto Networks fair value estimates, including one that suggests up to 15% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Palo Alto Networks research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Palo Alto Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Palo Alto Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Palo Alto Networks?
If you like the AI security angle with Palo Alto Networks but want a broader watchlist, a few targeted stock screens can help you spot other opportunities that fit your style, whether you care most about value, resilience, or future potential.
- If capital preservation sits high on your list, filter for steadier businesses through a 31 resilient stocks with low risk scores that prioritizes resilience over drama.
- If you want income on top of potential share price moves, focus on companies with robust payouts using a curated 7 dividend fortresses that targets higher yielding candidates.
- If you are hunting for tomorrow’s potential leaders before they are widely talked about, sift through a 21 high quality undiscovered gems built around quality fundamentals and quieter coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com